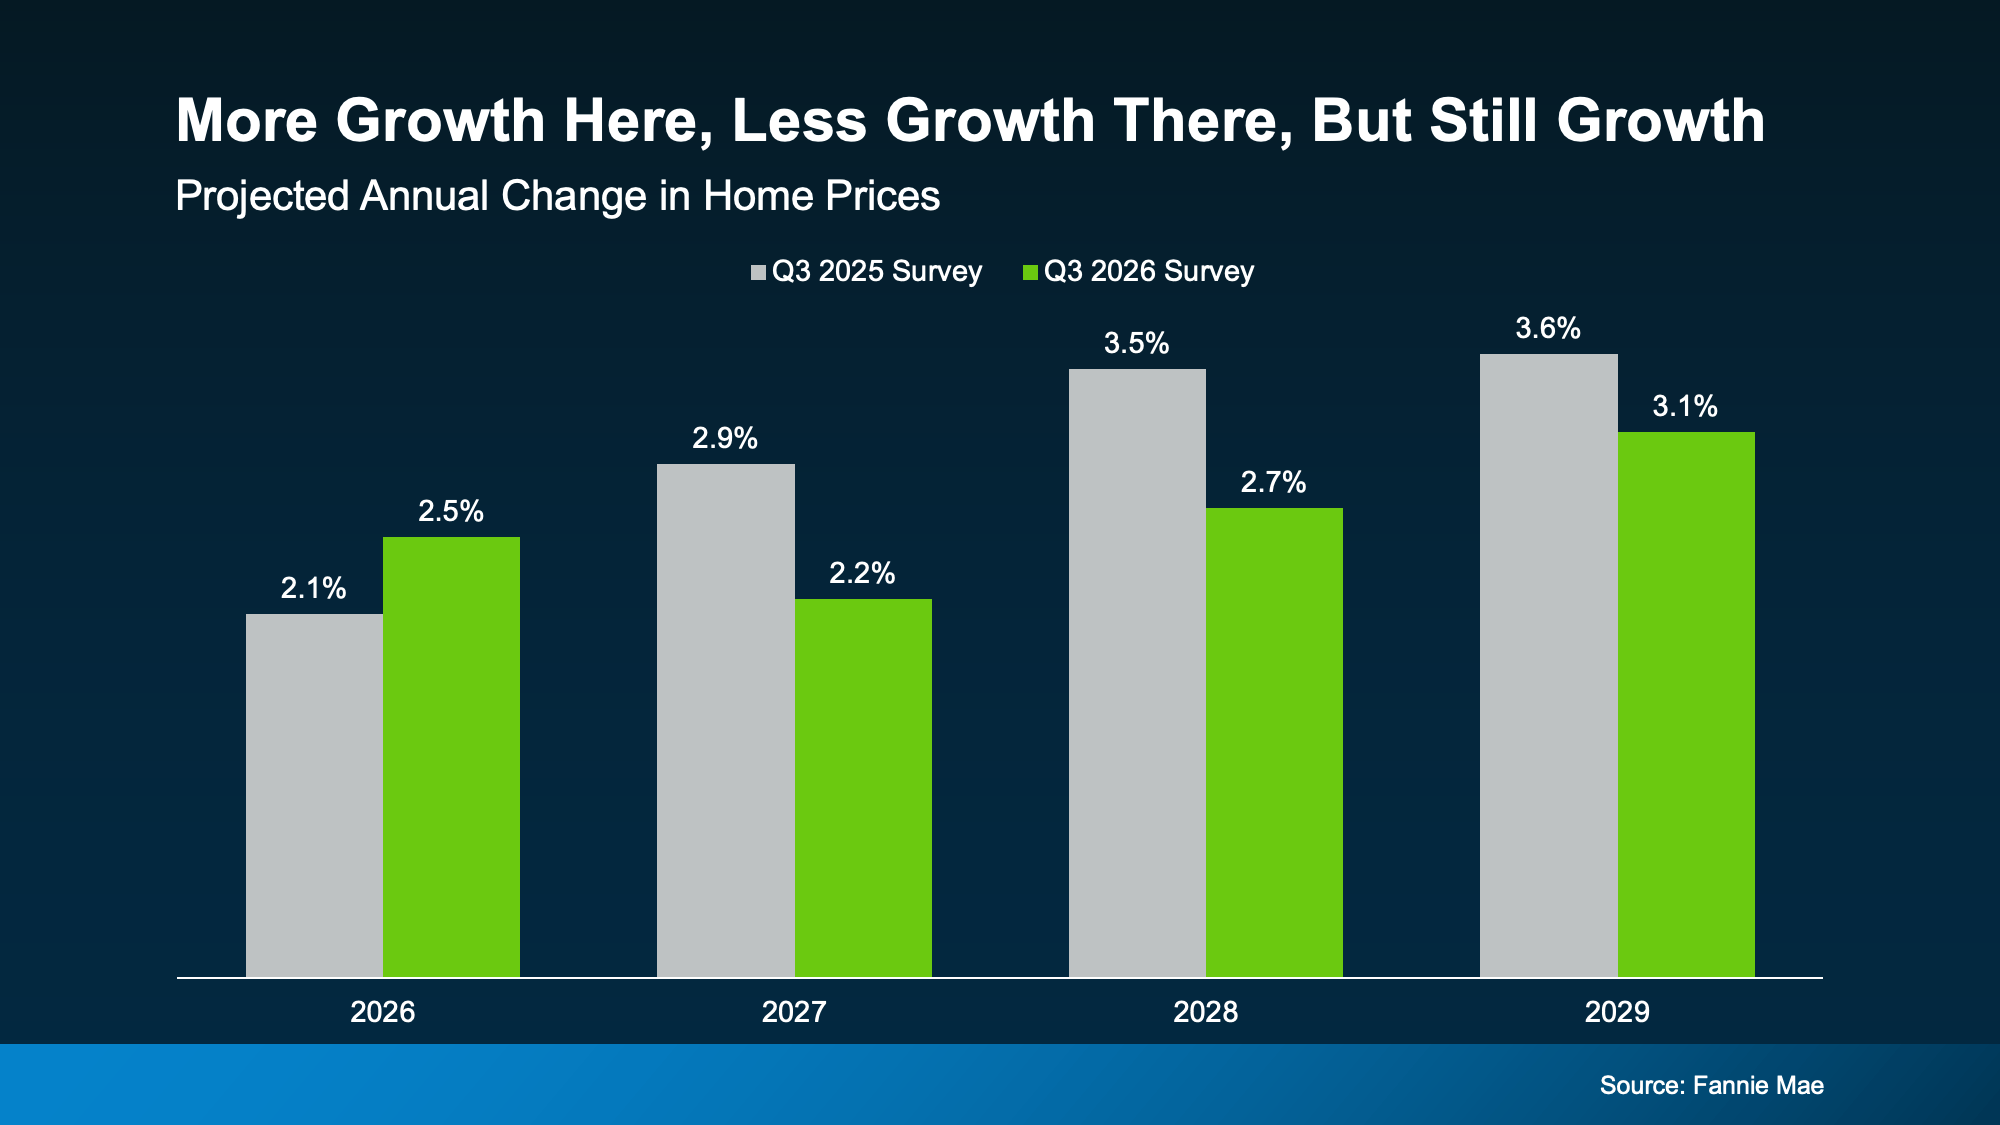
New Search

If you are not happy with the results below please do another search

344 search results for: chicken little

1
stdClass Object
(
    [agents_bottom_line] => 

The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, let's map out a plan that works at today's rates.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:16:32Z [id] => 321 [name] => Agent Value [parent] => [parent_id] => [published_at] => 2024-04-10T16:17:42Z [slug] => agent-value [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Valor del agente ) ) [updated_at] => 2024-04-10T16:17:42Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) [6] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:20:58Z [id] => 325 [name] => Economy [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:04Z [slug] => economy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Economía ) ) [updated_at] => 2024-04-10T16:21:04Z ) [7] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) ) [content_type] => blog [contents] =>

You've probably heard the Federal Reserve (the Fed) is raising rates again. And if you're planning to buy or sell a house, you may be wondering what that means for you.

With all the headlines, it’s easy to think the Fed sets mortgage rates. That’s actually a common myth. But the Fed’s decisions can still have an impact on them.

So, where does that leave you? The next few months could get a little bumpy. But the Fed is playing the long game. And with the right plan, you can still make a move that works. Let’s break it down.

Why the Fed Is Raising Rates

It all comes back to inflation. With prices rising fast, everything is getting more expensive – and that leaves buyers with less spending power and makes homes cost more to build.

So, the Fed raises its key short-term rate (the Federal Funds Rate) to slow down inflation. And that’s where a lot of people get tripped up.

  • MYTH: The Fed controls mortgage rates.

  • REALITY: The Fed has an impact on mortgage rates, but it’s only one piece of the puzzle.

As NerdWallet explains:

“The Federal Reserve influences mortgage rates, but doesn't set them. . . Mortgage rates are influenced by many elements, including the inflation rate, the pace of job creation, and whether the economy is growing or shrinking. The Federal Reserve's monetary policy is a factor, too . . .”

Here’s the simplest way to explain how it all fits together. Mortgage rates tend to follow something called the 10-year treasury yield. That’s the return investors get for lending money to the government for 10 years. And that yield moves up and down based on what investors expect from inflation and the economy.

Right now, one of the biggest things moving that yield is the conflict in Iran. It’s pushed oil prices higher, which has investors worried about inflation. That’s why any news about the conflict can move mortgage rates. If there’s resolution in Iran, that could take some pressure off inflation and mortgage rates. But the timing is hard to predict.

What the Fed does can move that yield, too. When they hike the Federal Funds Rate to fight inflation, investors pay attention. That can push the 10-year yield up, and mortgage rates usually follow. But once inflation cools, the yield has room to come back down, and mortgage rates can, too. That gives buyers some of their purchasing power back (see graphic below):
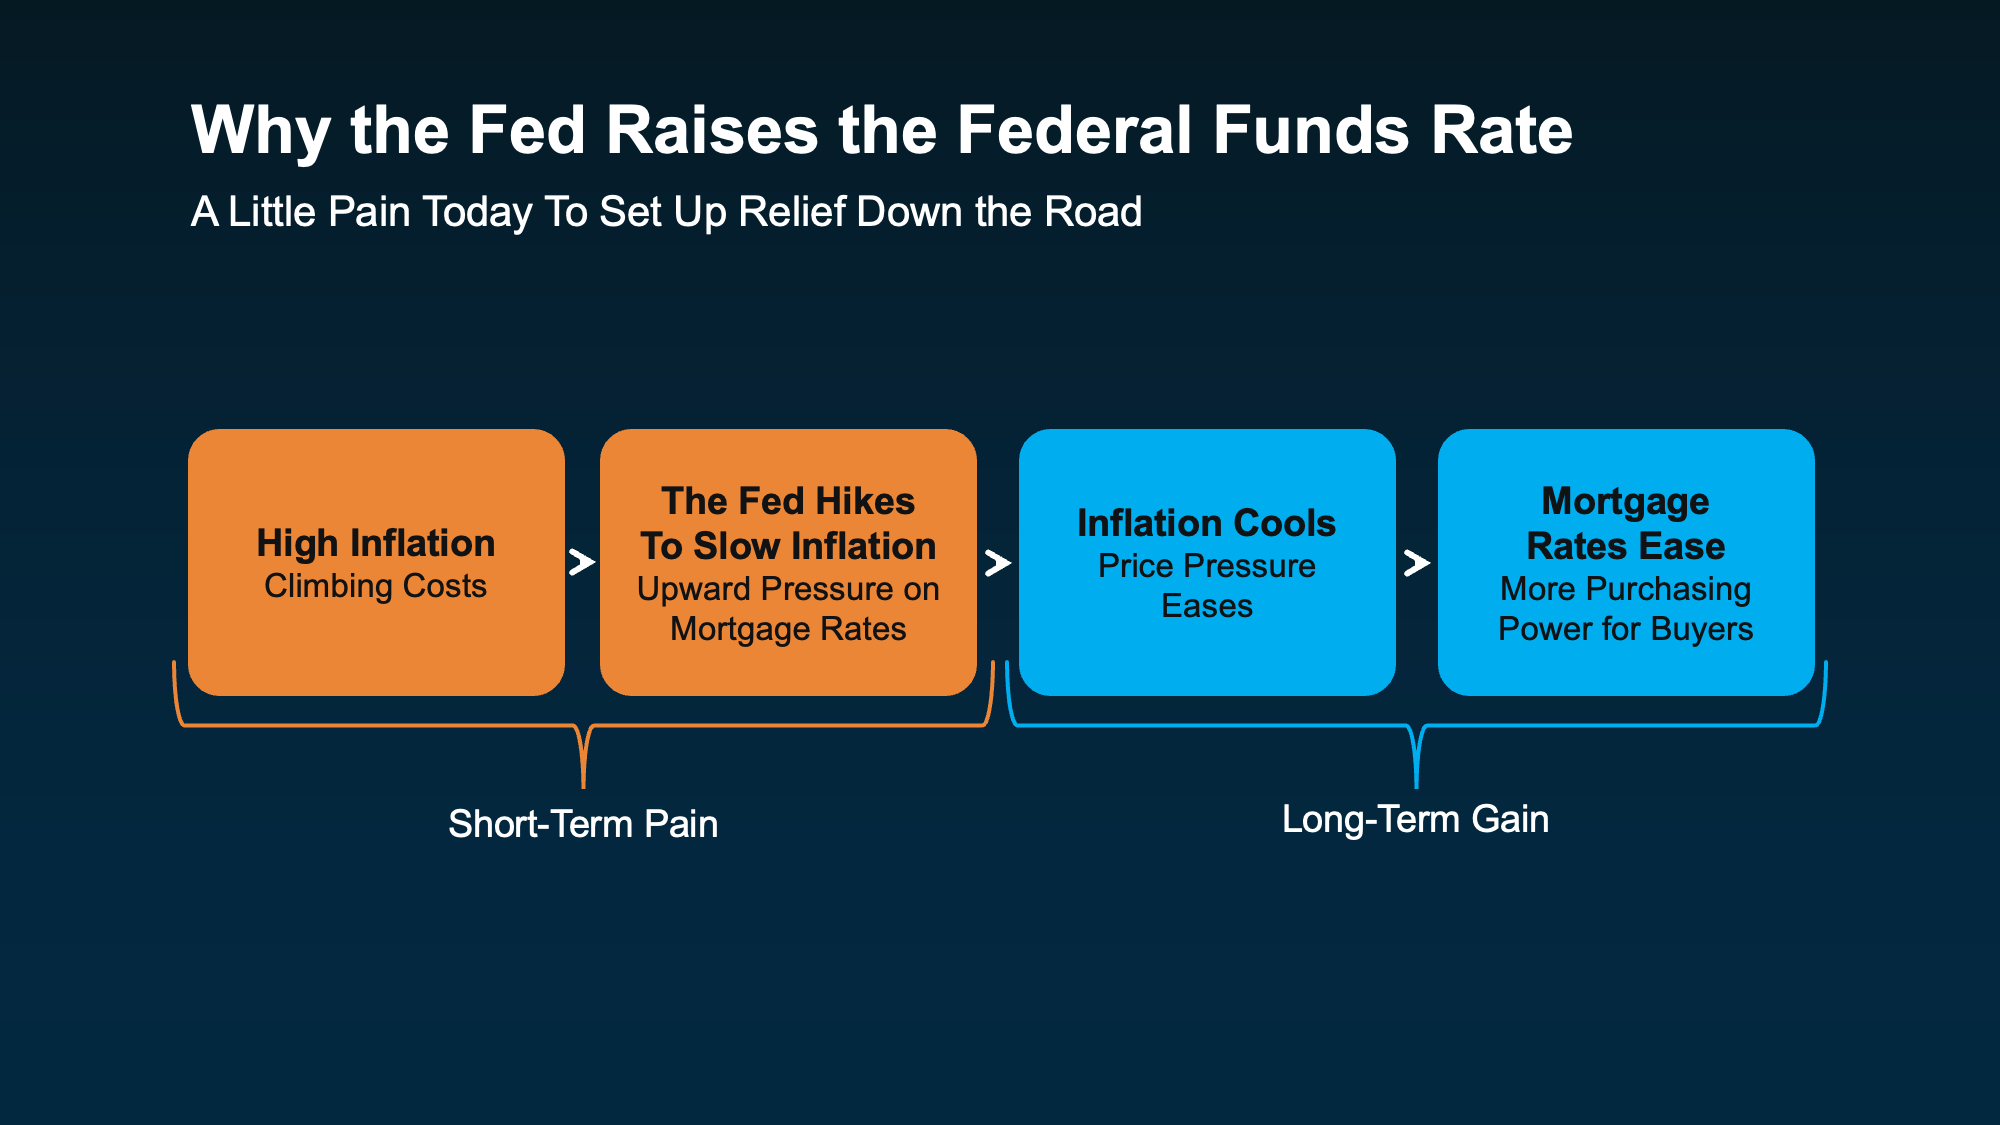
a diagram of a federal funds rate

Think of it as a little pain today to set up some relief down the road. But how long could that short-term pain last? A lot depends on what the Fed does next.

There’s a Strong Possibility the Fed Will Hike Again This Year

According to CME FedWatch, there’s over an 80% chance the Fed hikes their federal funds rate at least once more before the end of 2026 (see graph below):
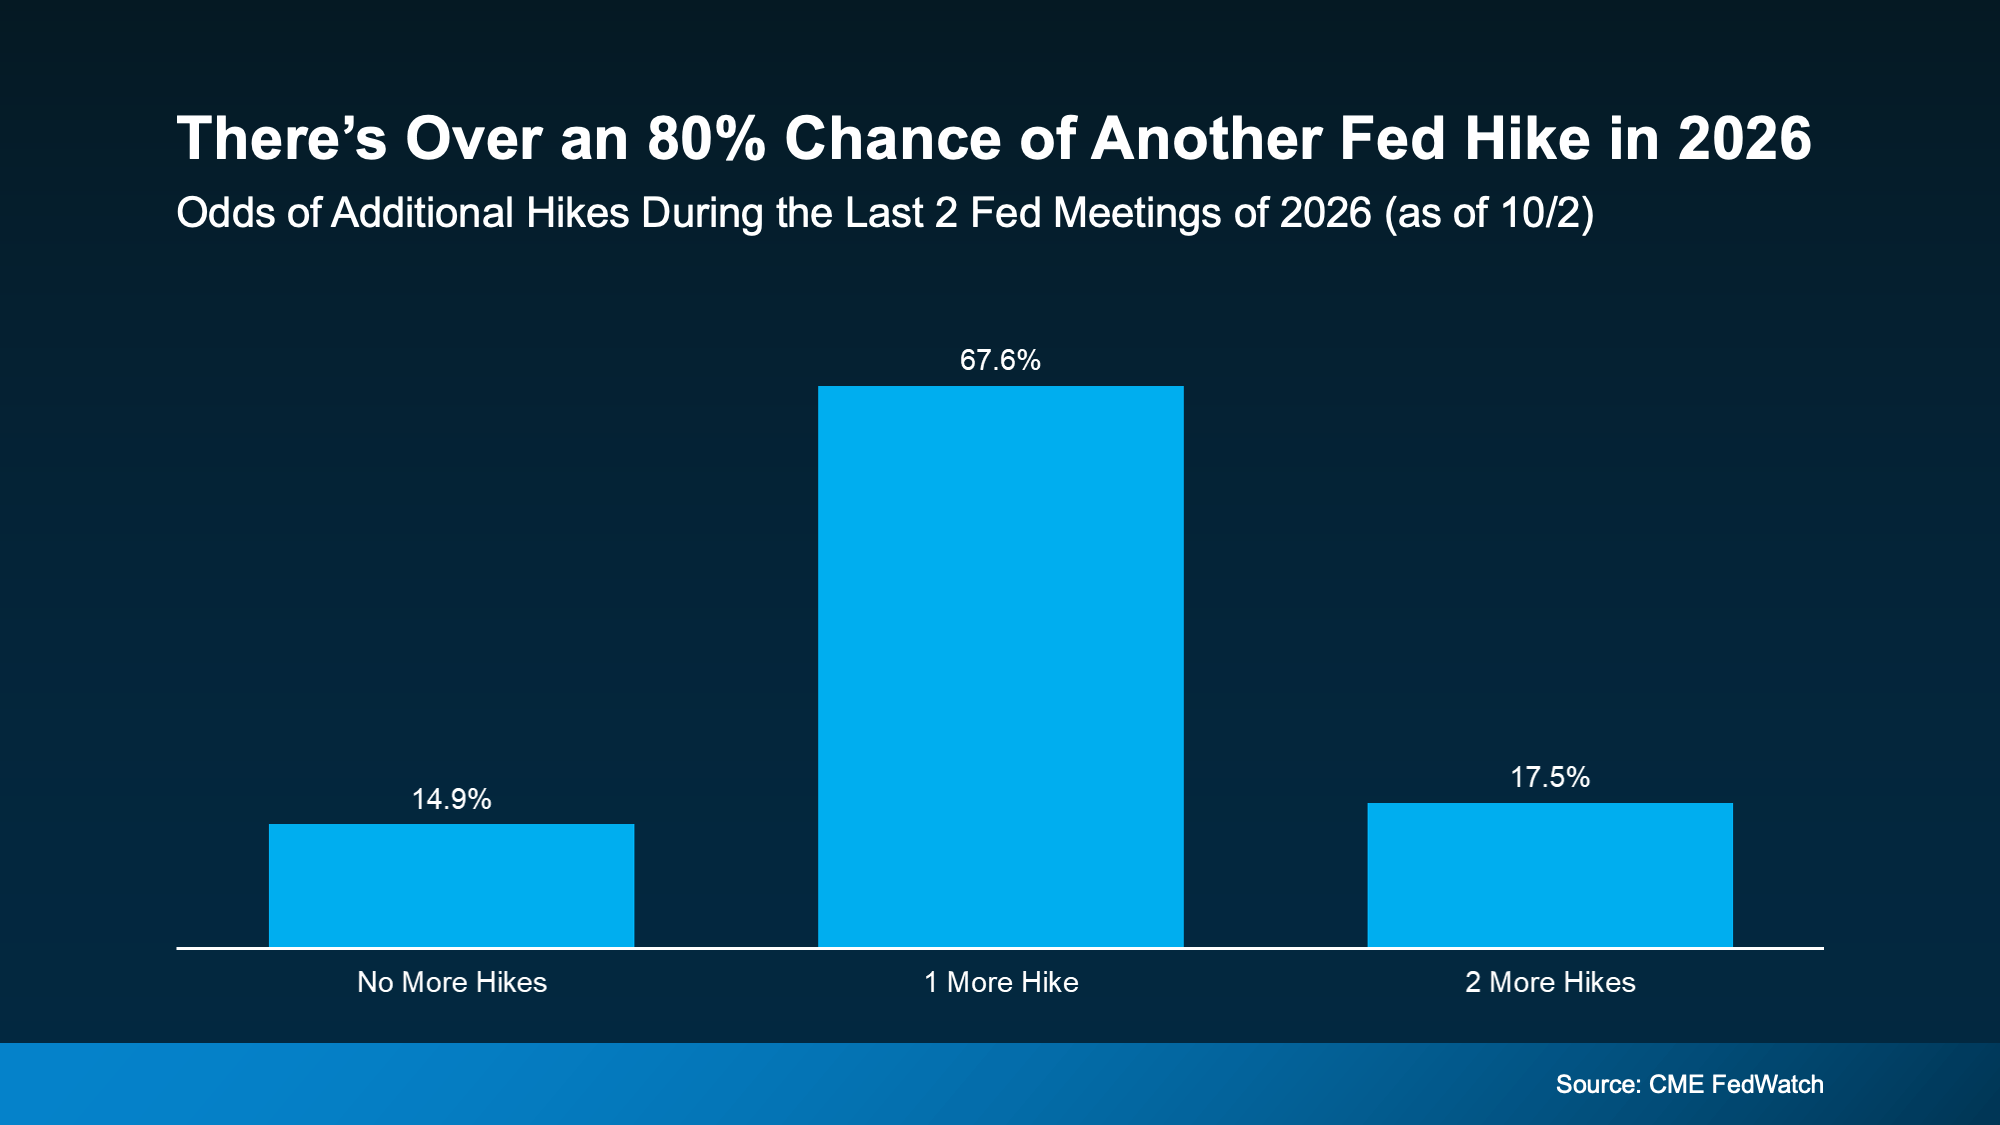
a graph of hikers with blue squares

Remember, the Fed doesn’t set mortgage rates. But another hike will likely keep upward pressure on them in the short term. So, should you wait it out? Sam Williamson, Senior Economist at First American, says this:

"Over time, firmer Fed action could help steady the bond market and open the door to lower mortgage rates, but only if investors become more confident that inflation is coming under control."

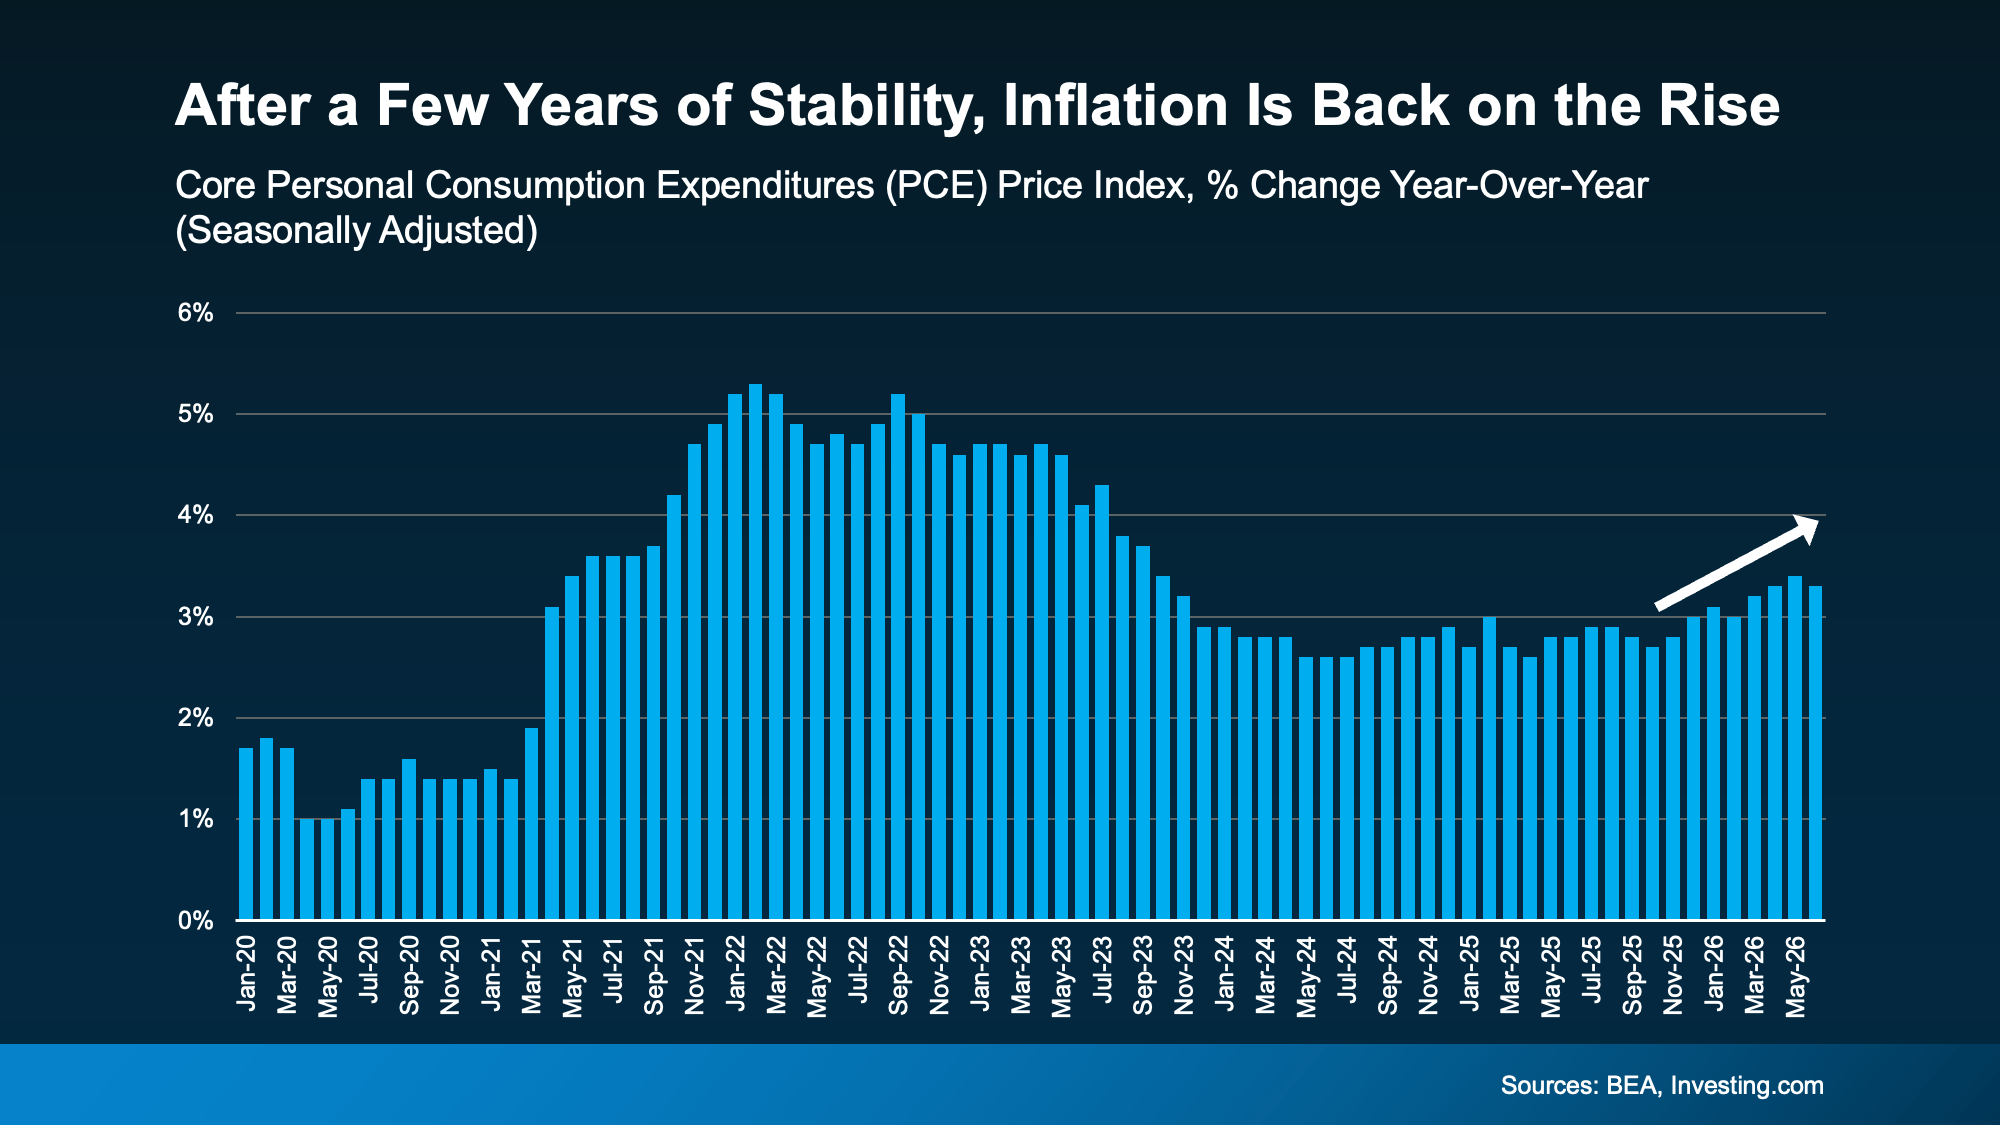
And there are some early signs that’s starting to happen. Inflation cooled faster than experts expected in August:

  • PCE inflation dropped to 3.4%, down from 3.7% in July.

  • Core PCE (the Fed’s preferred measure which leaves out food and energy prices) fell to 3%, down from 3.3%.

That’s a step in the right direction, and it’s part of why the odds of a hike at the Fed’s October meeting have come down recently. But inflation’s still above the Fed’s 2% target, and it’s been that way for about 5 years. So, lower rates could still take a while. Your best bet is a plan that works at today’s rates.

How To Make Your Move Work Right Now

While this rate hike cycle isn’t the headline you want to see, it doesn’t mean you have to wait. There are still ways to move, even now.

  • If you're buying: Get pre-approved so you know your real budget. Ask your lender about your options to get the best rate possible. And once you're under contract, lock your rate so a jump before closing doesn't raise your payment.

  • If you're selling: Decide what matters most to you – a quick sale or top dollar. Each one can call for a different plan. Price for today's buyers, whose budgets are smaller with higher rates. And think about offering a rate buydown or other concession. They can do more for a buyer’s budget than a price cut.

[created_at] => 2026-10-06T15:42:09Z [description] =>

You've probably heard the Federal Reserve (the Fed) is raising rates again. And if you're planning to buy or sell a house, you may be wondering what that means for you.
[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20261006/Header-Image-GettyImages-1804102108.png [id] => 112518 [kcm_ig_caption] => The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, let's map out a plan that works at today's rates. [kcm_ig_hashtags] => MortgageRates,HomeBuying,KeepingCurrentMatters [kcm_ig_quote] => Myth vs. Reality: Does the Fed control mortgage rates? [modified] => [poll] => [public_bottom_line] =>

The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, connect with a local real estate agent to map out a plan that works at today's rates.

[published_at] => 2026-10-07T10:30:00Z [related] => Array ( ) [related_to] => Array ( ) [shares] => 0 [slug] => myth-vs-reality-does-the-fed-control-mortgage-rates [status] => published [tags] => Array ( [0] => foundations ) [title] => Myth vs. Reality: Does the Fed Control Mortgage Rates? [updated_at] => 2026-10-06T15:42:09Z [url] => /2026/10/07/myth-vs-reality-does-the-fed-control-mortgage-rates/ )

Myth vs. Reality: Does the Fed Control Mortgage Rates?

You've probably heard the Federal Reserve (the Fed) is raising rates again. And if you're planning to buy or sell a house, you may be wondering what that means for you.
2
stdClass Object
(
    [agents_bottom_line] => 

Your first home may not be as far off as it feels. When the numbers make sense for you, buying a starter home and putting down less than 20% can get you there years sooner. 

Want to see which starter homes in our area could fit your budget? Let's connect.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 53 [name] => Rent vs. Buy [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => rent-vs-buy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Alquilar Vs. Comprar ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can make owning feel further off.

But buying your first home doesn’t have to happen to feel like a far away goal. Two choices you control can bring your first home years closer, even with affordability as tight as it is right now.

How Long Buying Really Takes

First, one quick definition. "Breaking even" is the point where owning has cost you about the same as renting would have over the same period. And after that point, owning starts to cost less than renting. Kara Ng, Senior Economist at Zillow, puts it this way:

"Buyers should think about not just when they can afford to buy, but how long they'd need to stay before owning makes more financial sense than renting."

So how long does reaching that point usually take? And what are the shortcuts? Let’s do the math.

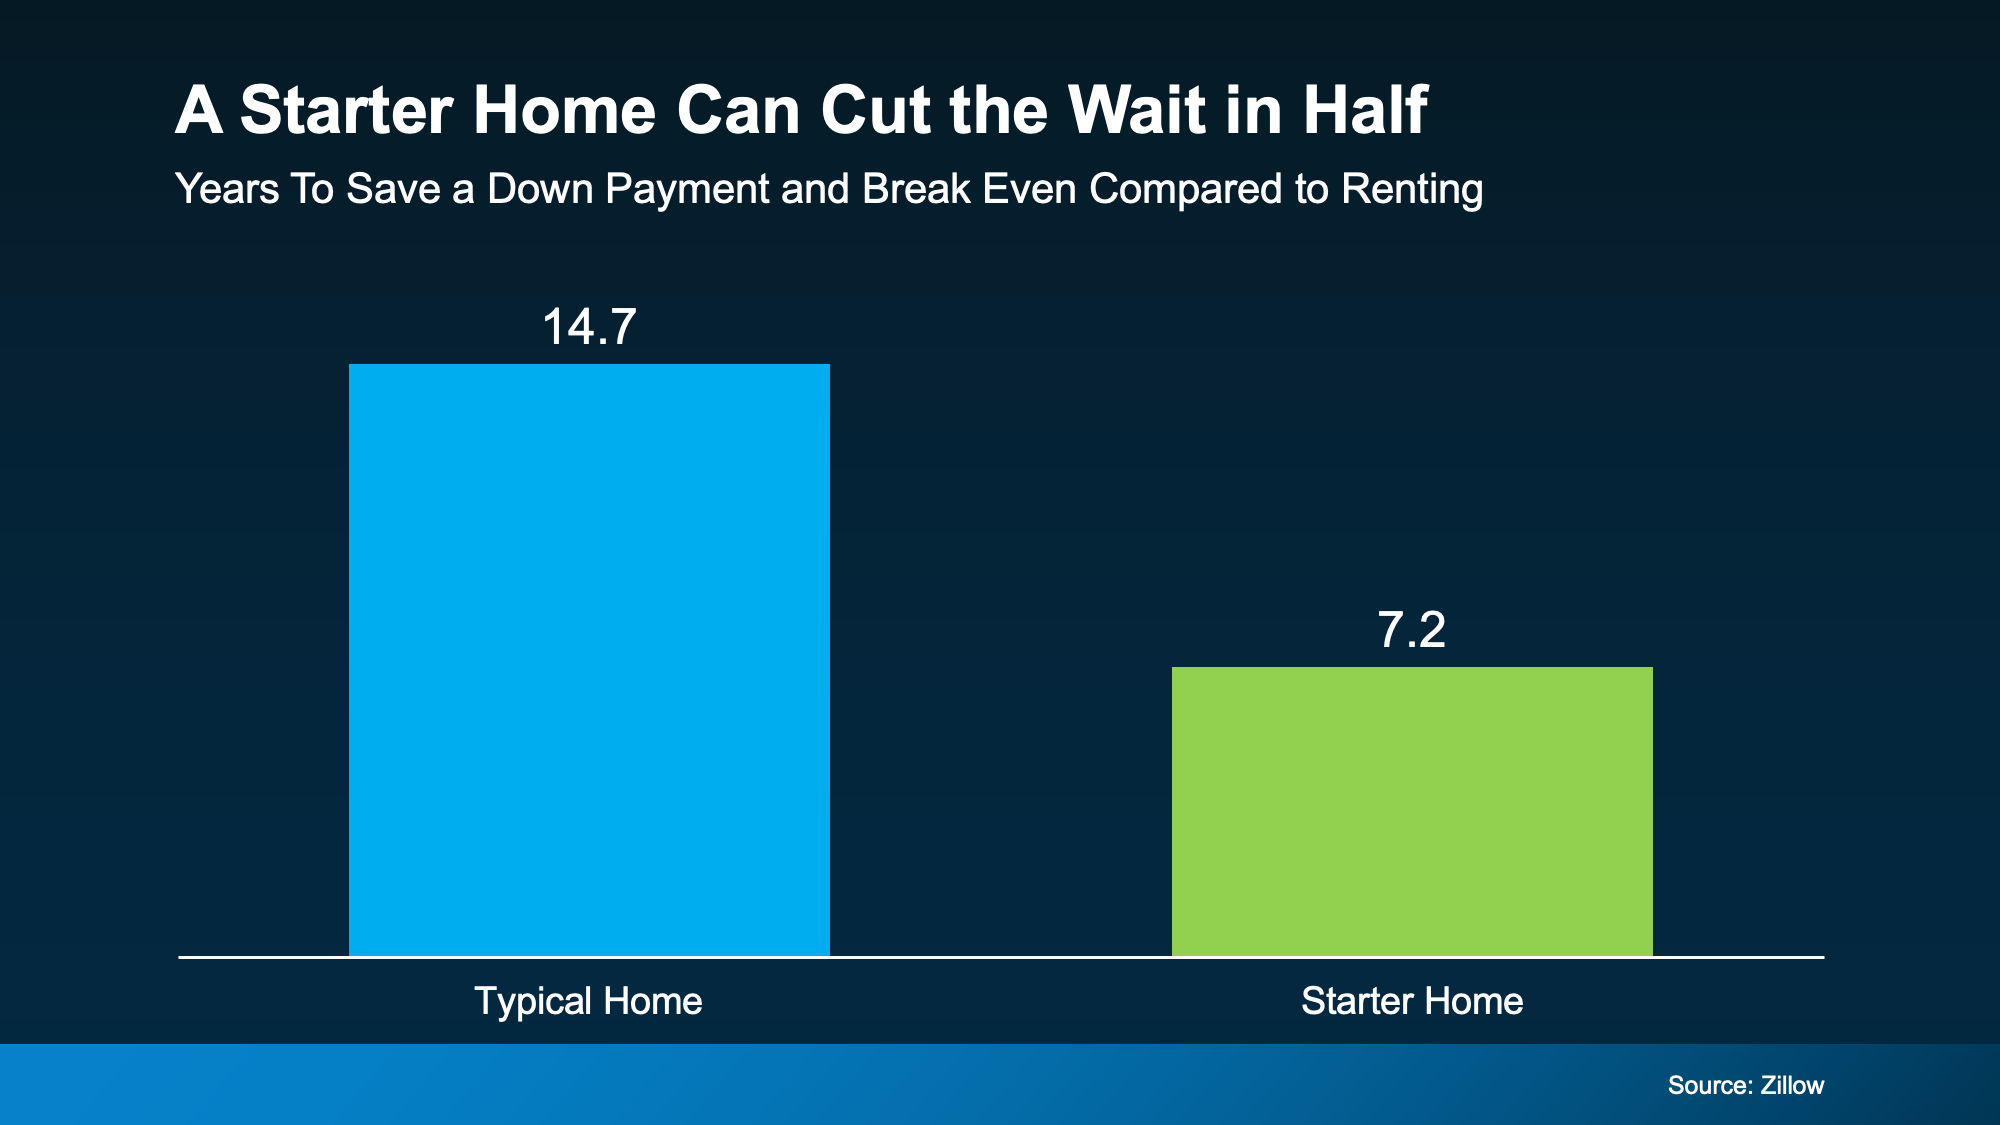
According to Zillow, it usually takes about 8.5 years to save for a 20% down payment, then roughly 6.2 more years before owning costs the same as renting. Together, that's just under 15 years. But that math relies on two assumptions: that you're buying a mid-priced home, and that you're putting 20% down. 

Change either one and your timeline gets shorter. Change both and it can shrink fast. It also varies widely by market, since local prices and rents are different depending on where you live. 

A Starter Home Can Get You There Twice as Fast

A starter home usually means a home in the lower third of local prices. They’re often condos, townhomes, or single-family homes a little smaller or older than others in the area. 

Choosing one over a mid-priced home can cut your wait down by a lot. And while that might sound obvious, you may not realize just how much it shortens your timeline. Because if you’re buying a more affordable home, you don’t have to save up as much or as long.

Zillow found that nationwide, a starter home takes half the time – about 7.2 years – to save for and come out ahead on, compared with renting (see graph below):

a graph of a number of squares

That works out to about 4.6 years to save and 2.6 years to break even. It won't erase every affordability challenge, but it can take years off the wait. And if you’ve already been saving for a while, it could get you closer to making it a reality.

You Usually Don't Need To Put 20% Down

You, like many first-time homebuyers, might assume you need a 20% down payment to even consider buying. But a lot of the time, you don’t. 

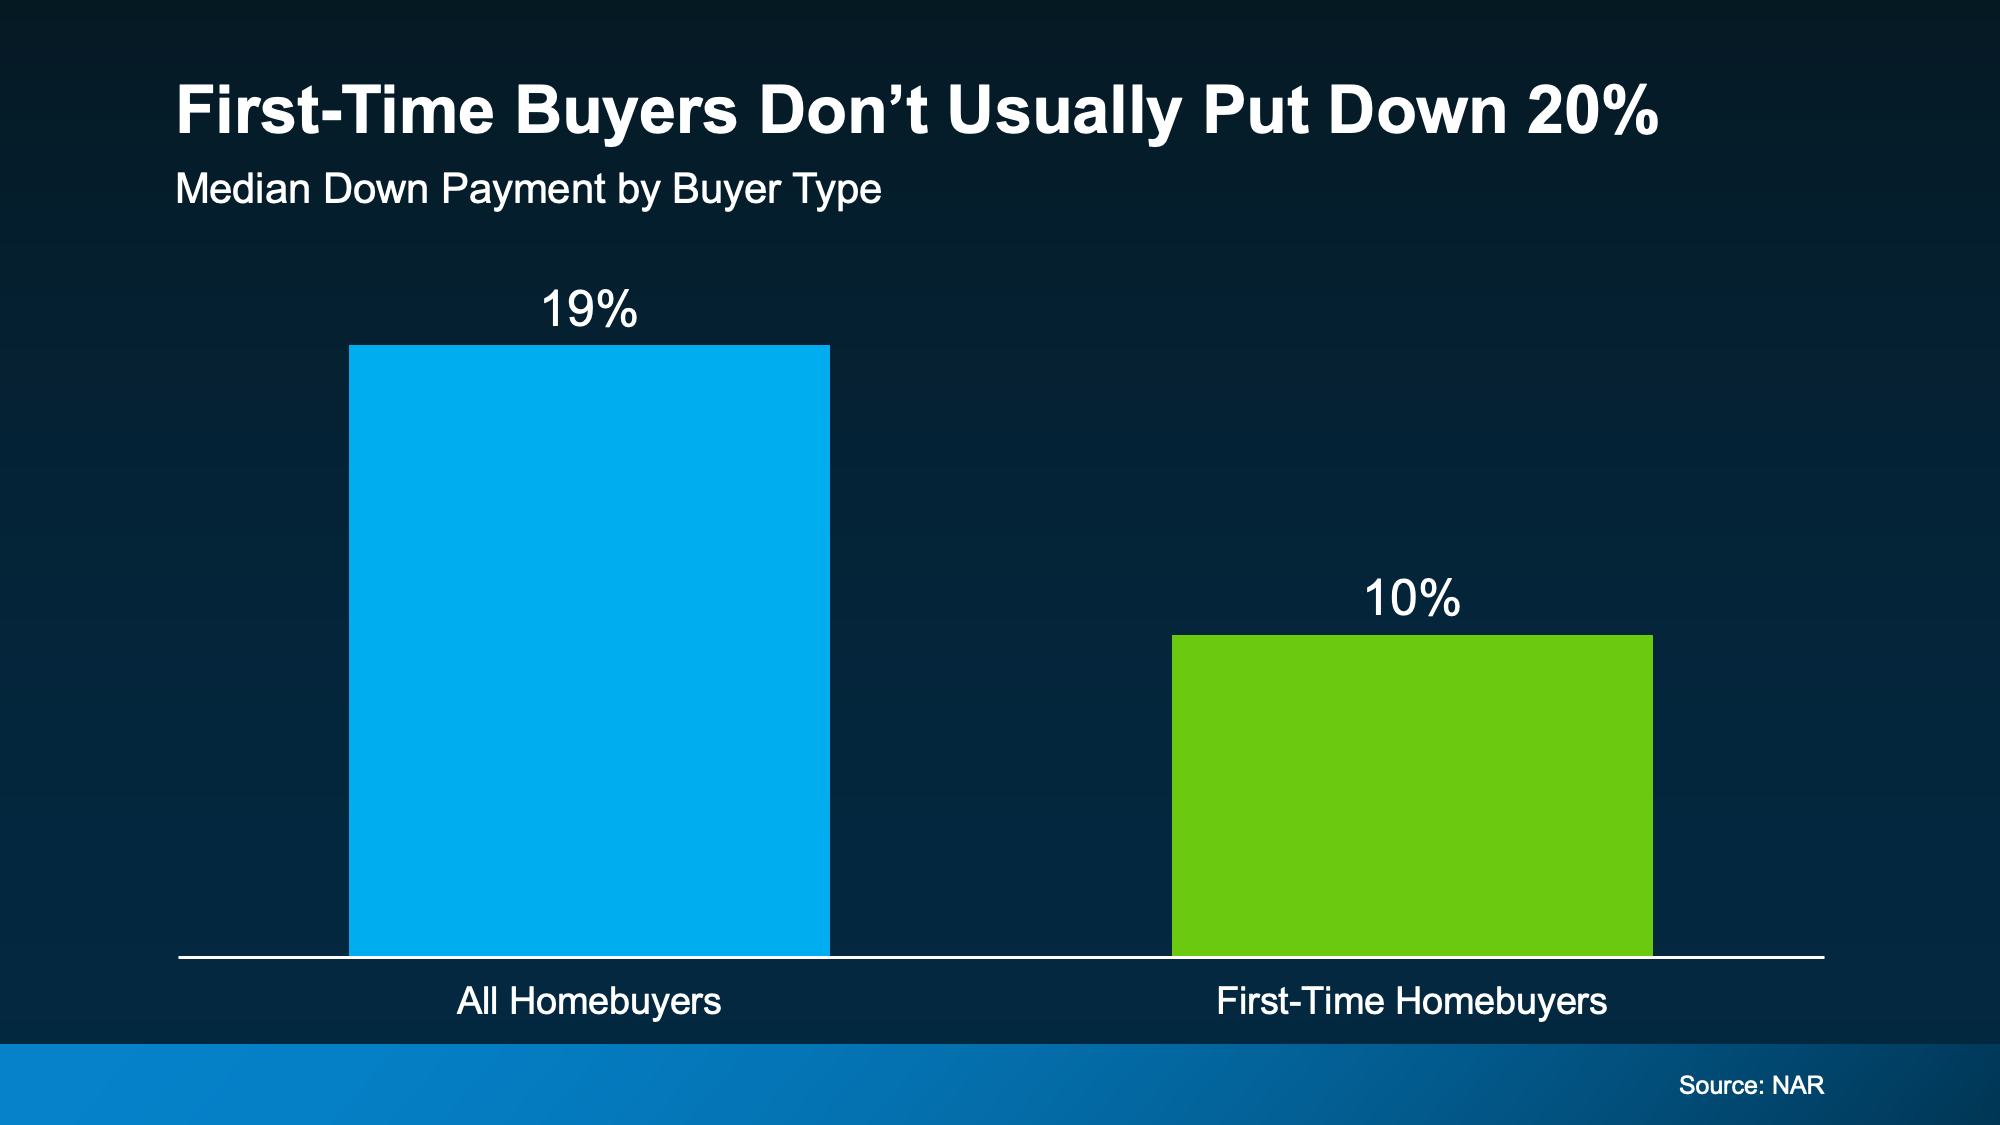
Most first-time buyers don't put down anywhere near that. The National Association of Realtors shows the median down payment for first-time buyers is 10% (see graph below):

a graph of a sales report

And the minimums go lower still. Some buyers put down as little as 3% on a conventional loan or 3.5% on an FHA loan, and eligible veterans or buyers in certain rural areas can put down nothing at all.

There's help with the upfront costs of buying, too. Down Payment Resource counts 2,746 assistance programs nationwide, and some are even stackable:

"Some homebuyers can layer multiple sources of assistance to reduce their upfront costs. Layering means combining more than one eligible source of funding as part of your home purchase."

Put those together – a lower price point, a smaller down payment, and help covering it – and the years you thought you needed start to come down.

[created_at] => 2026-09-23T18:00:43Z [description] =>

For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260923/Header-Image-20230404-Blog.png [id] => 112109 [kcm_ig_caption] => Your first home may not be as far off as it feels. When the numbers make sense for you, buying a starter home and putting down less than 20% can get you there years sooner. Want to see which starter homes in our area could fit your budget? Let's connect. [kcm_ig_hashtags] => FirstTimeHomebuyer,HomebuyingTips,KeepingCurrentMatters [modified] => [poll] => [public_bottom_line] =>

Your first home may not be as far off as it feels. When the numbers make sense for you, buying a starter home and putting down less than 20% can get you there years sooner. 

Want to see which starter homes in your area could fit your budget? A local real estate agent can show you.

[published_at] => 2026-10-05T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 112111 [content_type] => must-share [title] => 10/5 Must Share ) ) [shares] => 0 [slug] => two-moves-that-can-get-you-into-your-first-home-sooner [status] => published [tags] => Array ( ) [title] => Two Moves That Can Get You Into Your First Home Sooner [updated_at] => 2026-09-23T18:00:43Z [url] => /2026/10/05/two-moves-that-can-get-you-into-your-first-home-sooner/ )

Two Moves That Can Get You Into Your First Home Sooner

For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach.

3
stdClass Object
(
    [agents_bottom_line] => 

Whether you're bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Let's talk about what that means for your market and your plans.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:21:25Z [id] => 326 [name] => Equity [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:42Z [slug] => equity [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Equidad ) ) [updated_at] => 2024-04-10T16:21:42Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:04Z [id] => 327 [name] => Forecasts [parent] => [parent_id] => [published_at] => 2024-04-10T16:22:19Z [slug] => forecasts [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Previsiones ) ) [updated_at] => 2024-04-10T16:22:19Z ) ) [content_type] => blog [contents] =>

Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.

A recent survey from Clever found 58% of Gen Z buyers are actually rooting for a crash, just so homeownership feels within reach.

So, what do the forecasts actually say?

Every quarter, Fannie Mae surveys more than 100 housing experts on where prices are headed. The newest results are in. And spoiler alert: they’re not calling for a crash – not even the pessimists.

What the Newest Numbers Actually Say

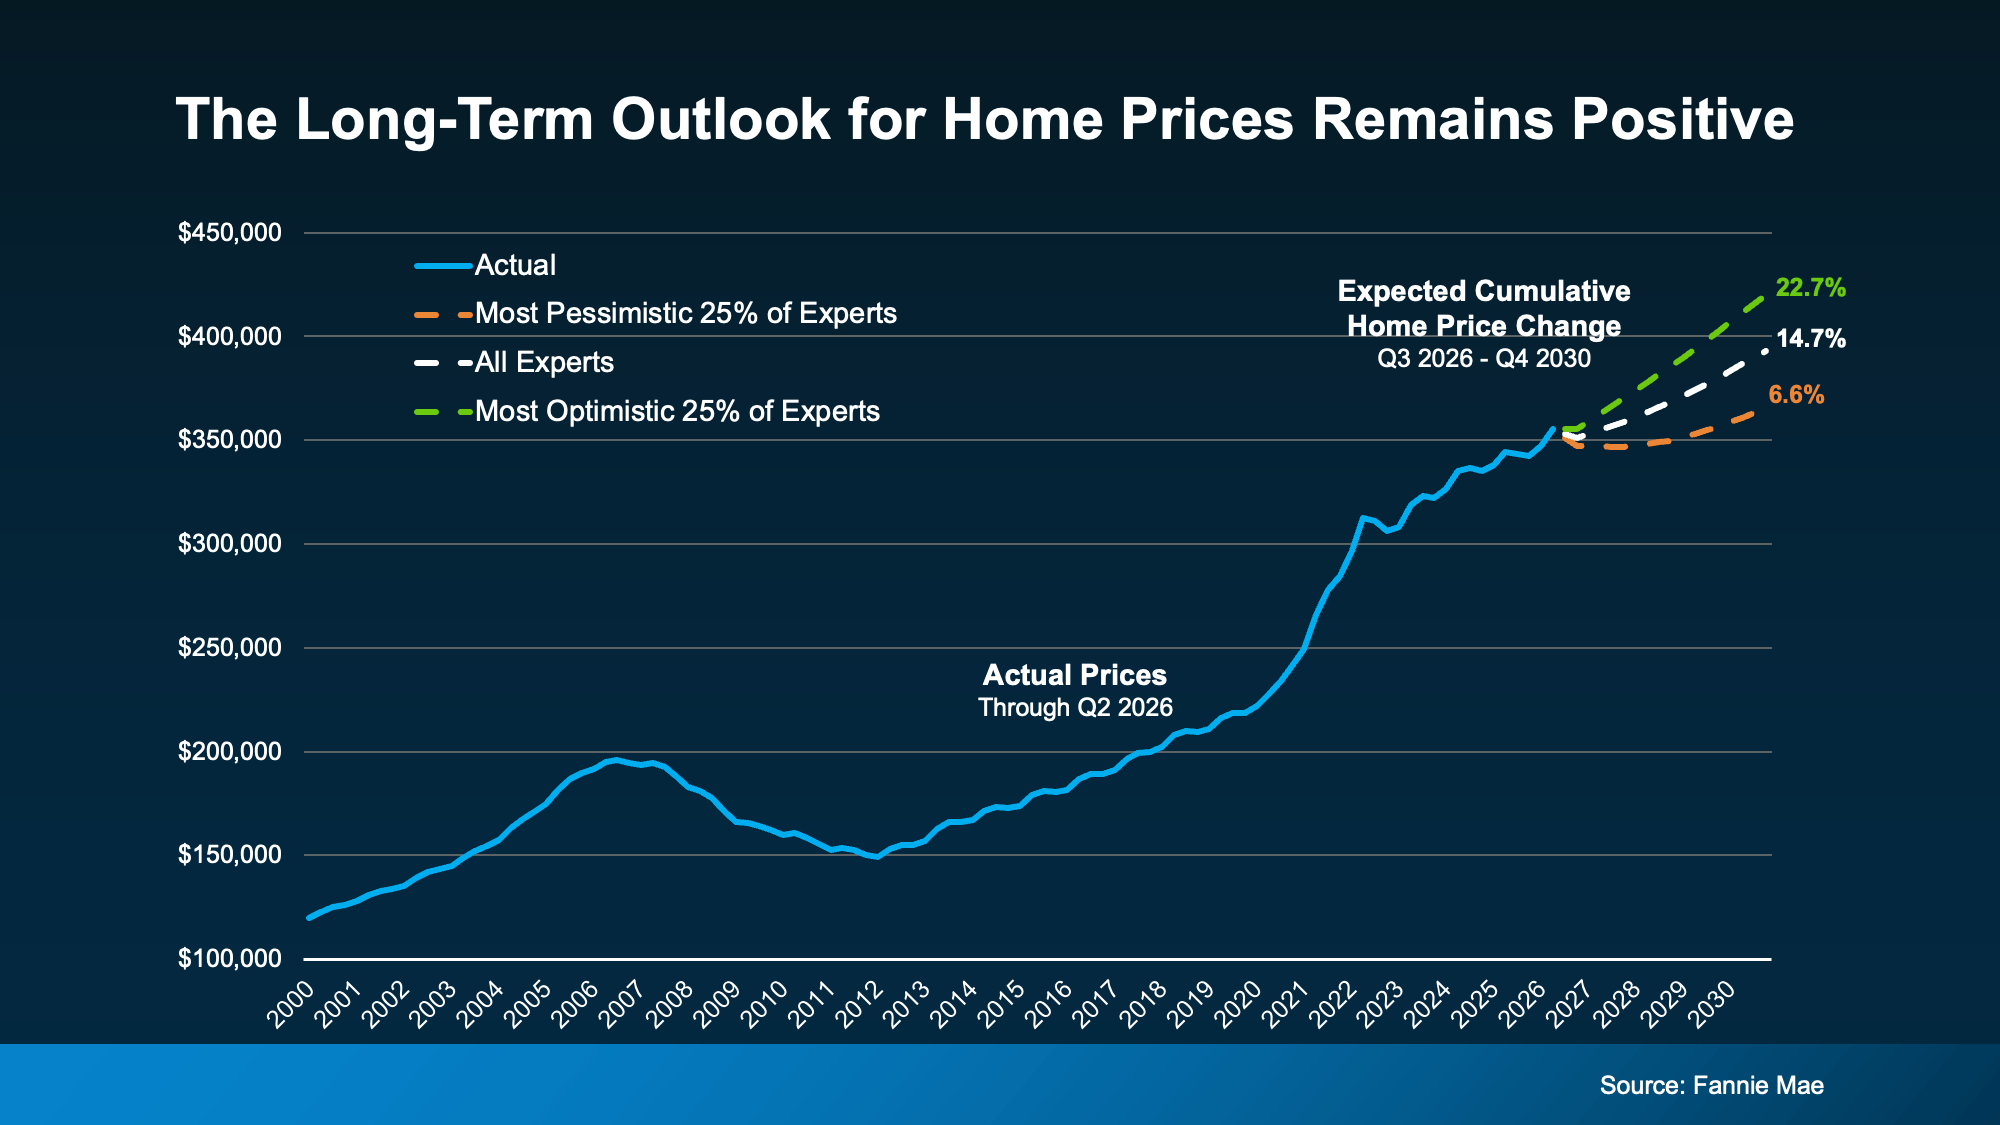
The panel's latest forecast has prices climbing every single year through at least 2030.

The panel's average forecast is that prices will rise by 14.7% in the next 5 years. And here’s where it gets really interesting. If you split these experts into optimists and pessimists, even the pessimists still expect prices to increase about 6.6% by the end of 2030 (see graph below):

a graph showing the price of a home

The takeaway? If you've been waiting for prices to fall, you may be waiting a while.

One thing to keep in mind though – these are national numbers. Prices in your area could run a little hotter or a little cooler than this, so it helps to know what’s happening locally, too. But the big picture is prices aren’t crashing. Historically prices usually rise.

How This Quarter Compares to the Past

Here’s something you probably don’t realize. This survey runs 4 times every year, so you can track the panel's mood over time.

A year ago, the panel expected home prices to grow 2.1% this year. Now they’re forecasting 2.5%. That means the near-term outlook actually got more optimistic. But that’s only part of the story. The years after that shifted, too (see graph below):

a graph of growth in a graph

Zoom out to 2027 through 2029 and the mood has cooled a bit. Each of those years is now expected to see a little less growth than the panel thought a year ago. That’s likely a reflection of where we are right now with everything that’s impacting the housing market.

But again, the overall takeaway here is every bar shows an increase in prices – the size of that increase has just moderated due to some of the factors at play.

A slower climb isn’t a bad thing, though. It’s a sign the market is settling into a more normal pace after a few wild years.

A little more growth here, a little less growth there. What hasn't budged once is the idea that home prices will keep growing.

What It Means for Your Next Move

Now, percentages are great, but you probably care more about the actual dollars and cents of your move, so let’s graph that out, too.

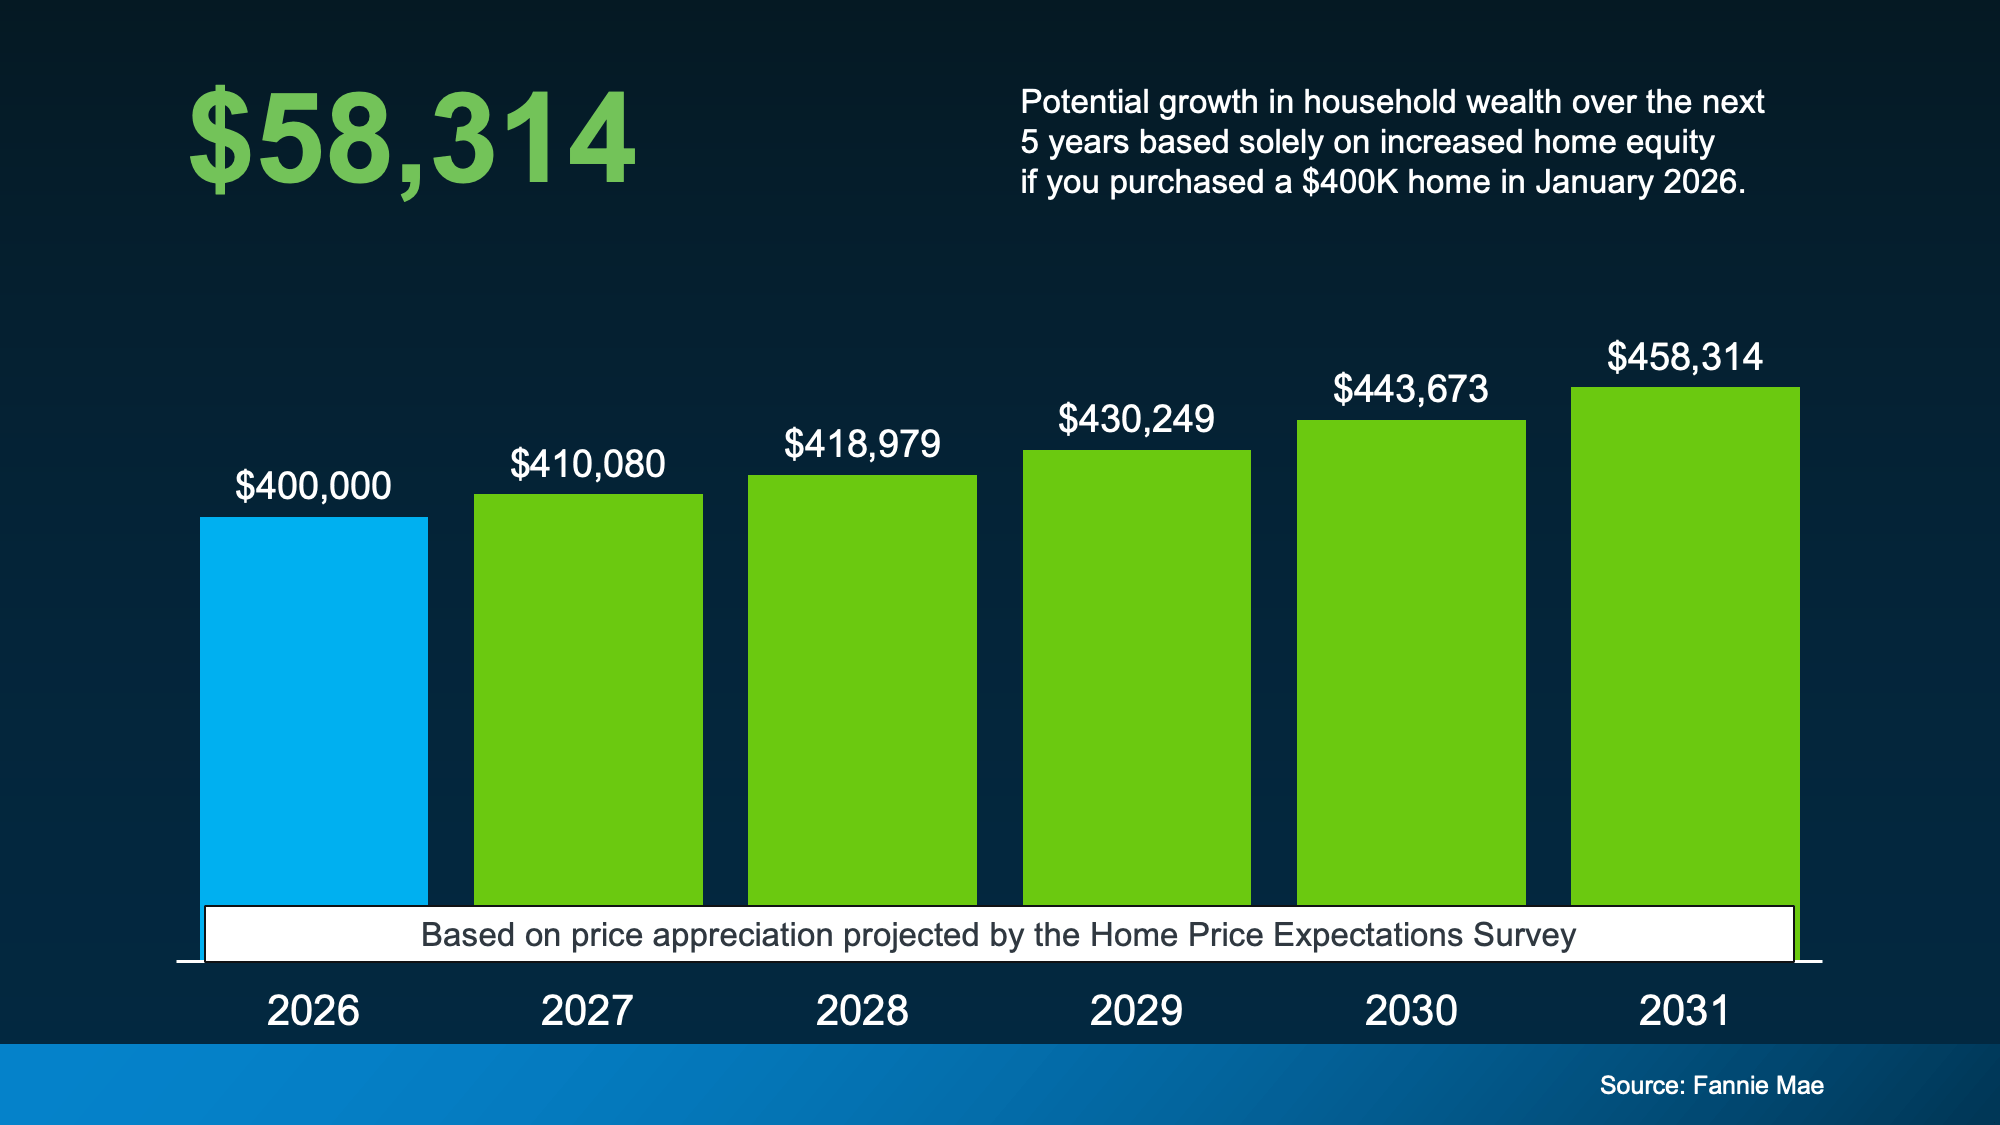
Run the numbers on a $400,000 home bought in January, and the panel's latest forecast puts you up about $58,000 in equity in 5 years just from price growth (see graph below):

a graph of growth in a number of green squares

That’s real wealth you could be building while others sit on the sidelines, waiting for a crash the experts don’t see coming. And with prices expected to keep rising, waiting could mean paying more for the same home later.

[created_at] => 2026-09-29T17:31:51Z [description] =>

Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260929/Header-Image-GettyImages-170652636.png [id] => 112310 [kcm_ig_caption] => Whether you're bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Let's talk about what that means for your market and your plans. [kcm_ig_hashtags] => HousingMarket,HomeBuyingTips,KeepingCurrentMatters [kcm_ig_quote] => Hoping for (or dreading) a housing crash? The experts just weighed in. [modified] => [poll] => [public_bottom_line] =>

Whether you're bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Talk with a local real estate agent about what that means for your market and your plans.

[published_at] => 2026-09-30T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 112311 [content_type] => must-share [title] => 9/30 Must Share ) ) [shares] => 0 [slug] => hoping-for-or-dreading-a-housing-crash-the-experts-just-weighed-in [status] => published [tags] => Array ( [0] => foundations ) [title] => Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In. [updated_at] => 2026-09-29T17:31:52Z [url] => /2026/09/30/hoping-for-or-dreading-a-housing-crash-the-experts-just-weighed-in/ )

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.

4
stdClass Object
(
    [agents_bottom_line] => 

Price cuts are a normal part of today’s housing market, and both buyers and sellers can use them to their advantage. Let's look at what's actually happening with prices in your neighborhood, so you know exactly where you stand before you list or make an offer.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:16:32Z [id] => 321 [name] => Agent Value [parent] => [parent_id] => [published_at] => 2024-04-10T16:17:42Z [slug] => agent-value [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Valor del agente ) ) [updated_at] => 2024-04-10T16:17:42Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) [6] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) [7] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2025-10-30T18:13:40Z [id] => 340 [name] => Price It Right/Overpricing [parent] => [parent_id] => [published_at] => 2025-10-30T18:13:40Z [slug] => price-it-rightoverpricing [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => ) ) [updated_at] => 2025-10-30T18:13:40Z ) ) [content_type] => blog [contents] =>

Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on.

Sellers tend to worry a cut means walking away with less than they hoped. Sometimes that’s true, but more often it just means the market moved faster than the listing did.

Buyers, for their part, often assume a cut means something’s wrong with the house. Most of the time, that’s not it.

This is what's actually driving all those price cuts, and why it matters no matter which side of the deal you're on.

42% of Homes for Sale Are Now Carrying a Price Cut

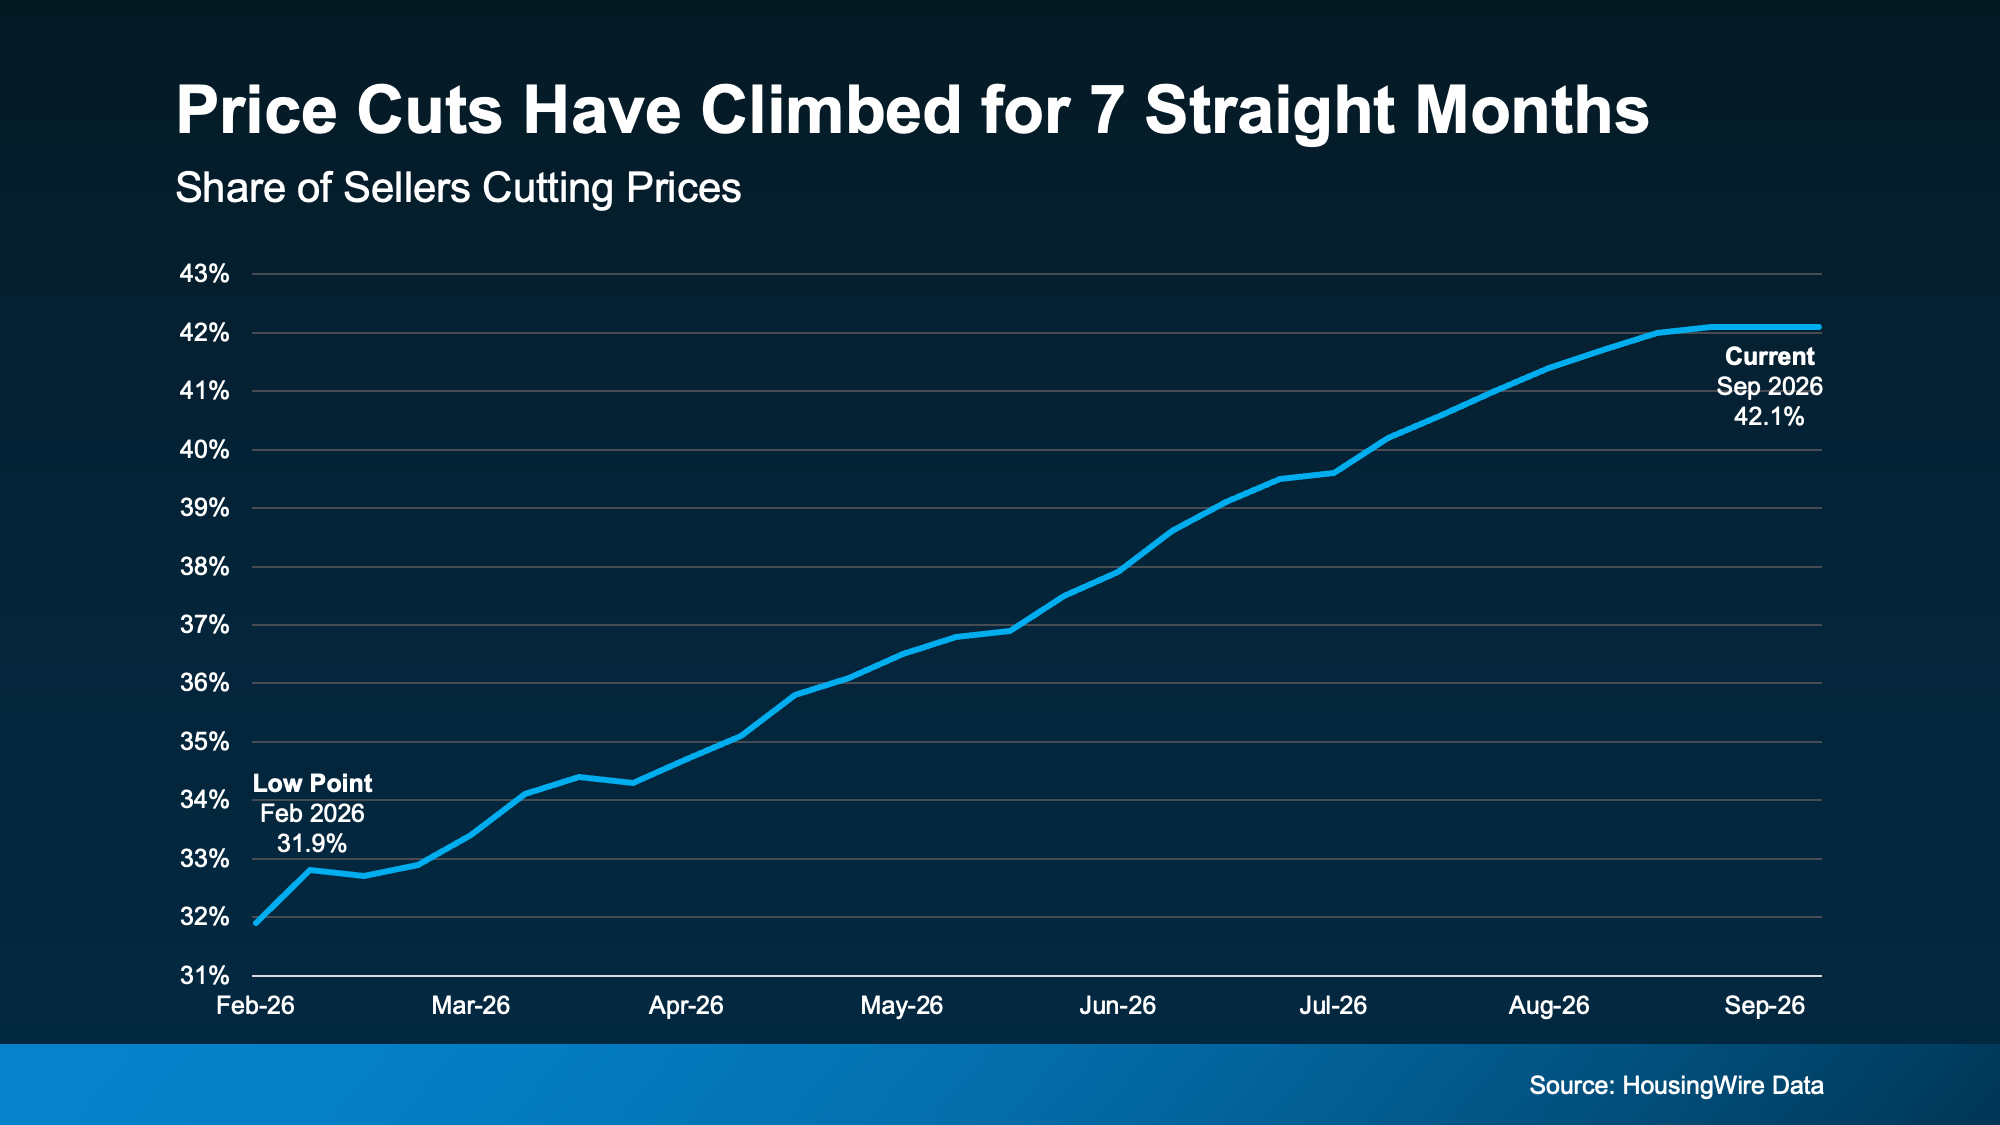
According to HousingWire Data, the share of sellers cutting their asking price has climbed every month for 7 straight months (see chart below):

a graph showing the growth of a straight month 

Today, more than 4 in 10 active listings have had at least 1 price cut, and the typical seller is cutting about $17,560 off their original number. 

Here’s why that’s happening. With rates still elevated and more homes to choose from, buyers can afford to wait for the right number. So, sellers who don’t start there often end up adjusting anyway.

What does that mean for you?

  • If you're selling, this isn’t a red flag. But it is a sign that pricing it right from day 1 is your best bet. Just know that the market's been shifting fast enough this year that sometimes even a well-priced house can fall behind within a matter of weeks. If that happens to you, dropping your price to catch up to where pricing actually stands today tends to bring in more buyers and helps you sell closer to true market value.

  • If you're buying, it's easy to assume a price cut means something's wrong with the house. But with cuts happening on more than 4 in 10 homes right now, the reality is sellers are just catching up to where the market already is. And with affordability still tight, that's exactly the kind of opening you need to get a better deal.

Why Sellers Are Adjusting Faster than Before

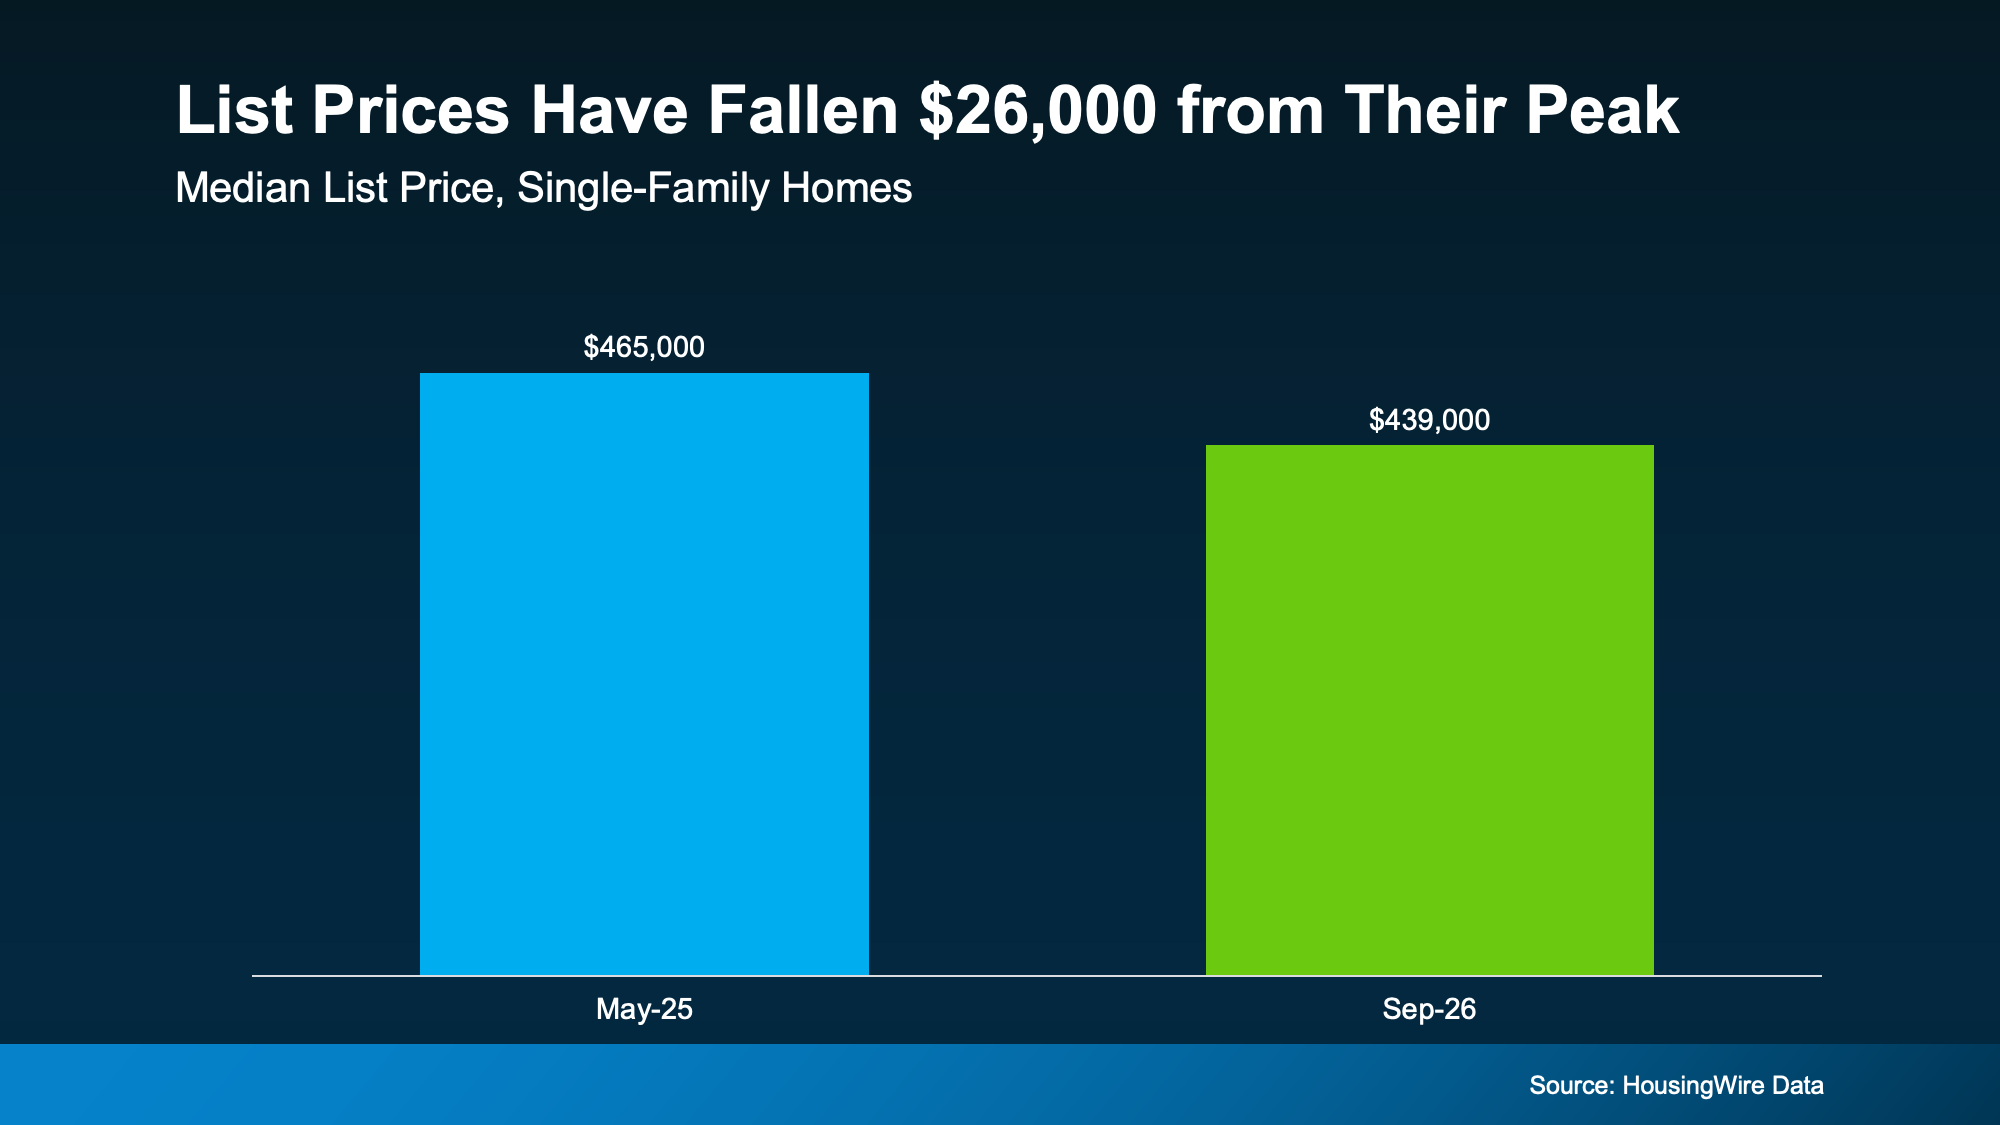
HousingWire Data also shows list prices are trending down nationally. That’s often a sign sellers are pricing more realistically from the start instead of listing high and getting stuck cutting later. List prices have fallen about $26,000 from last year's peak.

Some of that decline is seasonal, since list prices typically soften each winter before rebounding in the spring. So, expect asking prices to keep drifting a little lower before turning back around (see chart below):

a graph of a number of people 

Jake Krimmel, Senior Economist at Realtor.com, explains: 

“That is good news for buyers, who are seeing lower asking prices and more room to negotiate, but it is also good news for sellers: Pricing to today’s demand is helping homes move and keeping more transactions alive in a high-rate environment.”

Translation – with rates still elevated, buyers can only stretch so far. Sellers who meet them where they are instead of holding out for unrealistic prices are the ones actually getting to closing. And doing that up front is always better than chasing the market later.

Buyers, You’ve Got Room To Negotiate Again

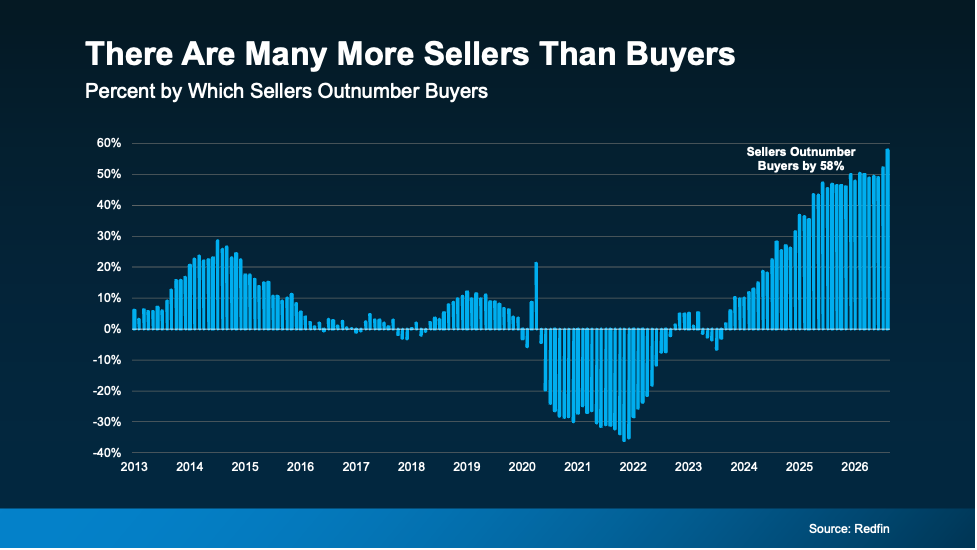
At the same time, Redfin data shows sellers now outnumber buyers by about 58%, the widest gap on record (see chart below):

a graph of sales 

That changes the power dynamics of the market – and impacts how homeowners should price their house. Nationally, about 7 in 10 markets now favor buyers or are trending that way.

  • For sellers, that means standing out matters as much as pricing. With more homes to choose from, buyers are comparing you directly against the competition. So, a little flexibility, like covering closing costs or being open on timing, can be what gets your house picked over another.

  • For buyers, it means more room to ask for a lower price, help with closing costs, repairs after inspection, or some combination of all 3. That’s especially true for homes that have already sat for weeks, where sellers are often the most willing to talk.

[created_at] => 2026-09-22T21:40:32Z [description] =>

Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260922/Header-Image-GettyImages-1778738751.png [id] => 112076 [kcm_ig_caption] => Price cuts are a normal part of today’s housing market, and both buyers and sellers can use them to their advantage. Let's look at what's actually happening with prices in your neighborhood, so you know exactly where you stand before you list or make an offer. [kcm_ig_hashtags] => HousingMarket,PriceReduced,KeepingCurrentMatters [kcm_ig_quote] => Here's why so many sellers are cutting their price right now. [modified] => [poll] => [public_bottom_line] =>

Price cuts are a normal part of today’s housing market, and both buyers and sellers can use them to their advantage. Connect with a local real estate agent to look at what's actually happening with prices in your neighborhood, so you know exactly where you stand before you list or make an offer.

[published_at] => 2026-09-24T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 112081 [content_type] => must-share [title] => 9/24 Must Share ) ) [shares] => 0 [slug] => why-so-many-sellers-are-cutting-their-price-right-now [status] => published [tags] => Array ( ) [title] => Why So Many Sellers Are Cutting Their Price Right Now [updated_at] => 2026-09-22T21:40:32Z [url] => /2026/09/24/why-so-many-sellers-are-cutting-their-price-right-now/ )

Why So Many Sellers Are Cutting Their Price Right Now

Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on.

5
stdClass Object
(
    [agents_bottom_line] => 

Selling this fall is absolutely doable. And now you know four of the biggest things to get right.

If you want to sell before the end of the year, let’s make sure you have a winning strategy from day one.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2025-10-30T18:13:40Z [id] => 340 [name] => Price It Right/Overpricing [parent] => [parent_id] => [published_at] => 2025-10-30T18:13:40Z [slug] => price-it-rightoverpricing [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => ) ) [updated_at] => 2025-10-30T18:13:40Z ) ) [content_type] => blog [contents] =>

Selling your house this fall is absolutely doable. But there’s something you need to know about this time of year. 

Buyer activity typically starts to slow while the number of homes for sale climb – and you need the right strategy to get attention in this type of market.

The good news? There’s a lot you can control.

From how you price and present your house to how you negotiate and respond to feedback. Here are four things you’ll want to get right this fall. 

#1: Price To Get Buyers’ Attention

In the fall, there are typically fewer buyers looking and more homes for them to choose from. So, you want to make the most of every buyer who comes across your house.

And your price is one of the first things that can make them stop and take a closer look – or keep scrolling. 

That’s why this isn’t the time to start high “just to see what happens.”

If buyers think your house is overpriced, they have plenty of other options to move on to. And that could leave you sitting and waiting.

So, if you want to sell before year-end, work with your agent to find the right price for your house and today’s market. That may mean listing at market value – or even slightly below it – to grab buyers’ attention.

Redfin explains how a seemingly small difference can change your buyer pool: 

“Buyers often search in round-number price brackets, so pricing at $499,000 instead of $505,000 can make your home appear in more searches and feel like a better deal.” 

#2: Make a Great First Impression

When buyers had very few homes to choose from, they were often more willing to overlook dated finishes or a house that needed some work. That’s harder to count on now.

With more choices, how your house looks online and in person can determine whether it makes a buyer’s shortlist at all.

That doesn’t mean you need a full renovation before you sell, but you should take care of essential repairs, do what you can to boost curb appeal, and make sure your house photographs well. Maybe that’s some light staging, maybe it’s swapping out faucets or lights, or maybe a fresh coat of paint. Small details can help a lot.

After all, you only get one chance to make that first impression. Make it count.

#3: Stay Open To Negotiating

Some sellers are still expecting the kind of leverage they had a few years ago. But in many markets, buyers have more negotiating power today and there’s a lot more give and take.

The latest data from Redfin shows 46.2% of sellers gave buyers some type of concession. So, consider throwing in a little help with closing costs or covering a repair. Almost half of sellers are.

The takeaway? Playing hard ball may not get you what you want. But being flexible might. The key is not getting so focused on “winning” every individual negotiation that you lose sight of the bigger goal: making your move happen.

Sometimes a small concession is what gets you to the closing table.

#4: Know When It’s Time To Adjust

Sometimes your house tells you when something isn’t working. Maybe you’re getting plenty of online views but very few showings. Or buyers are coming through, but you’re not getting offers. Or maybe buyer feedback has one recurring theme.

Pay attention to those signals. They can help you figure out what needs to change.

Let’s say your price is the most common point of feedback. Talk to your agent about a price drop. It doesn’t have to be a big change to make a big difference. The average price cut right now is 4% according to HousingWire Data. That’s normal.

Now, that doesn’t mean you should panic and slash your price after a week. It means you and your agent should pay attention to what buyers are telling you and adjust if you need to.

Sometimes the smartest move isn’t waiting for the right buyer. It’s making sure you’re giving that buyer a reason to act.

[created_at] => 2026-09-15T18:17:33Z [description] =>

Selling your house this fall is absolutely doable. But there’s something you need to know about this time of year.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260915/Header-Image-Summer-2023-Guide-33--original.png [id] => 111814 [kcm_ig_caption] => Selling this fall is absolutely doable. And now you know four of the biggest things to get right. If you want to sell before the end of the year, let’s make sure you have a winning strategy from day one. [kcm_ig_hashtags] => HomeSellingTips,SellingDuringFall,KeepingCurrentMatters [kcm_ig_quote] => Selling this fall? You want to get these 4 things right. [modified] => [poll] => [public_bottom_line] =>

Selling this fall is absolutely doable. And now you know four of the biggest things to get right.

If you want to sell before the end of the year, connect with a local agent to make sure you have the right strategy from day one.

[published_at] => 2026-09-17T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 111815 [content_type] => must-share [title] => 9/17 Must Share ) ) [shares] => 0 [slug] => selling-this-fall-you-want-to-get-these-4-things-right [status] => published [tags] => Array ( ) [title] => Selling This Fall? You Want To Get These 4 Things Right. [updated_at] => 2026-09-15T18:17:33Z [url] => /2026/09/17/selling-this-fall-you-want-to-get-these-4-things-right/ )

Selling This Fall? You Want To Get These 4 Things Right.

Selling your house this fall is absolutely doable. But there’s something you need to know about this time of year.

6
stdClass Object
(
    [agents_bottom_line] => 

If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer.

Want help figuring out when those advantages typically show up in our market?

Let's have a quick conversation about how our market works and the steps you’ll need to take to get ready. 

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.

Yes, mortgage rates have been ticking up lately – and that’s creating some real challenges with affordability. No one’s arguing that. But there are also predictable trends that happen this time every year that can put some wind back in your sails.

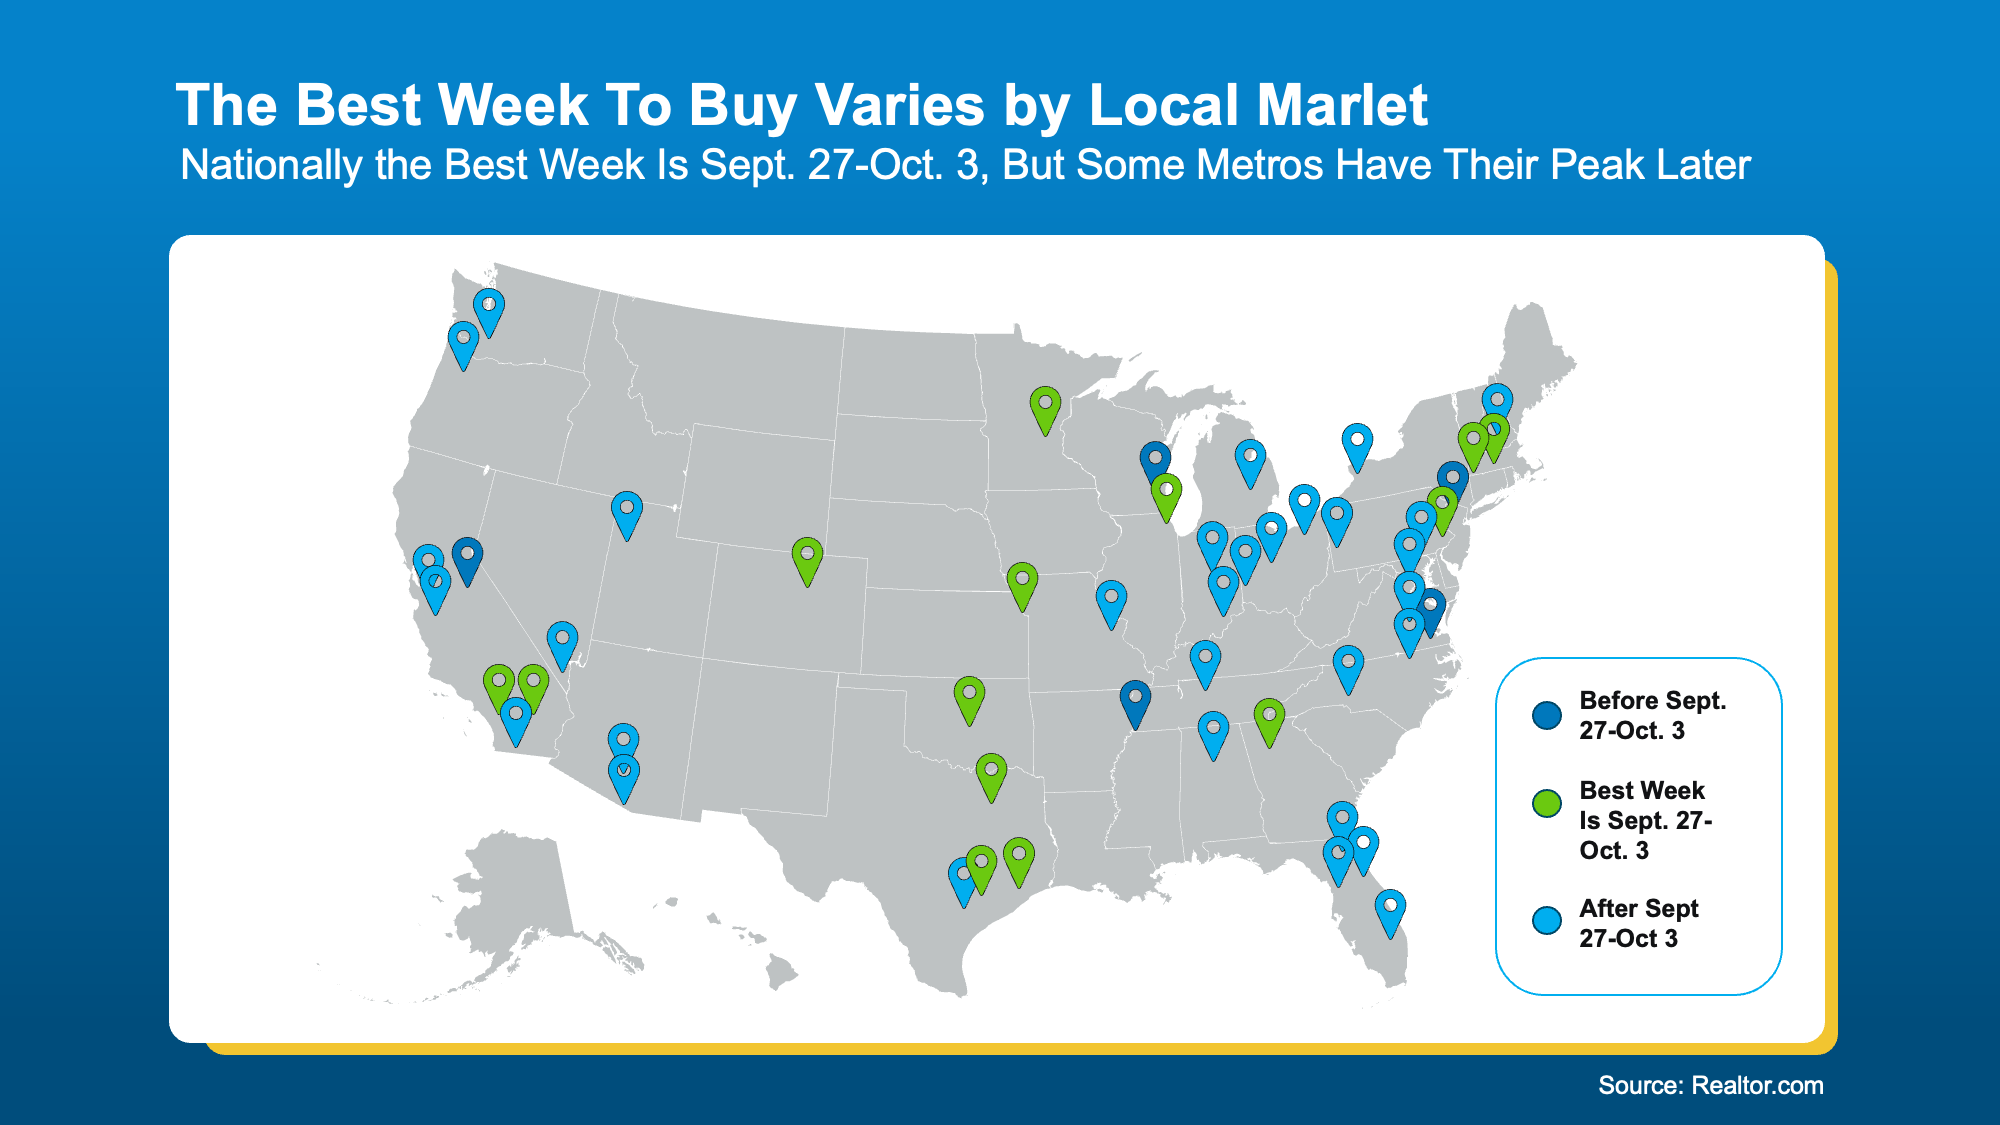
According to research coming out of Realtor.com, nationally, the week of September 27 – October 3 will be the best time to buy this year for this very reason:

“The week of September 27–October 3 brings together the market conditions buyers value most—elevated inventory, less competition and prices that have eased from their seasonal high—giving prepared buyers a way to offset high rates with savings on price and room to negotiate with confidence."

But that’s the national best week. Depending on where you live, your local sweet spot may come a little earlier or later (see map below):

a map of the united states with pins

It all depends on local trends and how inventory and buyer demand ebbs and flows seasonally where you want to live. But no matter when your market hits its peak, here are some of the perks you can expect this time of year.

More Choices, Better Prices, and Less Competition

For starters, there are more homes to choose from. In fact, data from the National Association of Realtors (NAR) shows the number of homes for sale recently reached its highest level in more than 10 years:

“NAR’s data does show a strong uptick in for-sale inventory at the end of the summer, reaching the highest level in more than 10 years.”

That means you may have a better shot at finding something you love and can afford without making as many compromises. And that’s not the only advantage.

Realtor.com says buyers during this window could see home prices about $14,000 lower than the summer peak, along with 30% less competition from other buyers. Plus, homes tend to stay on the market almost 2 weeks longer (13 days), giving you a little more breathing room to make a decision. 

  • More choices.

  • Better pricing.

  • Less competition.

That combination could be enough to ease some of the pressure higher mortgage rates are putting on your budget.

The Window Doesn’t Close After This One Week

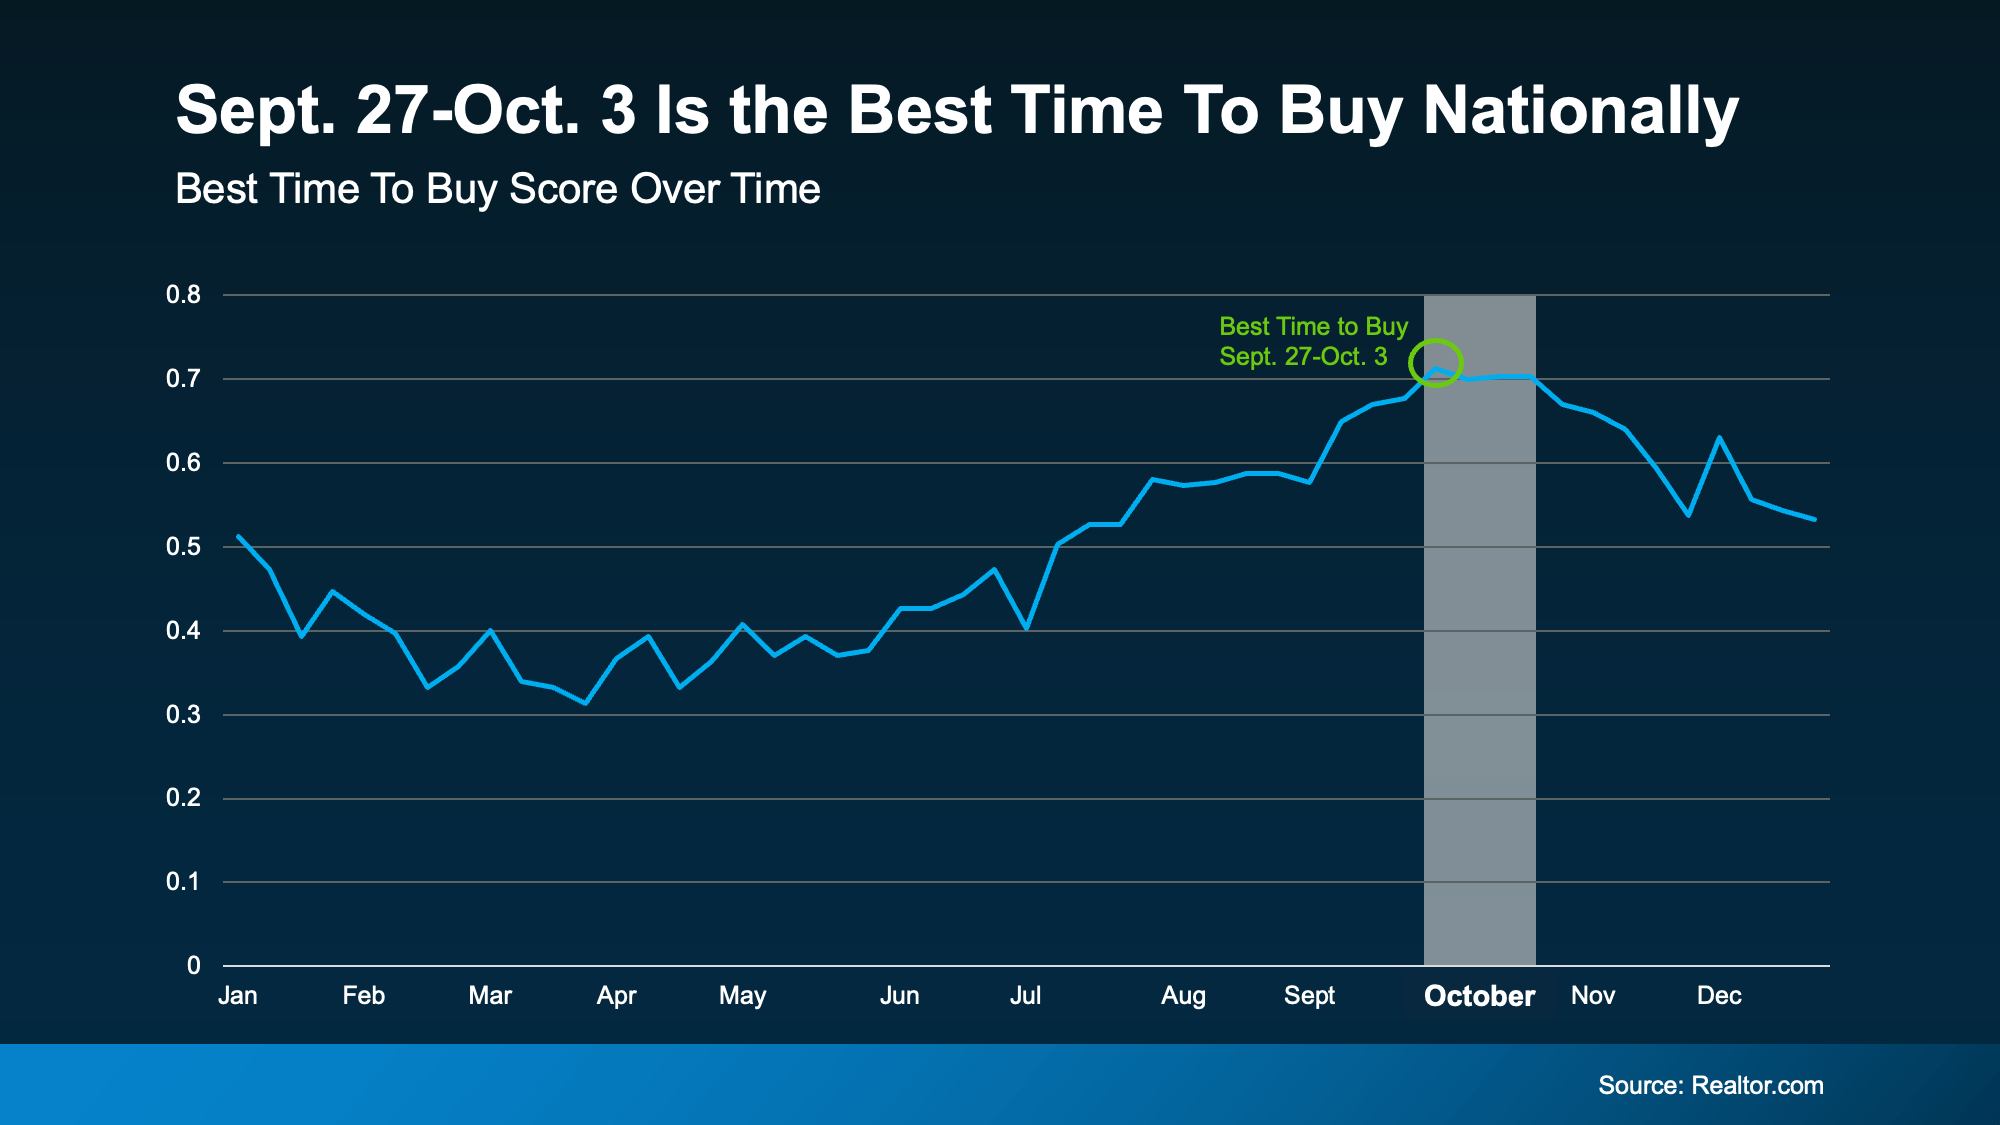
But you certainly don’t have to buy during that very specific window. This isn’t a one-week-only opportunity. History tells us conditions should be tipped in your favor for the entire month of October:

a graph on a dark background

In fact, Realtor.com says 42 of the 50 largest metros see their best week to buy fall sometime during October. So, don’t feel like you have to rush to hit one specific date. Use the time now to get things lined up, then jump in when the timing is right for you. As Guaranteed Rate explains: 

“The best time to buy a home depends on your needs. Certain seasons can give you an advantage when starting your homebuying journey.”

[created_at] => 2026-09-15T17:52:22Z [description] =>

Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260915/Header-Image-20230327-Blog-original.png [id] => 111810 [kcm_ig_caption] => If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer. Want help figuring out when those advantages typically show up in our market? Let's have a quick conversation about how our market works and the steps you’ll need to take to get ready. [kcm_ig_hashtags] => BestTimeToBuyAHome,HomebuyingTips,KeepingCurrentMatters [kcm_ig_quote] => The best time to buy a home in 2026 is almost here. [modified] => [poll] => [public_bottom_line] =>

If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer.

Want help figuring out when those advantages typically show up in your market?

Have a quick conversation with a lender and a local agent about how your market works and the steps you’ll need to take to get ready. 

[published_at] => 2026-09-16T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 111812 [content_type] => must-share [title] => 9/16 Must Share ) ) [shares] => 0 [slug] => the-best-time-to-buy-a-home-in-2026-is-almost-here [status] => published [tags] => Array ( [0] => foundations ) [title] => The Best Time To Buy a Home in 2026 Is Almost Here [updated_at] => 2026-09-15T17:52:22Z [url] => /2026/09/16/the-best-time-to-buy-a-home-in-2026-is-almost-here/ )

The Best Time To Buy a Home in 2026 Is Almost Here

Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.

7
stdClass Object
(
    [agents_bottom_line] => 

Of course, every market moves a little differently. But here's what doesn't change: Fall consistently gives buyers. More homes. Lower asking prices. Motivated sellers. 

If you’ve been waiting for your search to feel a little more doable, this season may be worth another look.

Let’s have a quick conversation about what's happening in our market and see whether this fall gives you opportunities you may not have had a few months ago.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:06:50Z [id] => 320 [name] => Inventory [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:06Z [slug] => inventory [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Inventario ) ) [updated_at] => 2024-04-10T16:19:06Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) ) [content_type] => blog [contents] =>

You've been waiting for something to change before you buy. It just might not be the thing you expected…

While everyone’s paying attention to mortgage rates, only the savviest buyers know that the changing season can start tipping things in their favor. 

Because every fall, buyers tend to get more to choose from, better prices, and more room to negotiate. And that’s why Hannah Jones, Senior Economist at Realtor.com, says:

“We always see that the best time to buy window usually falls in the early fall around October.”

And that’s exactly why, if you've been waiting for a better moment to buy, this season may be worth a closer look – even with rates where they are.

1. There Are More Homes To Choose From

One of the biggest frustrations buyers have had over the past few years has been a lack of choices. Fall tends to help with that.

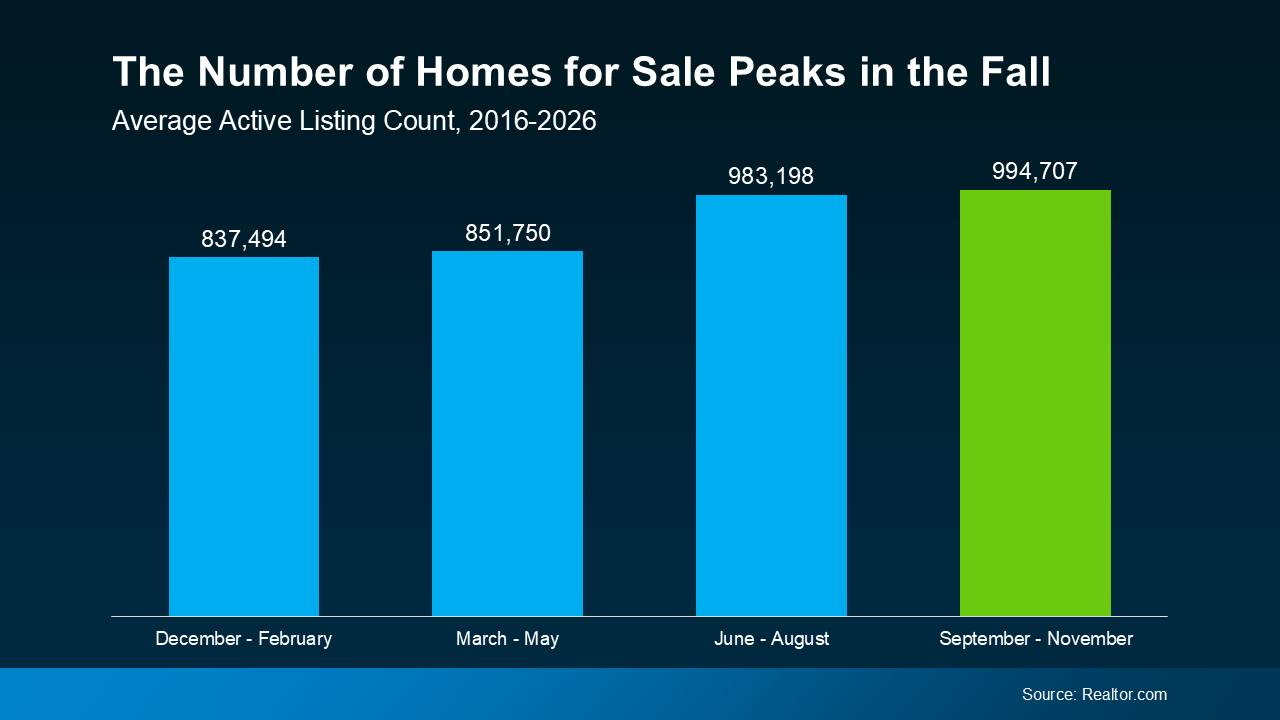
Based on seasonal trends, Realtor.com data shows there are typically more homes available for sale in September through November than during any other season of the year (see graph below):

a graph of a number of homesWhy does this happen? Homes that hit the market in spring and summer don't all close right away. Some sit. New listings keep coming. And inventory builds as the year goes on.
By fall, you're looking at the largest pool of available homes all year. That makes it easier to find one that works for your needs and your budget. And if anything, this should be more true this year. Rates that are higher for longer tend to help inventory grow even more.

More choices can mean fewer compromises. You’re more likely to find the right home, not just the one that happens to be available.

2. Asking Prices Start To Drop

Having more choices is great. But if every home is still priced too high, that only gets you so far. That's where fall's second advantage kicks in: asking prices start their seasonal decline. 

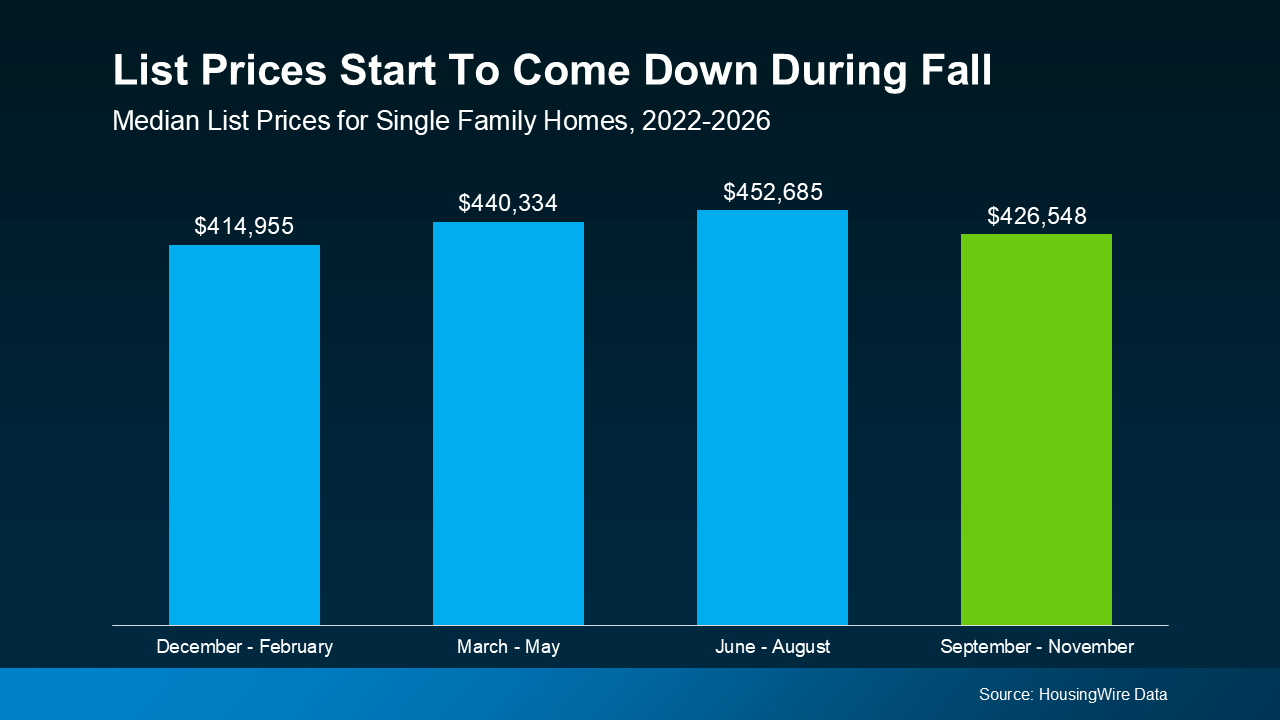
HousingWire data shows this trend over time (see graph below):

a graph of a number of blue and green barsIt works like this. Spring and early summer are when sellers feel the most confident because that's when demand is typically strongest. So, many homeowners price their homes higher during those periods because of the uptick in demand.
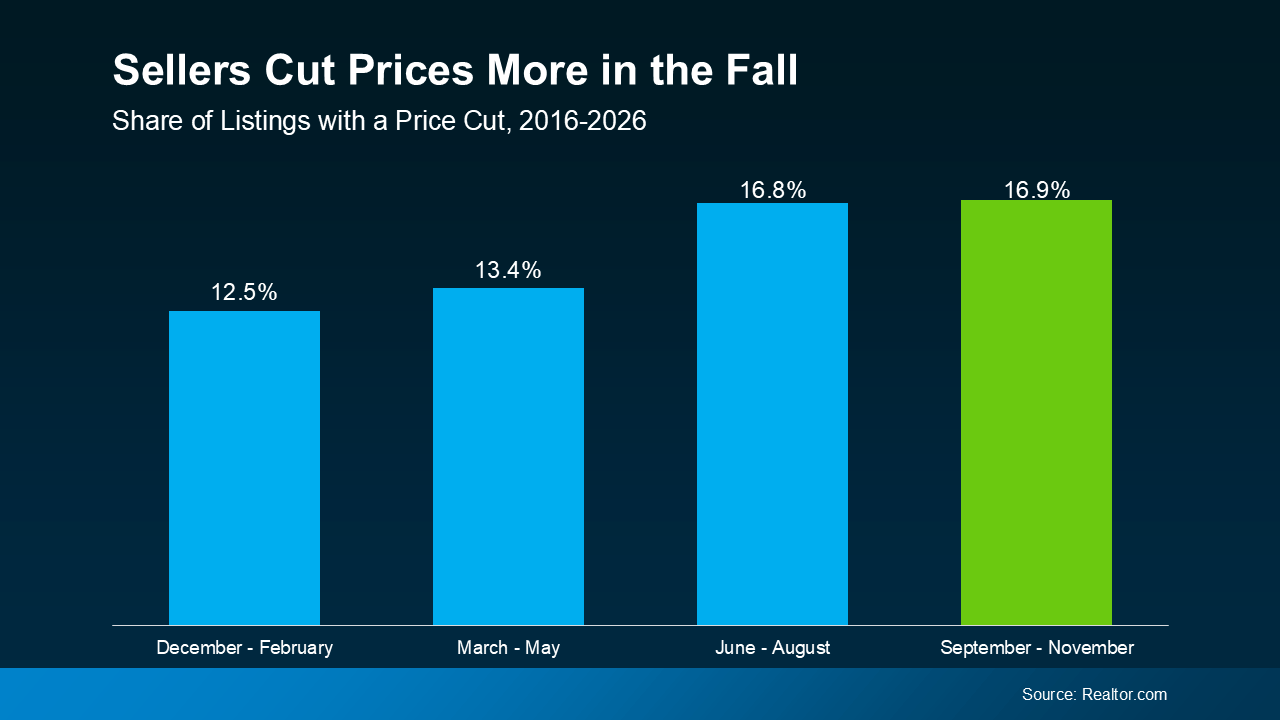
But every year, like clockwork, that dynamic starts to change by fall. Buyer activity slows down as the weather cools off. So, sellers have to price a bit lower to try to draw buyers in. And that’s good for your bottom line.

3. More Sellers Are Willing To Negotiate

But fall doesn't just bring more choices and lower asking prices. It also brings more sellers who are increasingly motivated to get a deal done. 

You can see it in the data. Most years, fall is when price cuts peak according to Realtor.com data (see graph below):

a graph of sales with numbers and text

While it’s not a big difference from summer, this fall you’ll have more negotiation power than you’d have if you wait until the first half of 2027. Here’s why. 

If a home is on the market in the fall, many sellers are eager to get it sold before the holidays. And since there are usually fewer buyers active in the fall, that often leads to another opportunity to snag a better deal. As the National Association of Realtors (NAR) explains:

“Less competition can lead to better deals. While homes are not selling as fast as during the summer, sellers may be more willing to negotiate.”

Even a small seller compromise here can make a meaningful difference for you. 

As an example, a 5% price drop on a $500,000 home is $25,000. That could mean you end up borrowing less, keeping more money in savings, having room in the budget for updates after you move in, or simply making the monthly payment feel more manageable.

[created_at] => 2026-08-28T16:24:21Z [description] =>

You've been waiting for something to change before you buy. It just might not be the thing you expected…

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260828/20260903---Blog-Header-Image-1--original.png [id] => 111198 [kcm_ig_caption] => Of course, every market moves a little differently. But here's what doesn't change: Fall consistently gives buyers. More homes. Lower asking prices. Motivated sellers. If you’ve been waiting for your search to feel a little more doable, this season may be worth another look. Let’s have a quick conversation about what's happening in our market and see whether this fall gives you opportunities you may not have had a few months ago. [kcm_ig_hashtags] => Homebuying,HousingMarketUpdate,KeepingCurrentMatters [kcm_ig_quote] => Why buyers shouldn't overlook a fall move. [modified] => [poll] => [public_bottom_line] =>

Of course, every market moves a little differently. But here's what doesn't change: Fall consistently buyers. More homes. Lower asking prices. Motivated sellers. 

If you’ve been waiting for your search to feel a little more doable, this season may be worth another look.

Have a quick conversation with a local agent about what's happening in your market. That way you can find out whether this fall gives you opportunities you may not have had a few months ago.

[published_at] => 2026-09-03T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 111201 [content_type] => must-share [title] => 9/3 Must Share ) ) [shares] => 0 [slug] => why-buyers-shouldnt-overlook-a-fall-move [status] => published [tags] => Array ( ) [title] => Why Buyers Shouldn't Overlook a Fall Move [updated_at] => 2026-08-28T16:24:21Z [url] => /2026/09/03/why-buyers-shouldnt-overlook-a-fall-move/ )

Why Buyers Shouldn't Overlook a Fall Move

You've been waiting for something to change before you buy. It just might not be the thing you expected…

8
stdClass Object
(
    [agents_bottom_line] => 

Life changes. Priorities shift. Families grow. Kids move out. Careers evolve. And eventually, the house you’re in may stop fitting the life you’re living.

If that’s been weighing on you lately, let’s talk through what your options could realistically look like today, no matter where rates or prices are.

Life can’t always wait for perfect market conditions. Maybe you don’t have to either.

[assets] => Array ( ) [can_share] => no [categories] => Array ( ) [content_type] => blog [contents] =>

You may be telling yourself you’re going to wait to move – maybe you’re hoping mortgage rates will come down, prices will fall, or the market will feel a little easier.

And honestly? A lot of people feel that way right now. But here’s what some are starting to realize.

Waiting doesn’t usually fix the thing that made you want to move in the first place.

Your family still desperately needs more room.
Your empty nest still feels too...empty.

Your parents or grandparents still need you to live closer.

You just got married... or divorced.

Your vision of retirement has you living somewhere else.

Eventually, life can reach a point where waiting feels harder than moving.

That’s why some people are still deciding to buy right now, even in today’s market. Not because conditions are perfect. But because the life changes behind their move never really went away.

And maybe that’s exactly where you are too. If so, you’re certainly not alone.

The Real Reasons People Move

Data from the National Association of Realtors (NAR) shows 1 in 5 buyers in 2025 said they felt like they had to purchase a home at that time, no matter the market.

That's an important reminder right now. Sure, the dollars and cents of your move have to make sense for you. But big life changes happen whether mortgage rates and home prices are high, low, or somewhere in between.

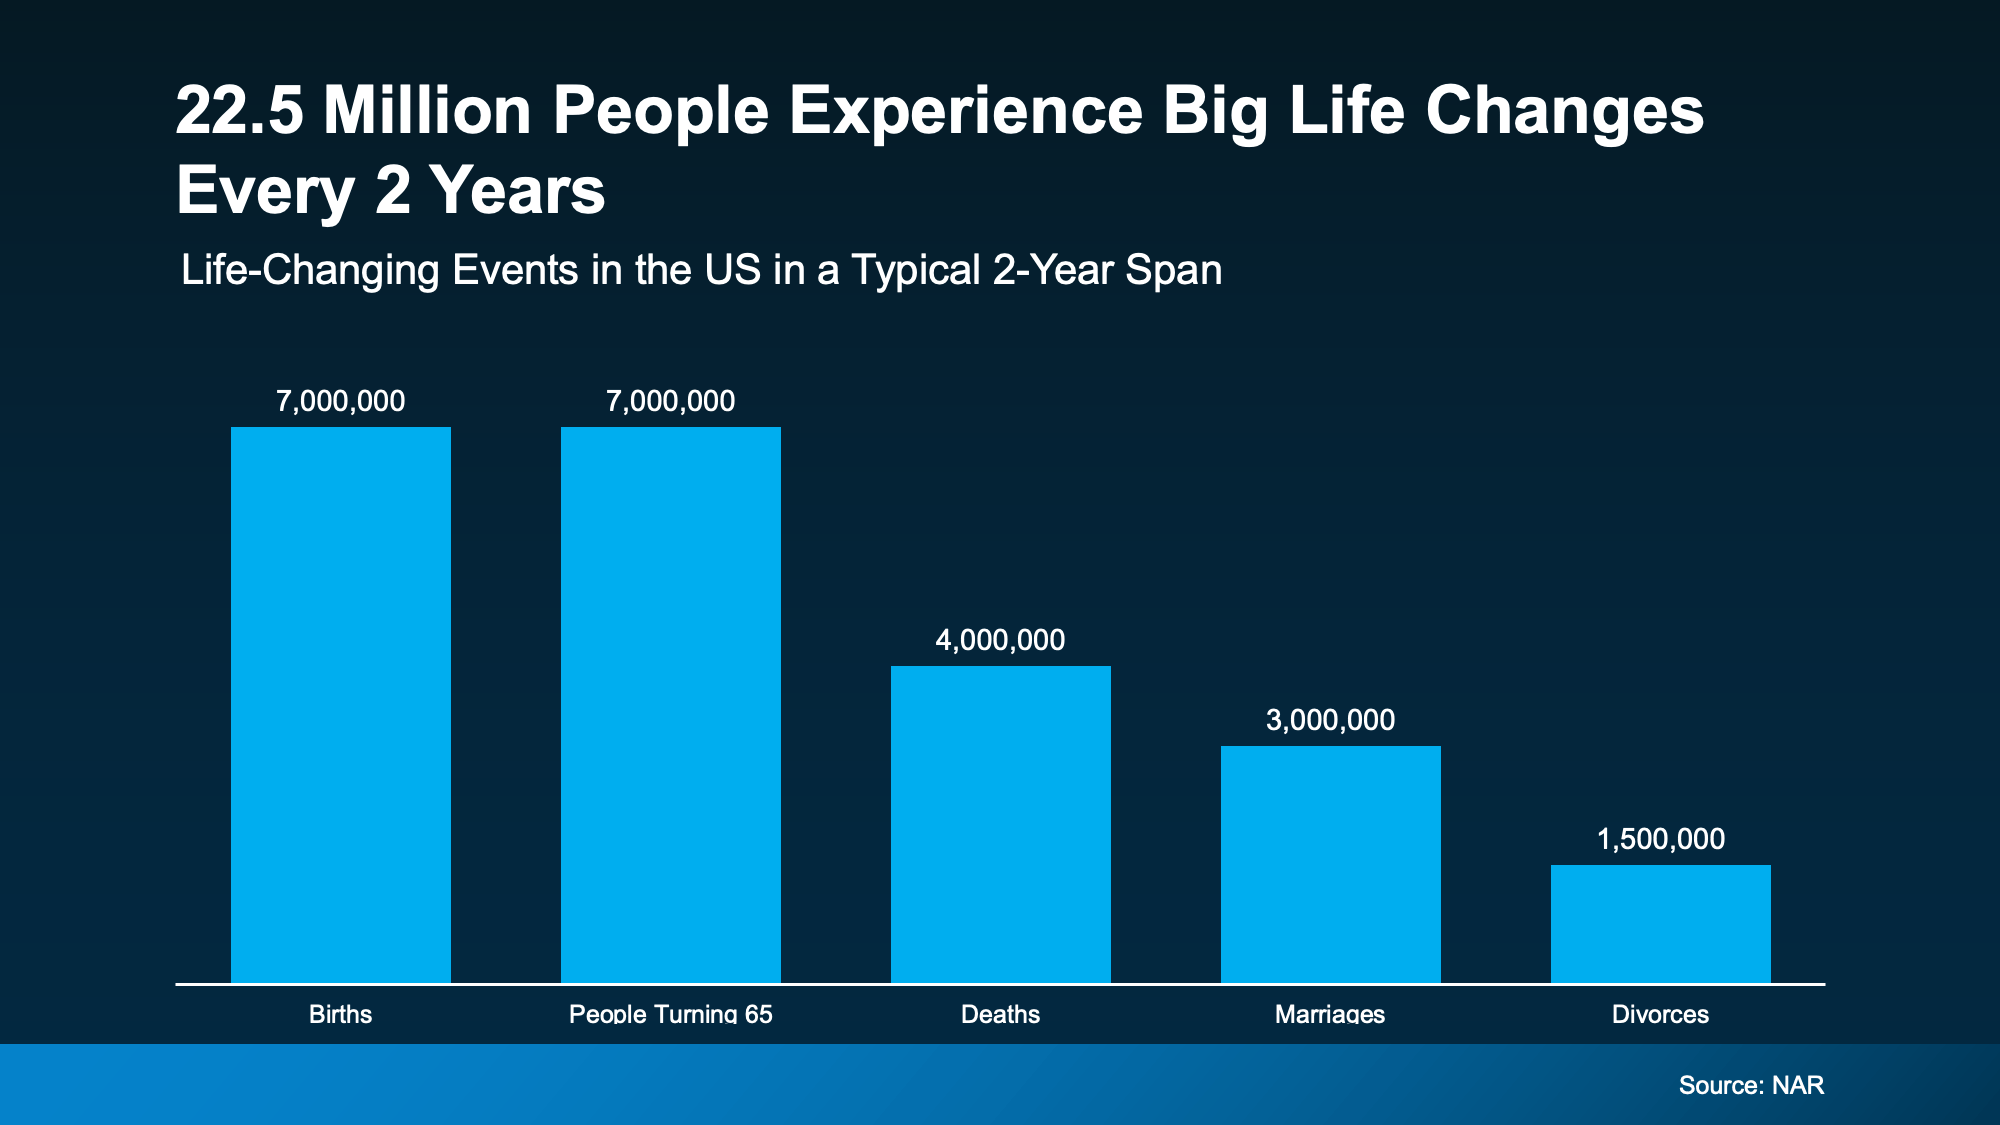
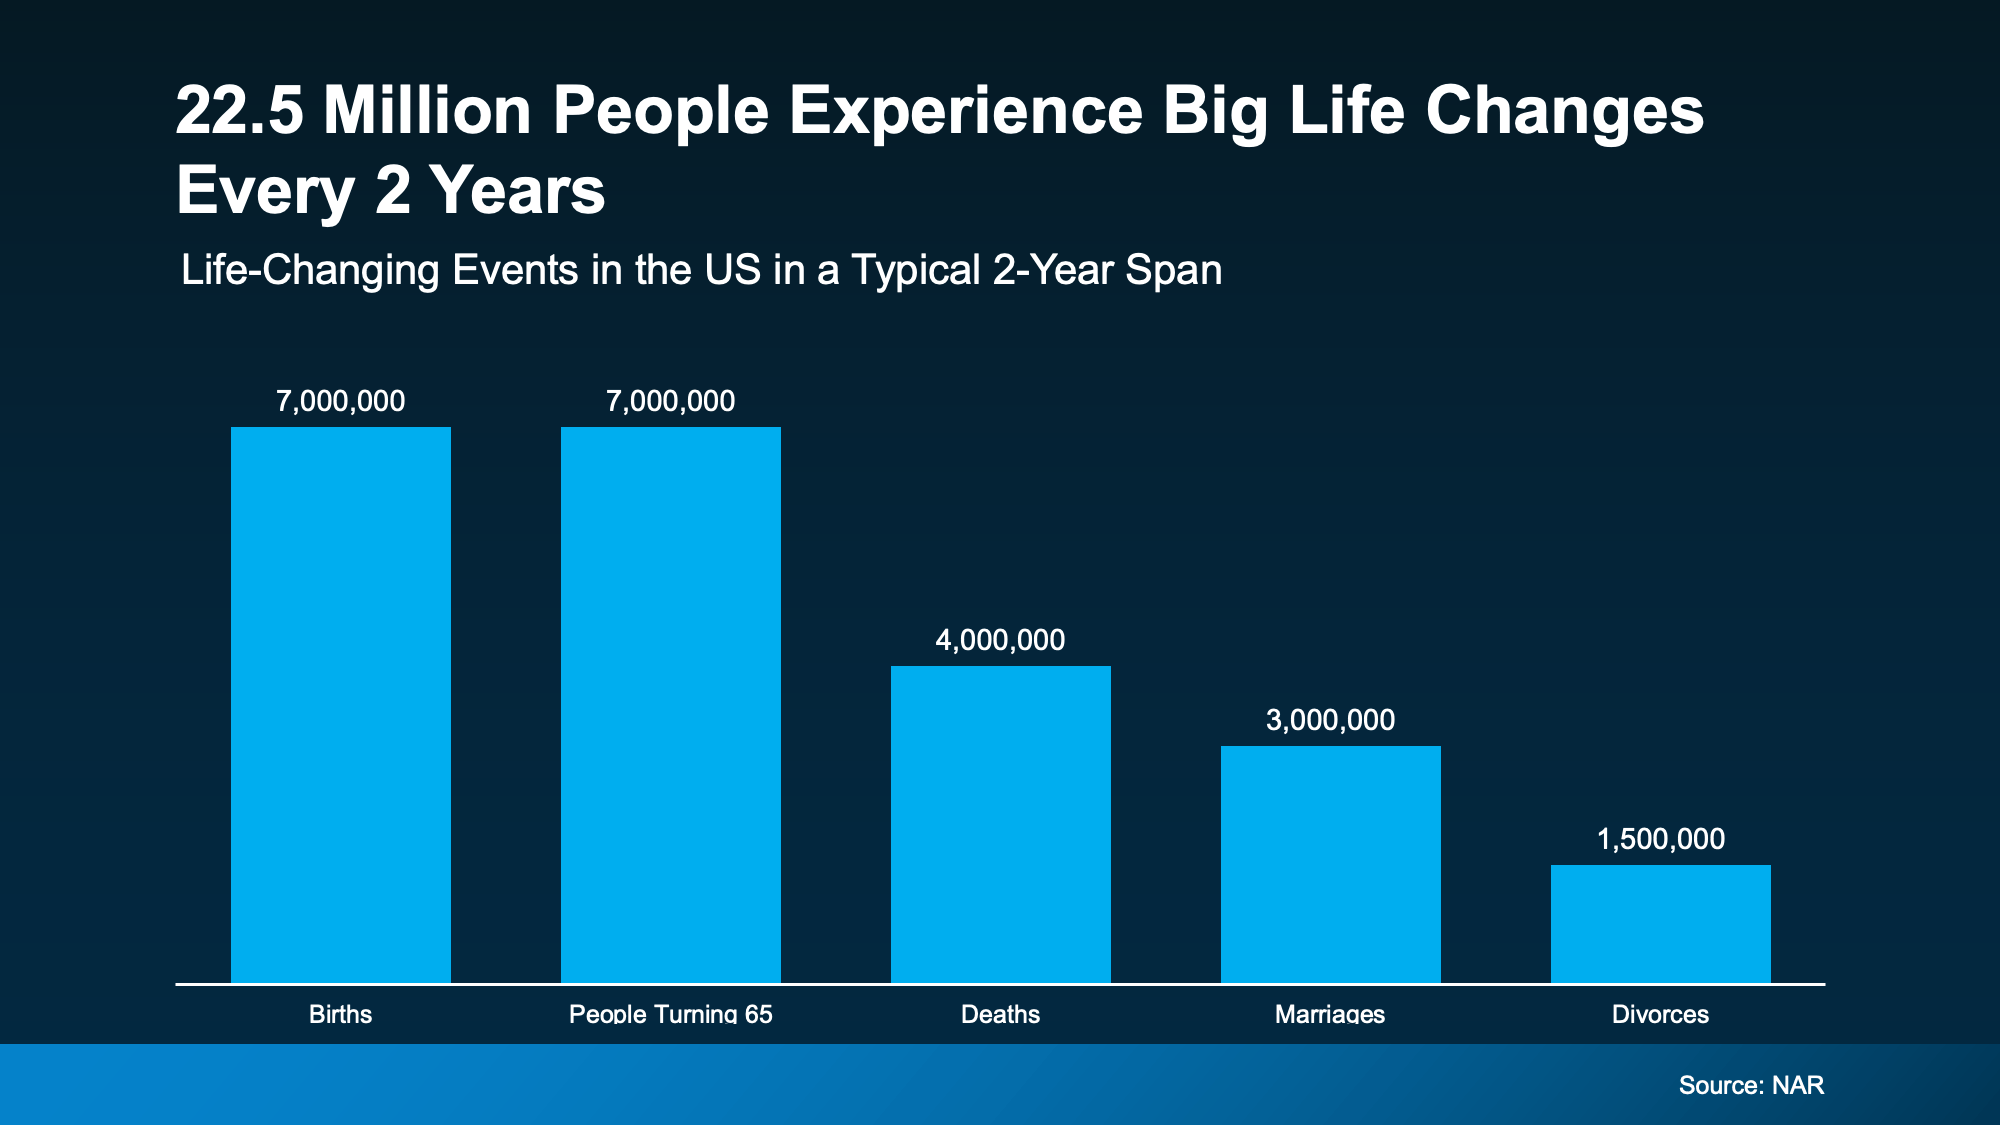
And those big life events happen more than you may think. NAR says roughly 22.5 million people experience major life changes in a typical two-year span (see graph below):

a graph of blue rectangular objects

These are exactly the kinds of things that can change how much space you need, where you want to live, or what kind of lifestyle makes sense now. Chen Zhao, Head of Economics Research at Redfin, explains:

“Life doesn’t stand still—people get new jobs, grow their families, downsize after retirement, or simply want to live in a different neighborhood.”

And that’s what makes waiting so hard. Every month you spend hoping the market changes is another month living in a house that no longer works for your life. It’s stressful to feel stuck. And that feeling usually doesn’t disappear.

There May Be More Opportunity Than You Think

But while affordability is still a challenge, there may still be a way for you to make your move.

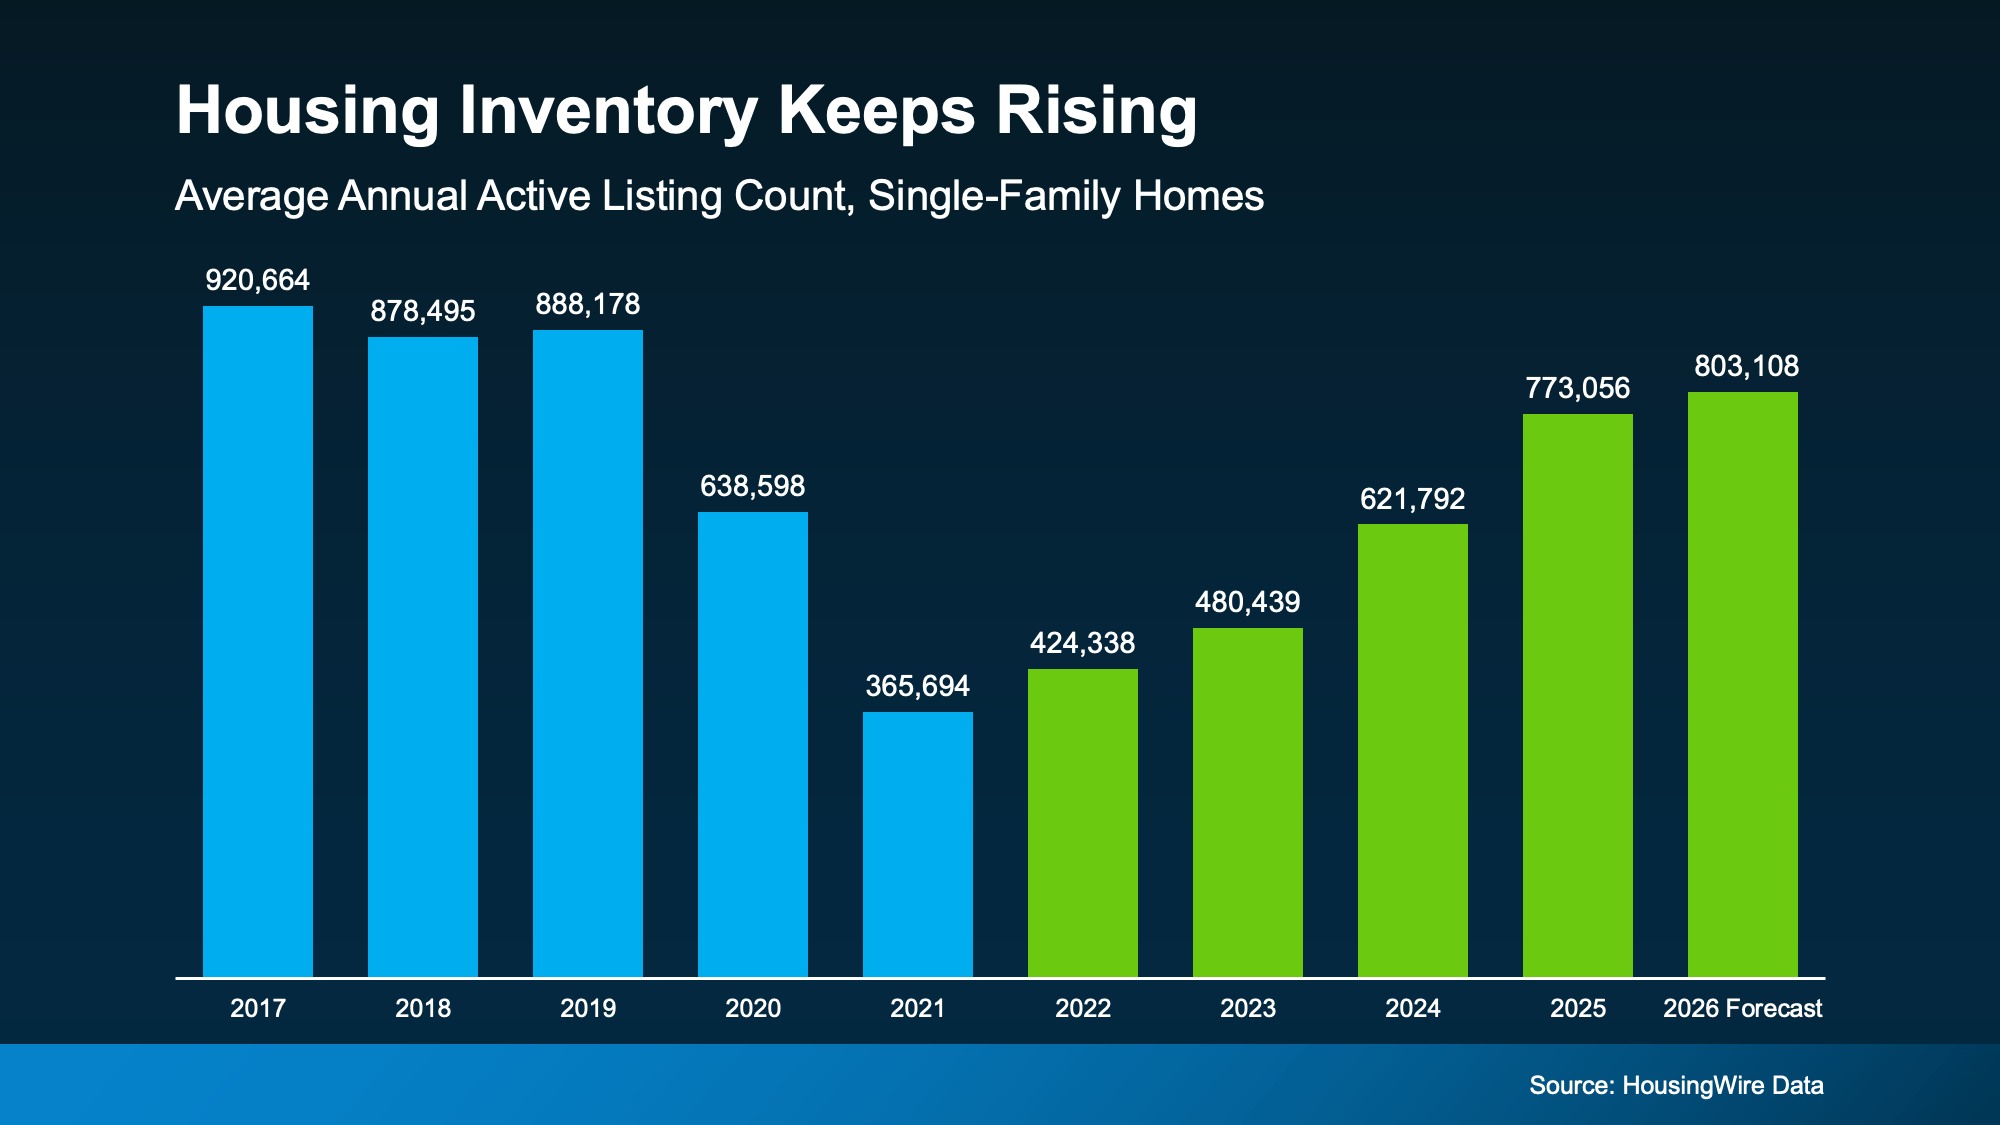
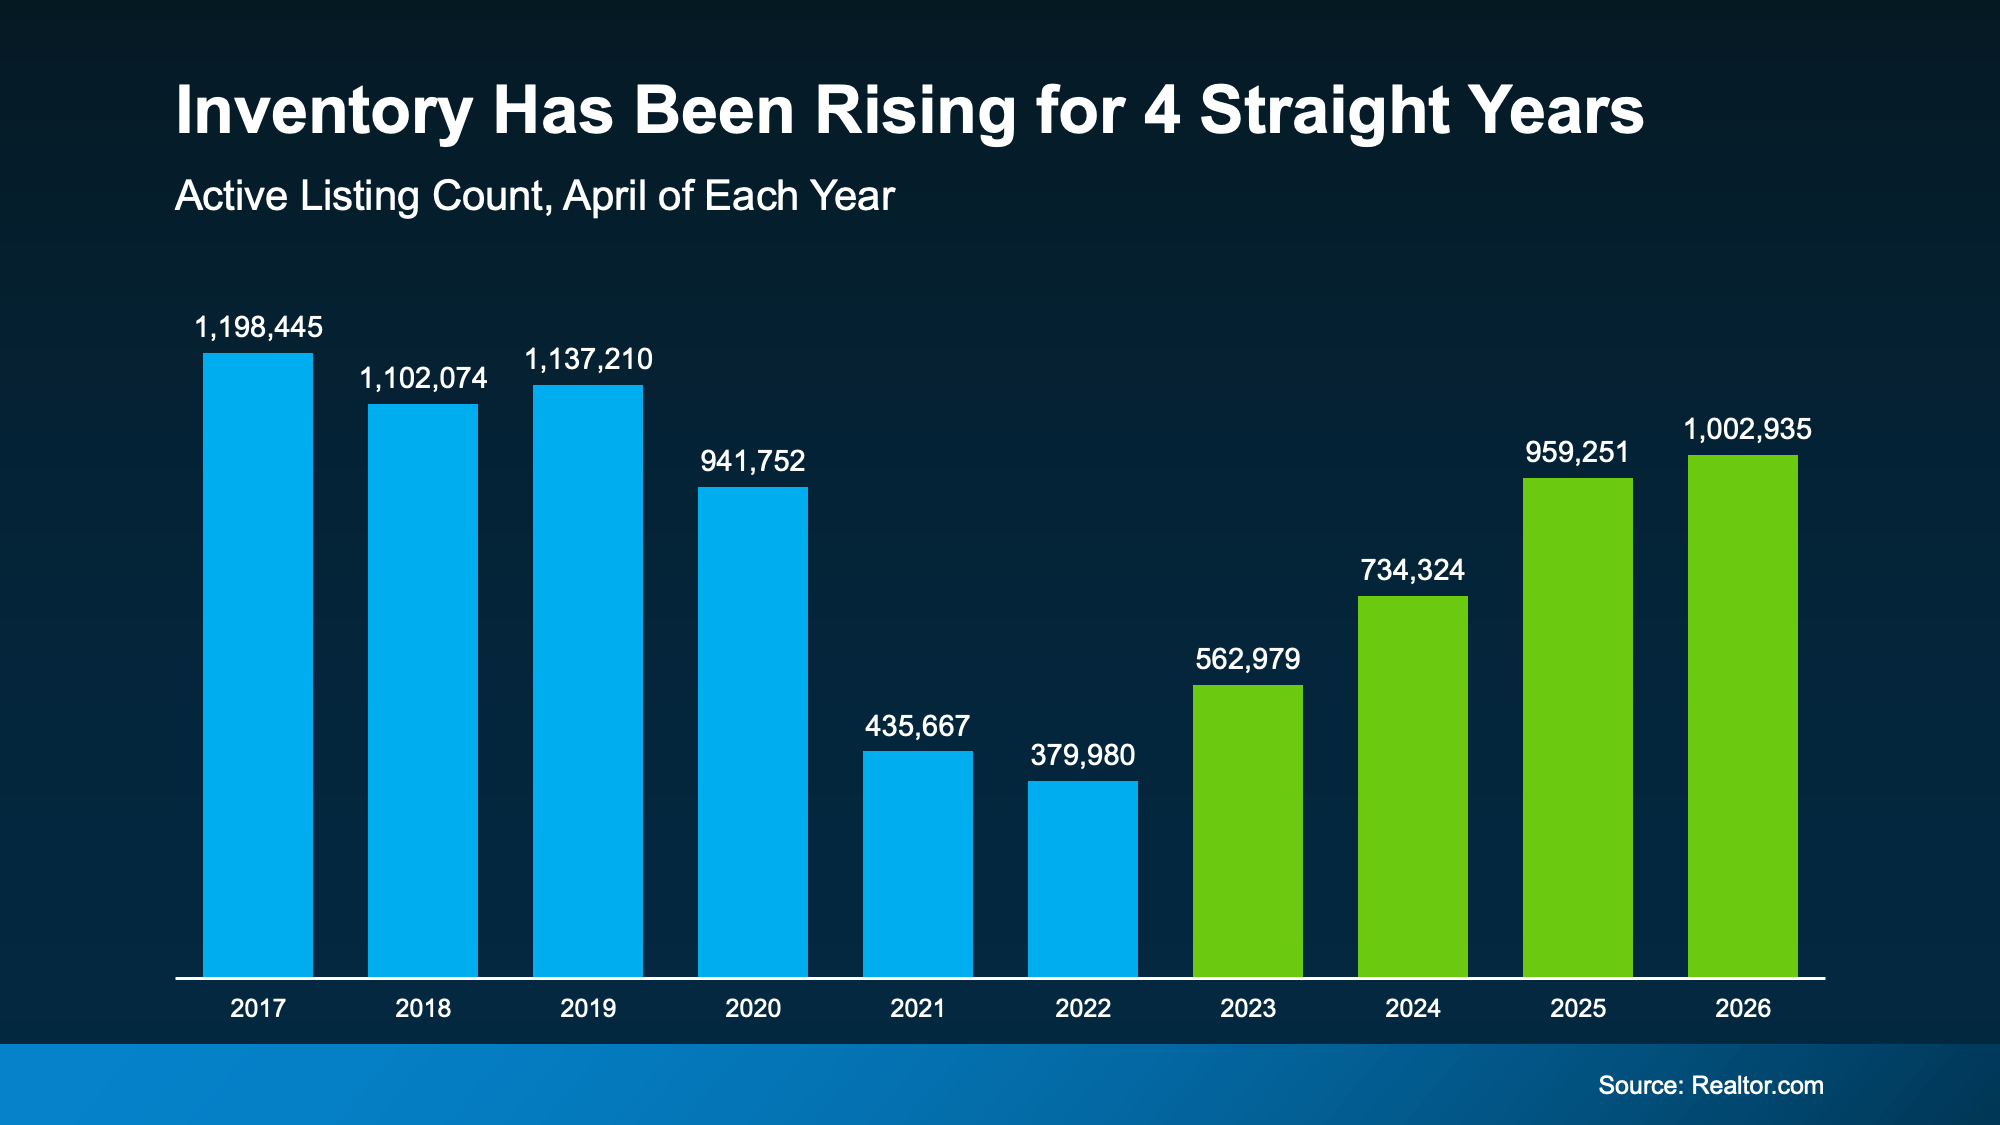
HousingWire Data shows the number of homes for sale has been growing for years (see graph below). That means more homes to choose from and, in some markets, more room to negotiate than buyers had just a few years ago.

a graph of a bar chart

That doesn’t mean moving is suddenly easy. But it does mean some buyers are finding ways to make a move work. So, if you’ve been putting your plans on hold, maybe the question isn’t just:

“What’s the market doing?” or “When will it get better?”

Maybe ask yourself this, too: “Can I still live where I'm at right now and make it work?”

If the answer to that second question is “no,” it may be worth having a conversation about what your options look like today – despite where rates or prices are. You could find your move is still possible after all. With more homes for sale, there’s a better chance to find one that fits your life (and your budget) right now.

[created_at] => 2026-09-17T20:37:29Z [description] =>

You may be telling yourself you’re going to wait to move – maybe you’re hoping mortgage rates will come down, prices will fall, or the market will feel a little easier.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260917/Header-Image-2022-Latino-Guide-original.png [id] => 111929 [kcm_ig_caption] => Life changes. Priorities shift. Families grow. Kids move out. Careers evolve. And eventually, the house you’re in may stop fitting the life you’re living. If that’s been weighing on you lately, let’s talk through what your options could realistically look like today, no matter where rates or prices are. Life can’t always wait for perfect market conditions. Maybe you don’t have to either. [kcm_ig_hashtags] => MakeMeMove,ReasonsToMove,KeepingCurrentMatters [kcm_ig_quote] => The market changed. Your reason for moving didn’t. [modified] => [poll] => [public_bottom_line] =>

Life changes. Priorities shift. Families grow. Kids move out. Careers evolve. And eventually, the house you’re in may stop fitting the life you’re living.

If that’s been weighing on you lately, talk to an agent about what your options could realistically look like today, no matter where rates or prices are.

Life can’t always wait for perfect market conditions. Maybe you don’t have to either.

[published_at] => 2026-09-01T10:30:00Z [related] => Array ( ) [related_to] => Array ( ) [shares] => 0 [slug] => the-market-changed-your-reason-for-moving-didnt [status] => published [tags] => Array ( ) [title] => The Market Changed. Your Reason for Moving Didn’t. [updated_at] => 2026-09-17T20:37:29Z [url] => /2026/09/01/the-market-changed-your-reason-for-moving-didnt/ )

The Market Changed. Your Reason for Moving Didn’t.

You may be telling yourself you’re going to wait to move – maybe you’re hoping mortgage rates will come down, prices will fall, or the market will feel a little easier.

9
stdClass Object
(
    [agents_bottom_line] => 

Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment.

That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while.

But if you’re interested, let this reassure you. If you want to talk through what home prices are doing in our market, your goals, or your timelines, let’s have a quick conversation.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 53 [name] => Rent vs. Buy [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => rent-vs-buy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Alquilar Vs. Comprar ) ) [updated_at] => 2019-06-03T18:18:43Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:21:25Z [id] => 326 [name] => Equity [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:42Z [slug] => equity [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Equidad ) ) [updated_at] => 2024-04-10T16:21:42Z ) ) [content_type] => blog [contents] =>

It’s one of the biggest hold ups some buyers have right now: “What if I buy, and home prices go down?”

With everything in the news, that concern makes some sense. No one wants to make a big financial decision at the wrong time. But here’s what’s important to know. You don’t want to get hung up on the few places seeing slight declines right now.

When you zoom out and look at the full picture, home prices usually rise over time.

What the Data Really Shows

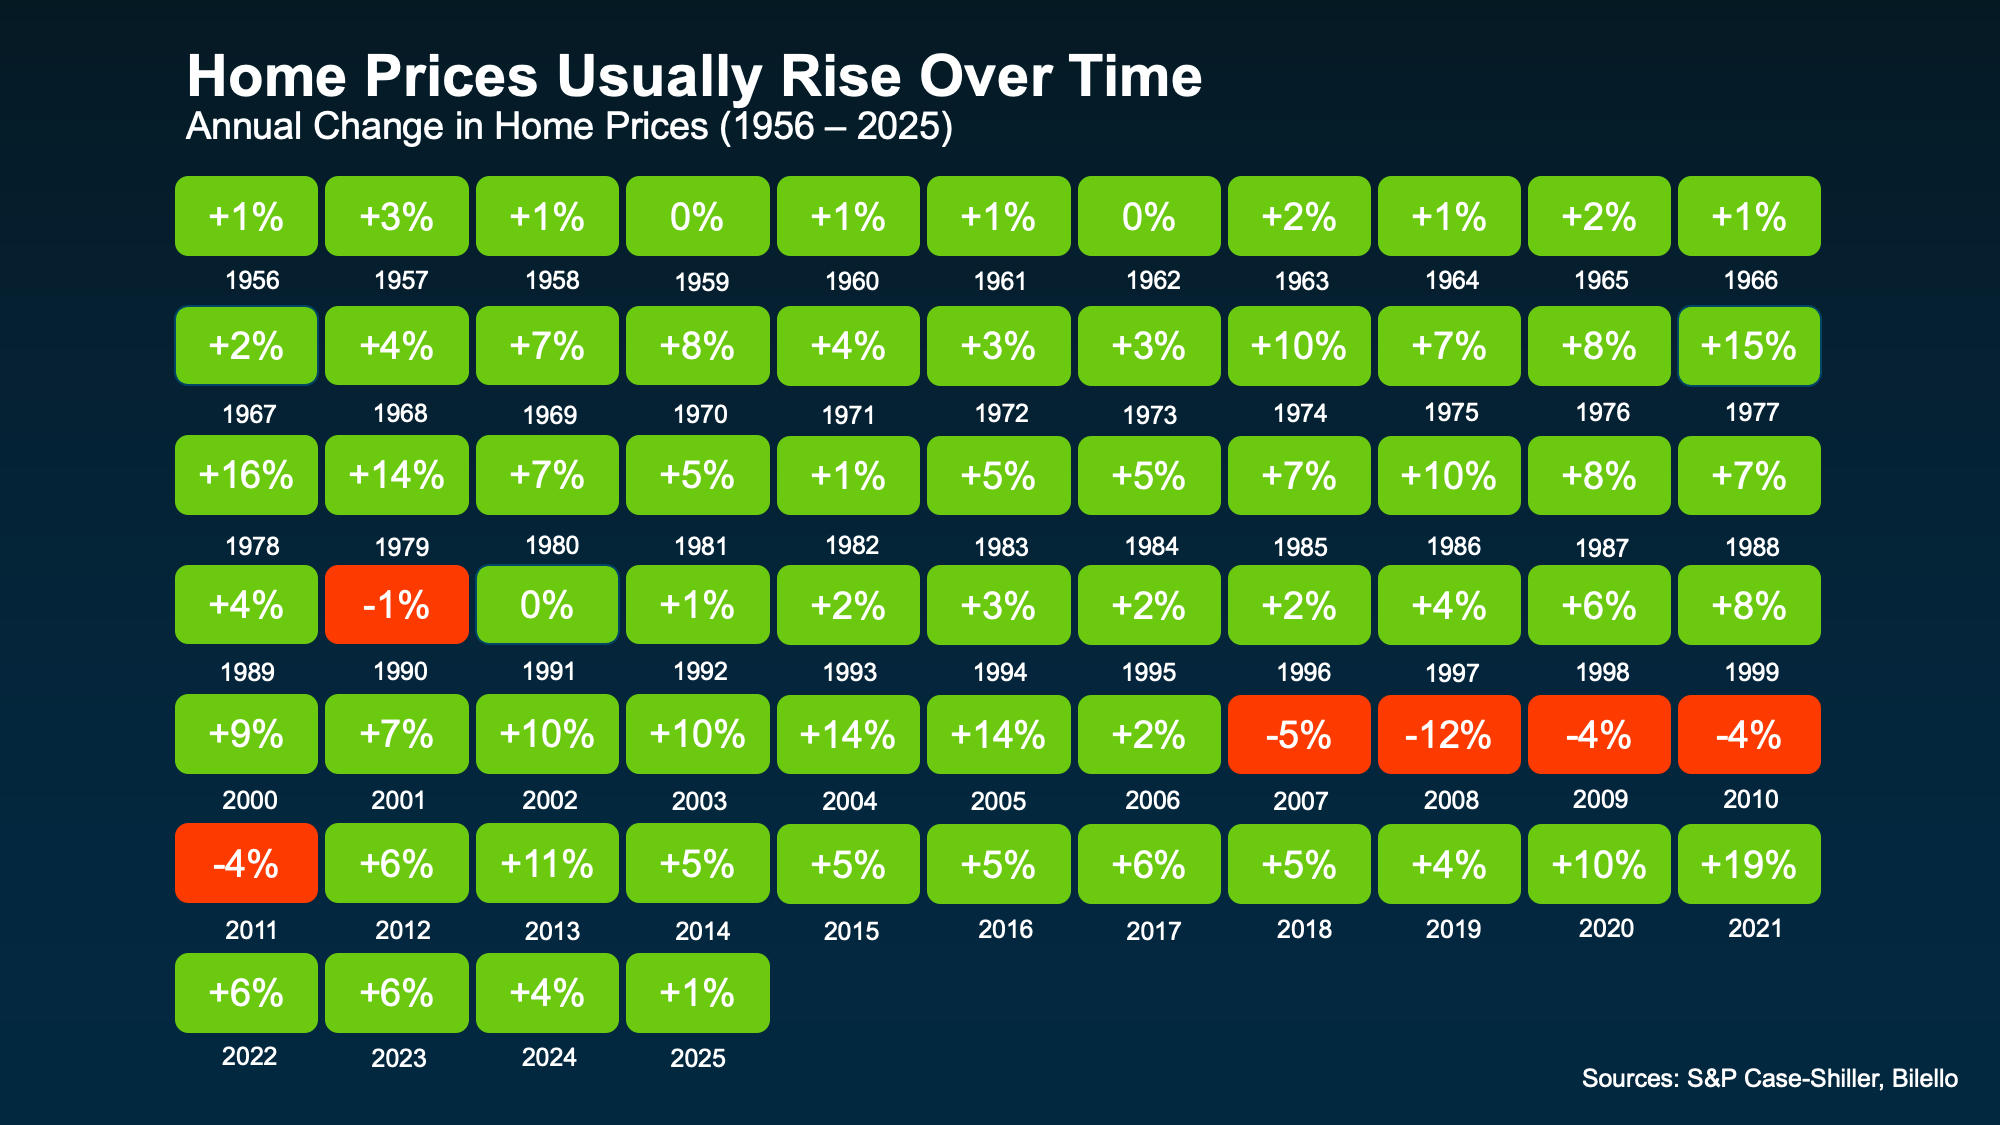
Take a look at the visual below. It uses data from Case-Shiller and Bilello to show how home prices have changed year by year going all the way back to the 1950s.

Here’s the key takeaway.

Outside of the housing crash, home prices have either held steady or increased in just about every year for decades (see visual below):

a chart of percentages and numbers

That’s a remarkably consistent track record. And it shows something a lot of headlines miss.

While short-term shifts can happen, it’s the long-term gains that really matter.

Why Prices Tend To Rise Over Time

There are a few core reasons prices usually go up each year:

  • There are always people who need to move. People need a place to live, and that demand will never fully go away. It may ebb and flow, but someone will always have to move as big changes happen in their life. So, homes stay in demand.

  • There still aren't enough homes for sale. While the number of homes for sale has grown, nationally there’s still an undersupply based on how many people want a home. That keeps upward pressure on prices.

  • Inflation has an impact. Over time, the cost of goods (including homes) naturally increases. That pushes home values higher.

What That Means for You as a Buyer

It’s easy to get caught up in what might happen with home prices next month or next year, especially if you’re a first-time buyer and you’re feeling a little anxious about making such a big financial commitment. But the big picture is clear. Prices usually rise.

That doesn’t mean prices will go up every single year in every market. Real estate is local, and there can be short-term ups and downs. We’re seeing that in some places right now. You can even see it in the few annual dips in the visual above.

But historically, the declines have been temporary.

That’s why it’s generally recommended to buy a home only if you plan to stay for a while – typically at least five years. That’s normally enough time to see your house grow in value. And, it’s enough so you can ride out any short-term changes in the market.

Because when you can do that, something powerful happens. Those rising home values grow your net worth, and by extension, help you build wealth.

The right decision isn’t about timing the market perfectly. It’s about making a move that works for your life and staying in it long enough to benefit from the bigger trend.

[created_at] => 2026-09-17T18:28:42Z [description] =>

It’s one of the biggest hold ups some buyers have right now: “What if I buy, and home prices go down?”

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260917/Header-Image-GettyImages-1192403701-1--original.png [id] => 111918 [kcm_ig_caption] => Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment. That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while. But if you’re interested, let this reassure you. If you want to talk through what home prices are doing in our market, your goals, or your timelines, let’s have a quick conversation. [kcm_ig_hashtags] => Homebuying,HomePrices,KeepingCurrentMatters [kcm_ig_quote] => Are home prices going to fall? Here’s what history says. [modified] => [poll] => [public_bottom_line] =>

Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment.

That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while.

But if you’re interested, let this reassure you. If you want to talk about what home prices are doing in our market, your goals, or your timelines, reach out to a local agent.

[published_at] => 2026-08-31T10:30:00Z [related] => Array ( ) [related_to] => Array ( ) [shares] => 0 [slug] => are-home-prices-going-to-fall-heres-what-history-says [status] => published [tags] => Array ( ) [title] => Are Home Prices Going To Fall? Here’s What History Says. [updated_at] => 2026-09-17T18:28:42Z [url] => /2026/08/31/are-home-prices-going-to-fall-heres-what-history-says/ )

Are Home Prices Going To Fall? Here’s What History Says.

It’s one of the biggest hold ups some buyers have right now: “What if I buy, and home prices go down?”

10
stdClass Object
(
    [agents_bottom_line] => 

Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.

If you're considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget. 


[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you've caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is. 

Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.

Why Dipping into a 401(k) Can Be Tempting

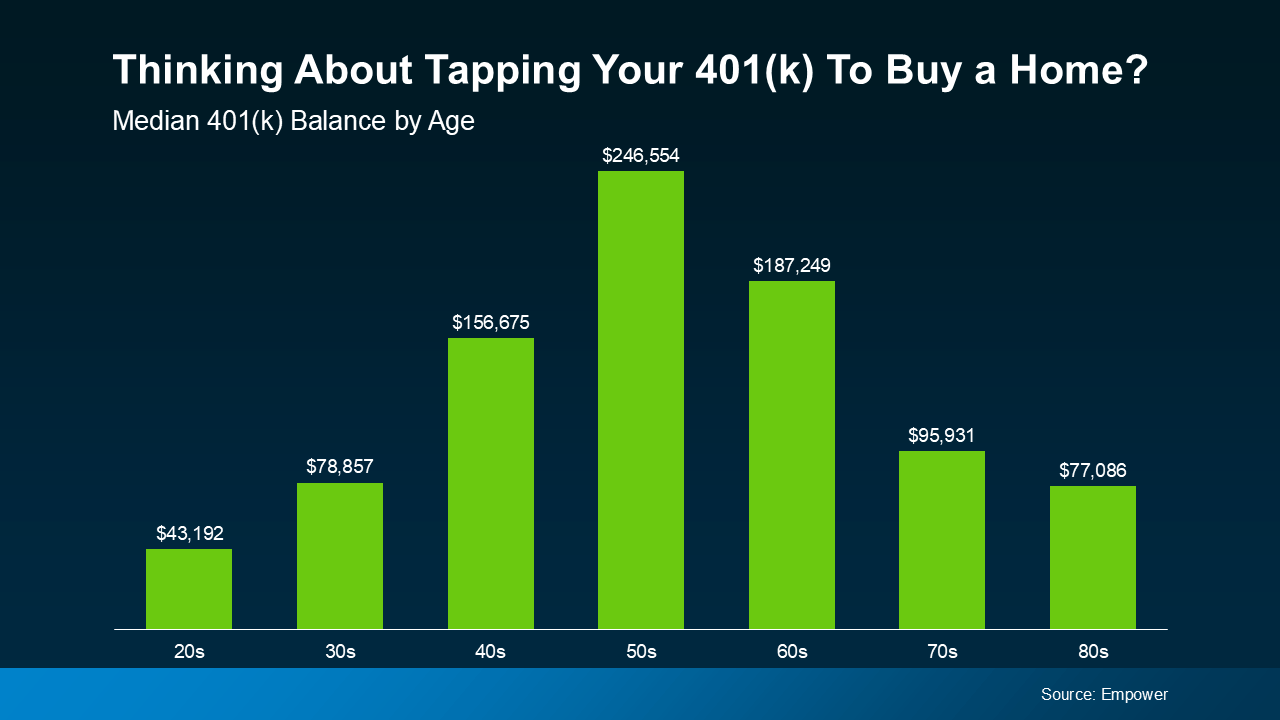
Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):

a graph of green barsAnd when you've got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call.
But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That's why it's a good idea to explore other options for your down payment first. As Redfin says: 

"If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth."

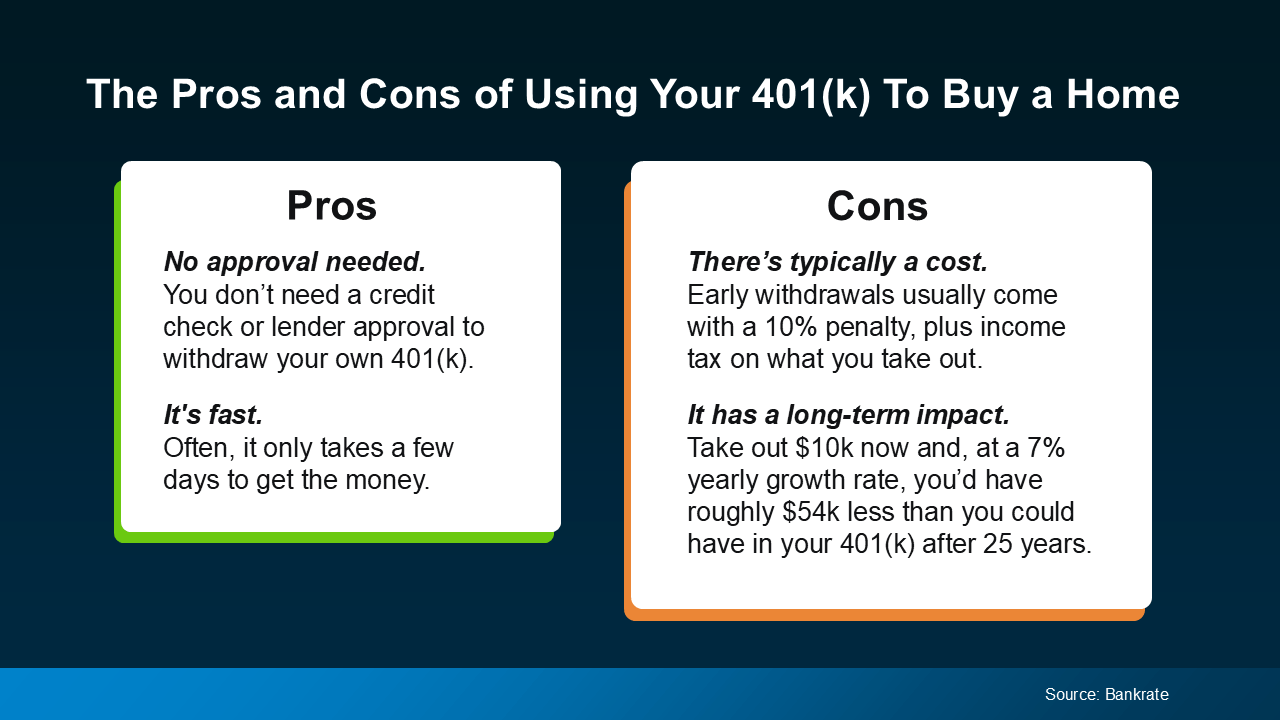
Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual):

a screenshot of a computer screen

Other Options Worth Exploring First

Your 401(k) isn’t the only way to finance a home purchase. Redfin outlines a few other options to look into before you decide what to do:

  • Low and No-Down Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home's price, depending on their credit scores.

  • Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.

Make a Plan Before You Make a Move

No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:

"Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset."

[created_at] => 2026-08-28T14:30:15Z [description] =>

Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260828/20260831-Blog-Image-original.png [id] => 111182 [kcm_ig_caption] => Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy. If you're considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget. [kcm_ig_hashtags] => DownPayment,HomebuyingTips,KeepingCurrentMatters [kcm_ig_quote] => Thinking about tapping into your 401(k) to buy a home? Read this first. [modified] => [poll] => [public_bottom_line] =>

Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.

If you're considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget. 


[published_at] => 2026-08-31T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 111184 [content_type] => must-share [title] => 8/31 Must Share ) ) [shares] => 0 [slug] => thinking-about-tapping-into-your-401k-to-buy-a-home-read-this-first [status] => published [tags] => Array ( ) [title] => Thinking About Tapping into Your 401(k) To Buy a Home? Read This First. [updated_at] => 2026-08-28T14:30:15Z [url] => /2026/08/31/thinking-about-tapping-into-your-401k-to-buy-a-home-read-this-first/ )

Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.

Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home.

11
stdClass Object
(
    [agents_bottom_line] => 

Most home sales still close, and the biggest thing that could get in the way of yours is the one thing you can actually do something about.

With the right prep, your sale has every reason to make it to the finish. So, let’s connect and get your house sold. 

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:16:32Z [id] => 321 [name] => Agent Value [parent] => [parent_id] => [published_at] => 2024-04-10T16:17:42Z [slug] => agent-value [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Valor del agente ) ) [updated_at] => 2024-04-10T16:17:42Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2025-10-30T18:12:44Z [id] => 339 [name] => Expired/Withdrawn/Canceled [parent] => [parent_id] => [published_at] => 2025-10-30T18:12:44Z [slug] => expiredwithdrawncanceled [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => ) ) [updated_at] => 2025-10-30T18:12:44Z ) ) [content_type] => blog [contents] =>

Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window.

But if you’re getting ready to sell, here’s what you should know. Even in today’s market, it rarely comes to that. Buyers who are moving at today’s rates and prices are generally moving because of some big life change. That means they’re motivated, and eager to get all the way to the closing table.

According to the latest data from Redfin, only about 1 in 7 pending sales are falling through. Meaning the vast majority make it all the way to closing.

And the single biggest thing that puts a deal at risk is the one you have the most power to prevent. It just takes a little smart planning before your house hits the market.

Why Some Deals Fall Apart Before Closing

A Redfin survey sheds light on the most common things that trip up a sale (see visual below):

a blue and orange chart with text

Here’s a bit more information on each one.

  • Inspection or repair issues. This is the big one. When a buyer’s inspector finds a problem, whether with the roof, the plumbing, the foundation, or elsewhere, the buyer can push back, ask you to make repairs, request a credit so they can do it themselves, or see if you’ll lower your price. If they don’t get what they want, they may walk away from the deal altogether.

  • The buyer’s financing fell through. Their mortgage loan has to be fully approved in time for closing day. If the loan doesn’t come together, the sale can’t move forward. 

  • The buyer’s current house didn’t sell. Some buyers need to sell their own home before they can close on yours. If that takes longer than expected, you may run into some issues with your timeline or even see them give up on their move.

  • There was a change in buyer’s financial situation. A new job, a big purchase, or new debt can change what a buyer qualifies for on their mortgage loan, even after they were pre-approved.

Where Your Agent Makes the Difference

Some of those reasons are outside your control, like whether a buyer’s loan clears or whether they sell their own home in time. But according to Zillow, there are a few proactive things you can do to help make sure your sale goes as smoothly as possible:

  • Save yourself the headache and get a pre-listing inspection. That’s when you get your own inspection before a buyer gets theirs. It lets you find the big issues before a buyer’s inspector does, so you can fix them or disclose them on your terms, instead of scrambling once you're under contract. In this situation, your agent will help you decide what's worth addressing and what to just disclose. Handle it now, and the biggest risk to your sale is behind you before a buyer ever brings it up.

  • Look at more than just the offer price. Your agent will help you weigh the whole offer, including the buyer’s timeline and any contingencies attached. When a buyer’s offer depends on selling their own home first, the success of your sale rides on a second deal you can’t see. Sometimes, a slightly lower offer with fewer strings is the safer one. Your agent will help you weigh your options and make a plan that works well for you. 

One of those is something you can’t do until you have offers in hand, but the other is something you can get ahead of right now. The pre-listing inspection.

That relatively small cost upfront can save you the much bigger hassle of a deal falling apart later. And while getting your own inspection before listing may not make sense in every market, your agent can tell you whether it’s worth it based on your market, your house, and what buyers are prioritizing in your area.

Sometimes the smartest move is staying one step ahead.

[created_at] => 2026-08-20T17:43:45Z [description] =>

Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260820/Header-Image-20220509-Blog-original.png [id] => 110901 [kcm_ig_caption] => Most home sales still close, and the biggest thing that could get in the way of yours is the one thing you can actually do something about. With the right prep, your sale has every reason to make it to the finish. So, let’s connect and get your house sold. [kcm_ig_hashtags] => SellingTips,SellYourHouse,KeepingCurrentMatters [kcm_ig_quote] => Most home sales close – Here’s how to keep yours on track. [modified] => [poll] => [public_bottom_line] =>

Most home sales still close, and the biggest thing that could get in the way of yours is the one thing you can actually do something about.

With the right prep, your sale has every reason to make it to the finish, and a good local agent can help you get there.

[published_at] => 2026-08-24T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110904 [content_type] => must-share [title] => 8/24 Must Share ) ) [shares] => 0 [slug] => most-home-sales-close-heres-how-to-keep-yours-on-track [status] => published [tags] => Array ( ) [title] => Most Home Sales Close – Here’s How To Keep Yours on Track [updated_at] => 2026-08-20T17:43:45Z [url] => /2026/08/24/most-home-sales-close-heres-how-to-keep-yours-on-track/ )

Most Home Sales Close – Here’s How To Keep Yours on Track

Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window.

12
stdClass Object
(
    [agents_bottom_line] => 

The number of homes for sale is growing slowly but surely, and that means more options for your move. Want to see what’s available in our area? Reach out, and let's take a look together.

[assets] => Array ( ) [banner_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260831/STM-Banner-6-original.jpg [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 42 [name] => Featured [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => featured [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Featured ) ) [updated_at] => 2019-06-03T18:18:43Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:06:50Z [id] => 320 [name] => Inventory [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:06Z [slug] => inventory [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Inventario ) ) [updated_at] => 2024-04-10T16:19:06Z ) ) [content_type] => blog [contents] =>

You may have heard the number of homes for sale isn’t growing like it was. And maybe that has you worried you won’t find a home you love when it’s time to make your move.

But that may be about to change. Here’s why your pool of options may actually start ticking back up again.

Growth Has Slowed, But It Hasn’t Stopped

Active listings were up 2.1% year-over-year in July, according to Realtor.com. Back in January, inventory was up 10%. And in May of 2025, it was up 31.5%. So, growth has cooled off a lot over the last year.

The past 3 months, though, have all seen inventory growth land in roughly the same range, which is a sign this slowdown may be nearing its floor (see graph below):

a graph of growth in a blue background

So, what does that mean for you?

Homes are still coming onto the market. Every single one of these bars shows a period where inventory grew. So, don’t be discouraged or let this make you think you’re out of options. Plus, we’ve seen more stability in the numbers lately, which is a good sign.

The Most Homes for Sale Since 2019

Compared to the rock-bottom lows of 2021, inventory has climbed back substantially. Nationally, the number of homes for sale has been up year-over-year consistently now for 33 months. And inventory has almost doubled in just a few years. So don’t get too hung up on the pace of that increase.

This July was actually the best July for inventory since 2019 (see graph below):

a graph of blue bars with white text

Now, the market still needs about 150k listings to get back to pre-pandemic levels, but things are quickly approaching normal. And experts think we may even be back to 2019 levels by the end of this year, even with the slowdown we’ve already seen.

And that’s thanks to one unlikely factor: mortgage rates. 

Why Higher Rates May Actually Help Inventory Grow

It works like this. When mortgage rates climb, inventory tends to climb with them. As Mike Simonsen, Chief Economist at Compass, explains:

“When rates rise; inventory rises. When rates fall; inventory falls. So, from July last year to March this year, rates ease lower and all the inventory growth of the past several years evaporated. If rates move higher from here or stay elevated for [a] longer period of time, then we should expect supply to build again.”

Well, rates are expected to hold in the mid-to-upper 6% range for a while longer, and Realtor.com's latest forecast has inventory ending 2026 up 3.6% year-over-year.

That means 2 things:

  • Inventory growth is forecast to pick up a little bit throughout the rest of the year.

  • And, inventory is projected to close the year at a historically normal level, right about where it stood at the end of 2019.

For buyers, that’s a win. Even if today’s rates aren’t your favorite, they’re helping the number of homes on the market to grow. And more homes for sale means more choices, more room to negotiate, and less pressure to rush your search.

[created_at] => 2026-08-18T15:24:39Z [description] =>

You may have heard the number of homes for sale isn’t growing like it was. And maybe that has you worried you won’t find a home you love when it’s time to make your move.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260818/Header-Image-6-original.png [id] => 110813 [kcm_ig_caption] => The number of homes for sale is growing slowly but surely, and that means more options for your move. Want to see what’s available in our area? Reach out, and let's take a look together. [kcm_ig_hashtags] => HomesForSale,HousingMarket,KeepingCurrentMatters [kcm_ig_quote] => Higher rates could actually help housing supply – Here’s how. [modified] => [poll] => [public_bottom_line] =>

The number of homes for sale is growing slowly but surely, and that means more options for your move. Want to see what’s available in your area? Reach out to a local real estate agent.

[published_at] => 2026-08-19T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110815 [content_type] => must-share [title] => 8/19 Must Share ) ) [shares] => 0 [slug] => higher-rates-could-actually-help-housing-supply-heres-how [status] => published [tags] => Array ( [0] => foundations ) [title] => Higher Rates Could Actually Help Housing Supply – Here’s How. [updated_at] => 2026-08-18T15:24:39Z [url] => /2026/08/19/higher-rates-could-actually-help-housing-supply-heres-how/ )

Higher Rates Could Actually Help Housing Supply – Here’s How.

You may have heard the number of homes for sale isn’t growing like it was. And maybe that has you worried you won’t find a home you love when it’s time to make your move.

13
stdClass Object
(
    [agents_bottom_line] => 

If you've been putting your home search on hold because you're convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy.

Let’s connect so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:20:58Z [id] => 325 [name] => Economy [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:04Z [slug] => economy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Economía ) ) [updated_at] => 2024-04-10T16:21:04Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:04Z [id] => 327 [name] => Forecasts [parent] => [parent_id] => [published_at] => 2024-04-10T16:22:19Z [slug] => forecasts [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Previsiones ) ) [updated_at] => 2024-04-10T16:22:19Z ) ) [content_type] => blog [contents] =>

Imagine waiting a year to buy a home, only to find mortgage rates haven't changed much. That may sound frustrating.But it's a real possibility.

A lot of people are putting their plans on hold because they believe much lower mortgage rates are right around the corner. But, based on today's forecasts, that may not happen. And you should know that before you decide what to do.

Let's look at why experts don't expect a dramatic drop in rates – and the options that could help you buy anyway. Because even if rates don’t fall, you can still move. Here’s how.

1. Mortgage Rates Aren’t Expected To Fall in a Meaningful Way

If you're waiting for rates to fall, you're not alone. A recent survey from Clever-Best Interest found 42% of people believe mortgage rates will drop below 5% this year.

The challenge is, that's not what the experts who study mortgage rates every day are expecting.

Forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo all show mortgage rates staying relatively steady in the low-to-mid 6% range through at least mid-2027 (see graph below):

a graph with numbers and lines

Why? Rates are influenced by inflation, the overall economy, Treasury yields, Federal Reserve policy, global events, and a lot of other moving pieces. And right now, those factors simply aren't pointing toward the kind of dramatic rate drop many buyers are waiting for.

Could rates move a little? Of course. But if you're holding out for a bigger drop, today's forecasts suggest you may be waiting a lot longer than you expect.

2. Inflation Is Still Elevated – And That’s Working Against Lower Rates 

One reason experts aren't expecting rates to fall much? Inflation. Generally speaking, high inflation is the enemy of lower mortgage rates.

And after a period of relative stability from mid 2023 to late 2025, recent data shows inflation has actually been trending higher lately (see graph below):

a graph of a number of people 

In other words, one of the biggest ingredients needed for much lower mortgage rates simply isn't in place today. That helps explain why experts aren't forecasting the kind of meaningful decline so many buyers are hoping for.

3. Today’s Rates Aren’t High, They’re "Normal"

And this may be the biggest mindset shift of all. The reality is, while today's rates may feel high compared to a few years ago, they're not high. They’re normal.

Historically, mortgage rates have spent the majority of their time somewhere between about 5% and 10%. And data from Freddie Mac shows we’re actually well in that range today. It just feels high because we all remember the ultra-low rates homeowners got during the pandemic (see graph below):

a graph of a graph showing the rise of a mortgage rate 

Now, this doesn't suddenly make a 6% mortgage feel exciting. But it does remind us that waiting for super low rates again may not be a realistic strategy.

So... What Should You Do Instead?

None of this is meant to convince you that you have to buy today. You don’t. But if you need to because something in your life’s changed, there are still ways to find better affordability without waiting for mortgage rates to fall.

  • Check out newly built homes. Many builders are offering incentives to attract buyers, including price cuts, potentially lower rates, free upgrades, and more.

  • Ask about an adjustable-rate mortgage (ARM). If you don't plan to stay in the home long-term, an ARM may offer a lower initial interest rate than a traditional 30-year fixed mortgage. It's not the right choice for everyone, but it's worth asking a lender if it fits your plans.

  • Look into mortgage rate buydowns. This is when you pay upfront to reduce your mortgage rate so you can get for a lower monthly payment without waiting for rates to fall.

  • Find out about assumable mortgages. An assumable mortgage allows you to take over the seller’s existing loan, including its lower mortgage rate.

The important thing is you shouldn’t assume waiting is your only option.

Talk with your real estate agent and lender about whether one of these strategies could be a good fit for you.

[created_at] => 2026-08-05T15:08:43Z [description] =>

Imagine waiting a year to buy a home, only to find mortgage rates haven't changed much. That may sound frustrating. But it's a real possibility.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260805/Header-Image-20221117-SG-original.png [id] => 110371 [kcm_ig_caption] => If you've been putting your home search on hold because you're convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy. Let’s connect so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer. [kcm_ig_hashtags] => HomeAffordability,MortgageRates,KeepingCurrentMatters [kcm_ig_quote] => Thinking about waiting for lower mortgage rates? Read this first. [modified] => [poll] => [public_bottom_line] =>

If you've been putting your home search on hold because you're convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy.

Connect with an agent or lender so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer.

[published_at] => 2026-08-06T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110372 [content_type] => must-share [title] => 8/6 Must Share ) ) [shares] => 0 [slug] => thinking-about-waiting-for-lower-mortgage-rates-read-this-first [status] => published [tags] => Array ( ) [title] => Thinking About Waiting for Lower Mortgage Rates? Read This First. [updated_at] => 2026-08-05T15:08:43Z [url] => /2026/08/06/thinking-about-waiting-for-lower-mortgage-rates-read-this-first/ )

Thinking About Waiting for Lower Mortgage Rates? Read This First.

Imagine waiting a year to buy a home, only to find mortgage rates haven't changed much. That may sound frustrating. But it's a real possibility.

14
stdClass Object
(
    [agents_bottom_line] => 

Big investors are stepping back, and they're adding homes to the market as they go. If you've been waiting for a better shot at buying, this could be it. Let’s connect so you can see what's popping up in our area. You may have more options than you think.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) ) [content_type] => blog [contents] =>

For years, a lot of would-be homebuyers have worried about the same thing. How do you compete with big investors who can swoop in, pay cash, and snap up the houses you want?

Well, worry a little less. Because right now, those big investors aren't buying up the market. They're backing out of it.

Investors Are Buying Fewer Homes Than They Have in Years

According to Redfin, investor home purchases just fell to their lowest level since 2020 – when the start of the pandemic temporarily caused pretty much all homebuying to pull way back. Before that, you'd have to go all the way back to 2016 to find a time when investors bought this few homes (see graph below):

a graph of sales in the fall

Why the step back? Two big reasons.

First, Washington passed a housing law that takes aim at large institutional investors. To be clear, these mega investors were never as big a part of the market as the headlines made it sound. They’ve always made up a relatively small slice of housing pie. But the law still targeted the largest ones, and it worked fast. According to Thom Malone, Principal Economist at Cotality:

“When Washington announced its intention to curb institutional investors’ homebuying, the market reacted. . . Cotality data shows that investment by mega investors who own 1,000 or more properties retracted almost instantly.”

Second, the housing market has cooled. Price growth has slowed in much of the country, and in some markets, prices are dipping. That makes the math a lot less appealing for investors betting on quick gains. Lance Lambert, CEO of ResiClub, explains:

“Ever since rates spiked and the Pandemic Housing Boom fizzled out in spring 2022, institutional single-family rental (SFR) operators have pulled way back from buying up homes on the resale market—the math just isn't as appealing right now. Home prices and rents are no longer ripping, holding costs (property taxes and insurance) have jumped, capital markets have shifted their attention elsewhere, and elevated materials prices make renovations expensive.”

They’re Not Just Buying Less – They’re Selling More

This is the part most people miss. Big investors aren't just slowing down their purchases. Data from Parcl Labs and ResiClub shows the largest institutional investors are now selling more homes than they're buying – and that gap is growing these past 4 quarters (see graph below):

a graph of a graph showing the price of a home sold

Every one of those homes goes right back into the market for buyers like you. And since big investors tend to own homes at the lower end of the price range, a lot of what they're selling is exactly the kind of home first-time buyers are looking for. As Malone puts it:

". . . this sudden dropoff in institutional investment is a signal to first-time homebuyers that there's an opening."

Less competition from deep-pocketed buyers. More homes hitting the market. And many of them at prices that work for a first purchase. That's a shift that works in your favor.

[created_at] => 2026-07-30T16:51:09Z [description] =>

For years, a lot of would-be homebuyers have worried about the same thing. How do you compete with big investors who can swoop in, pay cash, and snap up the houses you want?

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260730/Header-Image-Summer-2023-Guide-28--original.png [id] => 110206 [kcm_ig_caption] => Big investors are stepping back, and they're adding homes to the market as they go. If you've been waiting for a better shot at buying, this could be it. Let’s connect so you can see what's popping up in our area. You may have more options than you think. [kcm_ig_hashtags] => FirstTimeHomebuyer,HouseHunting,KeepingCurrentMatters [kcm_ig_quote] => Big investors are backing off and that’s your opening. [modified] => [poll] => [public_bottom_line] =>

Big investors are stepping back, and they're adding homes to the market as they go. If you've been waiting for a better shot at buying, this could be it. Connect with a local agent to find out what's popping up in your area. You may have more options than you think.

[published_at] => 2026-08-05T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110207 [content_type] => must-share [title] => 8/5 Must Share ) ) [shares] => 0 [slug] => big-investors-are-backing-off-and-thats-your-opening [status] => published [tags] => Array ( [0] => foundations ) [title] => Big Investors Are Backing Off and That’s Your Opening [updated_at] => 2026-07-30T16:51:09Z [url] => /2026/08/05/big-investors-are-backing-off-and-thats-your-opening/ )

Big Investors Are Backing Off and That’s Your Opening

For years, a lot of would-be homebuyers have worried about the same thing. How do you compete with big investors who can swoop in, pay cash, and snap up the houses you want?

15
stdClass Object
(
    [agents_bottom_line] => 

There's no one-size-fits-all answer to buying and selling at once. But for a lot of homeowners, leading with the sale makes moving easier on their mind and their wallet.

Let’s connect, so you can navigate selling and buying with more confidence, more financial power, and less stress.

[assets] => Array ( ) [can_share] => no [categories] => Array ( ) [content_type] => blog [contents] =>

If you're a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you start looking?

There's no single right answer. The best call depends on your finances, your local market, and your timeline. And a trusted agent can help you weigh all of it.

But in a lot of cases these days, selling first puts you in the stronger spot.

The Advantages of Selling First

Selling is usually the trickier half of a move today, so getting it done first clears your biggest hurdle. And that’s especially true right now, because there are more homes for sale than there are buyers, which means houses are taking longer to sell than they did a year or two ago.

So how does leading with your sale pay off? Let’s start with the money.

1. You Won’t Get Stuck Paying Two Mortgages

Buy before you sell, and you could end up carrying two mortgages at once. And especially since houses are staying on the market longer these days, that overlap may drag on for more time than you’d planned. And if unexpected repairs come up, it could get even more expensive.

Selling first takes that risk off the table, so you’re not multitasking homeownership. As Ramsey Solutions puts it:

"It's best to sell your old home before buying a new one to avoid unnecessary risks and possible headaches."

2. You Can Use Your Equity To Fuel Your Move

This is always true, but one of the biggest perks of selling first is that you’ll know exactly how much money you're walking away with. And one of the big figures that matters in that conversation is how much equity you have in your current place.

Equity is basically your house’s value minus what you still owe on your mortgage. And it adds up fast. According to Realtor.com, homeowners who’ve been in their home for 5 years have about $180,000 in equity on average. And those who’ve had their home for 6-10 years? They have over $340,000.

After you sell, you can use that money to cover your down payment or even buy your next home in cash. And knowing that profit up front helps you plan your next move.

3. Your Offer Will Be Hard To Pass Up

When your house is already sold, you don’t have to make your offer contingent on that sale. In a market where buyers are taking their time, that’s exactly what a seller wants to see.

Picture it from the seller’s side. If their house has been sitting for a while, they’ll gravitate toward the offer most likely to close without a snag.

That can also give you room to ask for a little more, like repairs, since a motivated seller would rather keep things moving than lose you and wait for another offer to come in. Your agent can help you make the most of your upper hand in that scenario.

Is There a Catch?

Selling first has its tradeoffs too, and it helps to see the pros and cons side by side before you decide. Here’s a quick breakdown based on information from Zillow (see visual below):

a screenshot of a video game 

The cons are manageable with the right plan, so talk about them with your agent. They can help you negotiate things like a rent-back, where you stay in your house for a set time after closing, or line up flexible closing dates to keep the transition smooth.

[created_at] => 2026-07-30T16:11:29Z [description] =>

If you're a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you start looking?

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260730/Header-Image-Summer-2023-Guide-13--original.png [id] => 110198 [kcm_ig_caption] => There's no one-size-fits-all answer to buying and selling at once. But for a lot of homeowners, leading with the sale makes moving easier on their mind and their wallet. Let’s connect, so you can navigate selling and buying with more confidence, more financial power, and less stress. [kcm_ig_hashtags] => SellYourHouse,HomeEquity,KeepingCurrentMatters [kcm_ig_quote] => Here’s where to start if you’re selling and buying at the same time. [modified] => [poll] => [public_bottom_line] =>

There's no one-size-fits-all answer to buying and selling at once. But for a lot of homeowners, leading with the sale makes moving easier on their mind and their wallet.

Connect with a local agent, and they’ll help you navigate selling and buying with more confidence, more financial power, and less stress.

[published_at] => 2026-08-03T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110200 [content_type] => must-share [title] => 8/3 Must Share ) ) [shares] => 0 [slug] => heres-where-to-start-if-youre-selling-and-buying-at-the-same-time [status] => published [tags] => Array ( ) [title] => Here’s Where To Start if You’re Selling and Buying at the Same Time [updated_at] => 2026-07-30T16:11:29Z [url] => /2026/08/03/heres-where-to-start-if-youre-selling-and-buying-at-the-same-time/ )

Here’s Where To Start if You’re Selling and Buying at the Same Time

If you're a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you start looking?

16
stdClass Object
(
    [agents_bottom_line] => 

Home price growth slowed way down, and now it's showing early signs of picking back up. Whether you're buying or selling, let's connect so you can see exactly what prices are doing in our local market and what that means for your plans.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) ) [content_type] => blog [contents] =>

After more than a year of headlines talking about how home prices are going to crash, the latest data shows that price growth may be starting to pick back up again. And depending on whether you’re buying or selling, that shift means something different for you.

The Numbers May Be Starting To Turn

For the past couple of years, home price growth has been moderating – cooling from around 7% in mid-2024, according to Redfin (see graph below). But look at the right side of that graph. The pace of that growth appears to have hit its low point and started to turn.

a graph of growth in a number of years

While a couple months of data doesn’t necessarily mean this will be a lasting trend, there are some other signs that this could continue.

For example, fewer markets are seeing prices decline. According to ResiClub and Zillow, about 36% of the 300 largest housing markets had falling prices as of the middle of last year. Since the start of this year, that share has been shrinking. Now? Only 23% are experiencing those mild dips (see graph below):

a graph of the price of a house

When fewer markets see prices falling, that means more markets are seeing prices rise again.

And forecasts suggest this shift has room to run. On average, experts project home prices will rise about 2.3% nationally this year. And for that to happen, price growth would have to pick up a bit in the second half of 2026.

But Remember, Real Estate Is Local

While it looks like national prices may be starting to pick back up a tiny bit, that doesn’t mean that’s what’s happening in your neighborhood.

National home prices are really just an average of hundreds of local markets. Some are climbing faster. Others are still cooling. But one reason the national average may be looking up is because a growing number of metros may actually be net positive for prices this year.

Not long ago, the major metros were split about 50/50 – half seeing prices rise and half seeing them fall. Now, that balance looks like it’s starting to tip in a more positive direction. Just last month, more than half of the major metros saw prices go up, according to Redfin (see graph below):

a graph of prices on a dark background

As Selma Hepp, Chief Economist at Cotality, explains:

“. . . local markets continue to tell very different stories. Annual home price growth has changed little since the start of the year, but some markets, especially those supported by strong job and income growth in the West and more affordable Midwest markets, have seen notable acceleration in price gains.”

What This Means for You

Home price headlines can be confusing because they don’t always tell the full picture. Lean on an agent to understand what’s happening in your local market and what the early signs say for where prices may go from here.

That’s the best way to stay one step ahead of the market.

If you're buying: slower price growth has worked in your favor. You've had more room to negotiate and a budget you could plan around. If price growth is picking up in your area, buying now may mean paying less than you would later this year.

If you own a home: you've been gaining equity all along, even while growth moderated. If growth keeps picking up, those gains could speed up, too. Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), projects the typical homeowner will gain roughly $16,000 in housing wealth this year. And if you're thinking about selling, this shift is a good early sign for you. Just remember, the market is still pretty balanced and buyer-friendly in a lot of areas right now.

Home price growth slowed way down, and now it's showing early signs of picking back up. Whether you're buying or selling, let's connect so you can see exactly what prices are doing in our local market and what that means for your plans.

[created_at] => 2026-07-28T18:51:24Z [description] =>

After more than a year of headlines talking about how home prices are going to crash, the latest data shows that price growth may be starting to pick back up again.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260728/Header-Image-20230103-Blog-original.png [id] => 110129 [kcm_ig_caption] => Home price growth slowed way down, and now it's showing early signs of picking back up. Whether you're buying or selling, let's connect so you can see exactly what prices are doing in our local market and what that means for your plans. [kcm_ig_hashtags] => HousingMarket,HomePrices,KeepingCurrentMatters [kcm_ig_quote] => Home price growth slowed down. That may be changing. [modified] => [poll] => [public_bottom_line] =>

Home price growth slowed way down, and now it's showing early signs of picking back up. Whether you're buying or selling, connect with a local real estate agent so you can see exactly what prices are doing in your local market and what that means for your plans.

[published_at] => 2026-07-29T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110130 [content_type] => must-share [title] => 7/29 Must Share ) ) [shares] => 0 [slug] => home-price-growth-slowed-down-that-may-be-changing [status] => published [tags] => Array ( [0] => foundations ) [title] => Home Price Growth Slowed Down. That May Be Changing. [updated_at] => 2026-07-28T18:51:24Z [url] => /2026/07/29/home-price-growth-slowed-down-that-may-be-changing/ )

Home Price Growth Slowed Down. That May Be Changing.

After more than a year of headlines talking about how home prices are going to crash, the latest data shows that price growth may be starting to pick back up again.

17
stdClass Object
(
    [agents_bottom_line] => 

If a tight budget or a thin selection has kept you from buying a home, now might be the time to restart your search.

Ready to see what’s available here? Let’s connect.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:06:50Z [id] => 320 [name] => Inventory [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:06Z [slug] => inventory [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Inventario ) ) [updated_at] => 2024-04-10T16:19:06Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

If you’ve thought about buying a home in the past few years, you may have run into two frustrations: asking prices that kept climbing and too few homes to choose from.

In many places, both sticking points are letting up this summer, with lower asking prices and more homes for sale. Let’s look at the trends, and what they mean for your search.

Sellers Are Pricing To Attract Buyers

According to Realtor.com, the national median asking price was $430,000 in June, nearly $11,000 under what it was the year before (see graph below):

a graph of sales

That’s the eighth month in a row that the typical asking price has dipped below where they were the previous year, according to the same Realtor.com report.

And while falling prices can sound worrying, this isn’t a sign of an impending crash. We’re talking about asking prices, not sold prices. This is a sign that today’s sellers are meeting the market where it is and pricing to draw buyers. And that’s actually something normal we’d expect from the market. As Danielle Hale, Chief Economist at Realtor.com, puts it:

“Sellers are reading market conditions and are pricing accordingly from the start rather than listing high and cutting later, and buyers are taking note and making bids. This is a welcome sign that we are in a functioning market.”

Asking prices were never going to climb forever – now they're just settling closer to what buyers can actually pay. That signals a healthier market, and sellers re-adjusting their expectations. 

More Homes Are Available Now

If you’ve spent the past few years watching homes disappear before you could even schedule a tour, this is for you.

Supply is starting to catch up. According to Realtor.com, the number of homes listed for sale in June was the highest June number we’ve seen in three years (see graph below):

a graph with numbers and a number of blue bars

This means more options for you and less competition for each one.

Now, supply is not back to normal everywhere. As you can see, we’re still down from where we were back in 2017-2019. But in many places, it’s better than it’s been in a while. Here’s how that helps you.

You don’t have to rush an offer just to stay in the running, and you have better odds of finding and landing the right home, not just the one that’s available. Plus, you’ll have more room to negotiate, so you’re searching from a stronger position than buyers had even a year ago.

Why This Is Encouraging if You’re Buying Your First Home

For first-time buyers looking for lower-priced homes, these trends line up especially well. Mischa Fisher, Chief Economist at Zillow, explains:

“The lowest price tiers are exhibiting some softness in terms of price, they also had the most listing-activity growth, the first time since 2022 that’s been the case.”

So, if you’re searching for your first place or your next house, there's a little more to choose from and a little more give on price.

[created_at] => 2026-07-15T16:43:40Z [description] =>

If you’ve thought about buying a home in the past few years, you may have run into two frustrations: asking prices that kept climbing and too few homes to choose from.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260715/Header-Image-GettyImages-1741416365-original.png [id] => 109785 [kcm_ig_caption] => If a tight budget or a thin selection has kept you from buying a home, now might be the time to restart your search. Ready to see what’s available here? Let’s connect. [kcm_ig_hashtags] => HomeBuying,HousingMarket,KeepingCurrentMatters [kcm_ig_quote] => More homes, better prices: A buyer’s summer. [modified] => [poll] => [public_bottom_line] =>

If a tight budget or a thin selection has kept you from buying a home, now might be the time to restart your search.

Connect with a local real estate agent to see what's available where you're looking.

[published_at] => 2026-07-20T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 109786 [content_type] => must-share [title] => 7/20 Must Share ) ) [shares] => 0 [slug] => more-homes-better-prices-a-buyers-summer [status] => published [tags] => Array ( ) [title] => More Homes, Better Prices: A Buyer’s Summer [updated_at] => 2026-07-15T16:43:40Z [url] => /2026/07/20/more-homes-better-prices-a-buyers-summer/ )

More Homes, Better Prices: A Buyer’s Summer

If you’ve thought about buying a home in the past few years, you may have run into two frustrations: asking prices that kept climbing and too few homes to choose from.

18
stdClass Object
(
    [agents_bottom_line] => 

Down payments are smaller than they’ve been in years, and that opens the door for more buyers.

And with added help from assistance programs and a little help from loved ones, you may have more ways forward than you realized. Connect with a trusted lender to talk through your options.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

Saving for a down payment can feel like the hardest part of buying a home. And with affordability as tight as it’s been lately, it’s fair to wonder how anyone manages it right now. Here’s something you may not have seen coming. 

Some people are getting their foot in the door with a smaller down payment.

According to Realtor.com, the typical buyer put down about $23,400 in early 2026 – that's around $5,000 below what was typical the year before (a 19% drop year over year). That’s the lowest down payments have been since 2021 (see graph below):

a graph of a line graph

So why are buyers putting less money down, and how can you put less down, too? Here’s your answer.

Why Down Payments Are Getting Smaller

There are a few things driving the trend:

  • Less competition between buyers. Part of it comes down to a more balanced market. With buyers facing less competition than they did a few years ago, there’s less pressure to put a big sum down just to stand out.

  • More moderate home prices. Your down payment is a percentage of the purchase price. So, as price growth cools, the amount you need to put down may change too. In a lot of markets, prices have slowed or leveled off, and some areas are even seeing slight dips. That can translate into smaller down payments.

  • Buyers opting for loans with lower down payments. More buyers are also turning to government-backed loans, like FHA and VA, which often need little or no money down. FHA loans have made up more than 24% of purchase mortgages for five straight quarters, and VA loans recently hit their highest share in over a decade, according to Mortgage Professional America.

But even a smaller down payment is still a significant chunk of cash, and saving it can be hard. So where does the rest come from? For many buyers, two things make the difference: programs built to help, and a hand from loved ones.

Help You May Not Know You Qualify For

Down payment assistance is one of the most overlooked tools out there. Looking at the 10 largest U.S. metros, Urban Institute and Down Payment Resource found nearly 44% of recent buyers already qualified for a down payment program, but many of them closed on their loan without tapping the help (see chart below):

a diagram of a payment

The options are broader than you might assume, too. According to Down Payment Resource:

  • There are more than 2,600 down payment assistance programs available

  • More than half (62%) are designed to help first-time buyers

  • 38% have no first-time buyer requirement, so you may qualify even if you've owned before

  • 62% are open to buyers earning $100,000 or more

A Boost from Loved Ones

For a growing number of buyers, help comes from closer to home. Research from Veterans United shows about 59% of parents have provided or plan to provide financial support to help their child buy a home.

That support most often goes toward the down payment, followed by help qualifying for a mortgage and covering closing costs. Chris Birk, VP of Mortgage Insight at Veterans United, puts it this way:

“For many families, helping a child buy a home has become less of an optional gesture and more of a practical response to today’s affordability challenges.”

If your loved ones are in a position to help, it can make a real difference in how soon you can buy.

[created_at] => 2026-06-30T17:41:58Z [description] =>

Saving for a down payment can feel like the hardest part of buying a home.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260630/Header-Image-GettyImages-1492289682-original.png [id] => 109379 [kcm_ig_caption] => Down payments are smaller than they’ve been in years, and that opens the door for more buyers. And with added help from assistance programs and a little help from loved ones, you may have more ways forward than you realized. Connect with a trusted lender to talk through your options. [kcm_ig_hashtags] => FirstTimeBuyer,DownPayment,KeepingCurrentMatters [kcm_ig_quote] => Down payments are smaller than they’ve been since 2021. [modified] => [poll] => [public_bottom_line] =>

Down payments are smaller than they’ve been in years, and that opens the door for more buyers.

And with added help from assistance programs and a little help from loved ones, you may have more ways forward than you realized. Connect with a trusted lender to talk through your options.

[published_at] => 2026-07-02T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 109380 [content_type] => must-share [title] => 7/2 Must Share ) ) [shares] => 0 [slug] => down-payments-are-smaller-than-theyve-been-since-2021 [status] => published [tags] => Array ( ) [title] => Down Payments Are Smaller Than They’ve Been Since 2021 [updated_at] => 2026-06-30T17:41:58Z [url] => /2026/07/02/down-payments-are-smaller-than-theyve-been-since-2021/ )

Down Payments Are Smaller Than They’ve Been Since 2021

Saving for a down payment can feel like the hardest part of buying a home.

19
stdClass Object
(
    [agents_bottom_line] => 

When it comes to prices, where you are matters more than ever right now, and a local real estate agent is the best person to help you make sense of it.

Reach out today and let's build a plan that fits our market.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:06:50Z [id] => 320 [name] => Inventory [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:06Z [slug] => inventory [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Inventario ) ) [updated_at] => 2024-04-10T16:19:06Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) ) [content_type] => blog [contents] =>

You've probably heard that home prices are cooling off. And that's true – nationally. But zoom in on individual markets across the country, and the picture looks completely different depending on where you are.

Some areas are still seeing solid price growth. Others have gone flat. A few have actually dipped slightly negative. So, what's causing all of that variation? 

It All Comes Down to Inventory

Here's the simple version:

  1. When there are more homes for sale, buyers have options.

  2. More options, means less competition.

  3. Less competition means sellers can't push prices as high.

On the flip side, when inventory is tight, buyers are competing over a small pool of homes, and that pushes prices up.

That dynamic is playing out right now in a really visible way across the country. 

Markets where inventory has climbed back to, or above, normal pre-pandemic levels are seeing prices flatten or fall slightly. Markets where inventory is still well below those 2019 benchmarks are still seeing prices rise. As Lance Lambert, CEO of ResiClub, puts it:

"Home prices are still climbing a little year-over-year in many regions where active inventory remains well below pre-pandemic 2019 levels, such as pockets of the Northeast and Midwest.

In contrast, some pockets in states like Texas, Florida, and Colorado — where active inventory exceeds pre-pandemic 2019 levels by a solid clip — are seeing modest home price pullbacks or flat pricing."

The Maps Say It All 

Take a look at where inventory stands today compared to 2019. In most places (the states in gray below), inventory still falls short of where we were back then. And that’s exactly why prices are climbing, albeit moderately, in the vast majority of states.

But you’re probably more interested in where prices are falling a bit, since that’s what is making headlines. So, let’s prove out how much inventory affects prices in those spots.

According to Realtor.com, 15 states and Washington, D.C. are now back above pre-pandemic inventory levels, and some by a wide margin (see the orange in the map below):

a map of the united statesNow, let’s look at the latest Federal Housing Finance Agency (FHFA) data to see what's happened to home prices in those same states over the past year (again, you’ll want to focus on the orange in the next map). 
See how those line up pretty closely with the areas seeing more homes for sale today?

The overlap isn't a coincidence. It's cause and effect. 

a map of the united states

The national average of 1.7% price growth is accurate, but it's an average of two very different stories happening at the same time – the few areas experiencing mild declines and the overwhelming majority that are still seeing prices rise.

What This Means If You’re Buying or Selling 

If you're a buyer, the market you're shopping in matters a lot right now. In places like Texas, Colorado, or Florida, you may have real negotiating power – more choices, less competition, and sellers who are more motivated to make a deal. In tighter markets like much of the Northeast, you're still likely facing a lot of competition.

If you're a seller, pricing strategy is everything. In markets where inventory has risen, overpricing is one of the fastest ways to linger on the market and eventually sell for less than you would have with the right price from day one. In markets where inventory is still low, you're in a strong spot, but getting your price right still matters if you want to attract serious buyers quickly. Either way, that's where a local real estate agent earns their keep.

[created_at] => 2026-06-25T17:03:09Z [description] =>

You've probably heard that home prices are cooling off.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260625/Header-Image-GettyImages-2213672932-original.png [id] => 109220 [kcm_ig_caption] => When it comes to prices, where you are matters more than ever right now, and a local real estate agent is the best person to help you make sense of it. Reach out today and let's build a plan that fits our market. [kcm_ig_hashtags] => HomePrices,HousingInventory,KeepingCurrentMatters [kcm_ig_quote] => The 1 factor that explains everything happening with home prices right now. [modified] => [poll] => [public_bottom_line] =>

When it comes to prices, where you are matters more than ever right now, and a local real estate agent is the best person to help you make sense of it.

Reach out to a local real estate agent today and work together to build a plan that fits your market.

[published_at] => 2026-06-29T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 109221 [content_type] => must-share [title] => 6/29 Must Share ) ) [shares] => 0 [slug] => the-1-factor-that-explains-everything-happening-with-home-prices-right-now [status] => published [tags] => Array ( ) [title] => The 1 Factor That Explains Everything Happening with Home Prices Right Now [updated_at] => 2026-06-25T17:03:09Z [url] => /2026/06/29/the-1-factor-that-explains-everything-happening-with-home-prices-right-now/ )

The 1 Factor That Explains Everything Happening with Home Prices Right Now

You've probably heard that home prices are cooling off.

20
stdClass Object
(
    [agents_bottom_line] => 

If your house didn’t sell the first time, you’re not stuck. You just need a different strategy, and maybe a different partner.

When you're ready for a fresh set of eyes on what happened and what to change first, let’s connect.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:16:32Z [id] => 321 [name] => Agent Value [parent] => [parent_id] => [published_at] => 2024-04-10T16:17:42Z [slug] => agent-value [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Valor del agente ) ) [updated_at] => 2024-04-10T16:17:42Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2025-10-30T18:12:44Z [id] => 339 [name] => Expired/Withdrawn/Canceled [parent] => [parent_id] => [published_at] => 2025-10-30T18:12:44Z [slug] => expiredwithdrawncanceled [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => ) ) [updated_at] => 2025-10-30T18:12:44Z ) ) [content_type] => blog [contents] =>

When your house doesn’t sell, it’s not just disappointing. It messes with your timing. Your plans. Your confidence. You start second-guessing everything, including the decision to move in the first place. And that raises 2 big questions: 

Do you try again?

Is that even worth it?

Here’s the secret to getting a better outcome the second time around.

Different Agent. Different Results.

Most sellers who re-list and ultimately sell don’t wait for market to magically change. They change their approach. And there’s data to back that up.

Research from REDX shows homeowners who put their house back on the market with a different agent are more likely to sell than homeowners who re-used the same agent. Not to mention, they see their homes sell faster (see graph below): 

a screenshot of a graph

That’s the power of a fresh set of eyes. Because in a moment like this, the worst thing you can do is rerun the same set of plays and expect a different outcome. A different agent can bring a new perspective on where things went off track – and a lot of the time, one of these things happened.

1. The Asking Price Didn’t Match Buyer Reality

There’s a saying that’s especially important in today’s market, and it’s: “if your price isn’t compelling, it’s not selling.” Maybe that’s what happened with your house.

With mortgage rates where they are and inflation driving up the cost of everyday purchases, buyers have less room to stretch. If they feel like your house is priced even a little high, it’s going to get skipped over. And if no one looks at it, it's not going to sell.

The Fix: Price to draw buyers in, not push them away. Have an agent pull fresh data from recent sales so your asking price matches what buyers are actually paying right now. 

2. The First Impression Didn’t Win the Click 

Most buyers decide whether they want to tour a home in seconds. If the photos look dark, or dated, they scroll right past. And while you may think: “If they just saw it in person, they’d get it,” you may not get that chance.

And honestly, even in person, small things can quietly kill momentum – worn down paint, outdated fixtures, clutter, or a yard that feels high-maintenance. Individually, they’re small. Stacked together, they create doubt.

The Fix: Walk the house like you’re a buyer, not the owner. Start with what’s easy and obvious – paint, lighting, curb appeal, decluttering. Then update the photos so they match the best version of your house.

3. The Marketing Was Too “Set It and Forget It”

Today, the number of homes for sale has grown in many areas. Buyers have more options, which means your house needs a plan to stand out. A generic description and a basic upload to the MLS can blend in fast.

The Fix: Find an agent who can build stronger exposure through digital marketing and social platforms, plus content that makes buyers stop – strong photos, a smart description, a video walk-through, and a plan for open houses and follow-up.

4. There Was No Clear Plan for Feedback

Sometimes the house gets showings, but no offers. If that was your experience, it actually tells you something important. Buyers liked it enough online to come see it. So, something else was holding them back.

Those buyers were sending a message. It just wasn’t translated into action. 

The Fix: Make sure your agent has a clear plan for seeking out and acting on feedback quickly. That dialogue often points to the one change that would get a house sold.

5. The Deal Couldn’t Get Over the Finish Line 

Even when a house is priced well and marketed right, deals fall apart when there’s no plan for the human side of the transaction.

Buyers today are more likely to ask for repairs, credits, or help with closing costs than a few years ago. In this type of market, being unwilling to negotiate can cost you more than a reasonable concession ever would.

The Fix: Decide ahead of time what matters most to you and where you can be flexible. Keep the dialogue open and lean on your agent for advice.

[created_at] => 2026-06-23T20:38:30Z [description] =>

When your house doesn’t sell, it’s not just disappointing. It messes with your timing. Your plans. Your confidence.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260623/Header-Image-GettyImages-1448385933-original.png [id] => 109144 [kcm_ig_caption] => If your house didn’t sell the first time, you’re not stuck. You just need a different strategy, and maybe a different partner. When you're ready for a fresh set of eyes on what happened and what to change first, let’s connect. [kcm_ig_hashtags] => ExpiredListing,SellYourHouse,KeepingCurrentMatters [kcm_ig_quote] => Your house didn’t sell. Here’s how to turn it around. [modified] => [poll] => [public_bottom_line] =>

If your house didn’t sell the first time, you’re not stuck. You just need a different strategy, and maybe a different partner.

When you're ready for a fresh set of eyes on what happened and what to change first, connect with a local agent.

[published_at] => 2026-06-25T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 109147 [content_type] => must-share [title] => 6/25 Must Share ) ) [shares] => 0 [slug] => your-house-didnt-sell-heres-how-to-turn-it-around [status] => published [tags] => Array ( ) [title] => Your House Didn’t Sell. Here’s How To Turn It Around. [updated_at] => 2026-06-23T20:38:30Z [url] => /2026/06/25/your-house-didnt-sell-heres-how-to-turn-it-around/ )

Your House Didn’t Sell. Here’s How To Turn It Around.

When your house doesn’t sell, it’s not just disappointing. It messes with your timing. Your plans. Your confidence.

21
stdClass Object
(
    [agents_bottom_line] => 

If affordability has been your top concern, the recent dip in prices is an opening. Want to see what that looks like in our area? Let’s connect.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

If affordability has been the biggest thing standing between you and a home, there's a little good news. 

Asking prices have started to come down.

The typical seller listed their house for a median of $429,500 in May. That’s 2.4% lower than a year ago, according to Realtor.com. On its own, that won't transform what you can afford, but in today’s market every little bit helps and it signals a broader shift taking place.

Buyers Are Finally Catching a Break

Check out this data from Realtor.com and you can see this is the first May in years where buyers have caught any sort of break price-wise.

Each May from 2022-2025, things held pretty steady. But this year? You can see that more noticeable shift in your favor (see graph below):

a graph of sales in different colors

While the dip from $440,000 to $429,500 isn’t a big one, it gives you more breathing room. And that’s not a small thing when affordability has been this tough.

Now, lower asking prices don’t mean every home is suddenly within your range. But they do show buyers are gaining a little ground.

And in today’s market, a little ground can go a long way. 

What That Means for the Housing Market

And just in case this crossed your mind, this is good news for your move, not bad news for the market as a whole.

The subtle dip from last May to this one shows prices are easing, but they’re not dropping off a cliff. What this is actually a sign of is that the market’s rebalancing now that the number of homes for sale has grown.

Buyers have a bit more power again, and sellers know they can't name just any price and expect their house to sell. They either meet the market where it is, or face a price cut later. And in general, sellers would rather avoid a price cut. As the New York Post explains:

"Rather than swinging for the fences with pandemic-era price tags, sellers are increasingly coming to terms with a new reality. The share of listings featuring price cuts actually fell to 17.5% in May, suggesting homeowners are doing their homework before putting up a “For Sale” sign instead of chasing unrealistic numbers and cutting later."

This signals a broader change in the market.

Seller expectations have been skewed a little high since the pandemic buying frenzy – you've probably felt that firsthand. But now, things are starting to normalize. It could mean less back-and-forth to land on a fair number. And homes should be priced a bit more realistically from the start.

[created_at] => 2026-06-09T06:25:03Z [description] =>

If affordability has been the biggest thing standing between you and a home, there's a little good news.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260609/Header-Image-GettyImages-83802508-original.png [id] => 108772 [kcm_ig_caption] => If affordability has been your top concern, the recent dip in prices is an opening. Want to see what that looks like in our area? Let’s connect. [kcm_ig_hashtags] => Homebuying,HomePrices,KeepingCurrentMatters [kcm_ig_quote] => Lower asking prices are a win for today’s buyers. [modified] => [poll] => [public_bottom_line] =>

If affordability has been your top concern, the recent dip in prices is an opening. Connect with a local real estate agent to see what that looks like in your area.

[published_at] => 2026-06-10T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 108773 [content_type] => must-share [title] => 6/10 Must Share ) ) [shares] => 0 [slug] => lower-asking-prices-are-a-win-for-todays-buyers [status] => published [tags] => Array ( [0] => foundations ) [title] => Lower Asking Prices Are a Win for Today’s Buyers [updated_at] => 2026-06-09T06:25:03Z [url] => /2026/06/10/lower-asking-prices-are-a-win-for-todays-buyers/ )

Lower Asking Prices Are a Win for Today’s Buyers

If affordability has been the biggest thing standing between you and a home, there's a little good news.

22
stdClass Object
(
    [agents_bottom_line] => 

Inflation is still above where the Fed wants it, and that means mortgage rates are likely to stay elevated for a while. But for people who need to move, strategy matters far more than trying to perfectly time the market.

Wondering what this means for your specific situation? Reach out today. Let's cut through the noise together and make a plan that actually works for you.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:20:58Z [id] => 325 [name] => Economy [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:04Z [slug] => economy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Economía ) ) [updated_at] => 2024-04-10T16:21:04Z ) ) [content_type] => blog [contents] =>

Data shows inflation is moving in the wrong direction. But before the headlines send anyone into a panic, here's what's actually going on, why it matters for the housing market, and what it means if you're thinking about buying or selling.

Inflation Went Up – Here’s What That Actually Means

The government tracks inflation in a variety of ways. One is something called PCE – the Personal Consumption Expenditures Price Index. It measures how much more (or less) people are paying for goods and services compared to a year ago. And just based on your own expenses, you can probably guess which way that’s trending.

That’s the one everyone is talking about right now. Check out the yellow line to see how that’s spiked since February (see graph below). A big driver of this jump is the ongoing conflict in the Middle East, which has pushed gas and energy prices significantly higher.

a graph with blue and yellow lines

Now, you may have noticed there’s a second line. The blue line shows core PCE. That’s the same measure, but with gas and energy prices stripped out. The Federal Reserve (the Fed) actually watches this number most closely because energy prices swing around a lot and can be misleading.

And here’s the somewhat encouraging part.

Core PCE is rising, but not nearly as fast as the overall number. That suggests a good chunk of the inflation spike we’re seeing right now is tied directly to what’s happening overseas. So, when that situation settles down, inflation may settle a bit, too.

Why This Matters for Mortgage Rates

Here's the housing connection. When inflation is high, the Fed tends to keep the Federal Funds Rate elevated or even raise it to try to taper spending and cool inflation back down. And while it's not a one-for-one relationship, that Federal Funds Rate can have an impact on your mortgage rate when you buy. 

Right now, based on the information we have, there's roughly a 50/50 chance the Fed actually raises the Federal Funds Rate before the end of 2026, according to CME FedWatch (see graph below):

a graph of blue squares

While it’s too soon to say where this goes for certain and if we’re headed for a rate hike, it does mean mortgage rates are probably not coming down as soon as most people were hoping.

If you've been waiting for rates to drop significantly before making a move, this report is a reminder that "higher for longer" is still very much on the table. It really all depends on where the economy goes from here. According to Bankrate:

“Oil prices and bond yields have dropped a bit . . . but they're still way up compared to the start of spring. Until there’s a resolution to the war, look for both inflation and mortgage rates to stay high.”

But This Is Not 2008 – Not Even Close

Just remember, a tough economy does not equal a housing crash. The conditions today are very different from what led to the 2008 collapse. Here's why:

  • Inventory is still relatively low. There's no flood of homes hitting the market.

  • Most homeowners today have strong equity in their homes.

  • Lending standards are far stricter than they were before 2008.

  • Today's challenge is affordability, not a wave of distressed underwater sellers.

Uncomfortable and unhealthy are not the same thing. The market feels hard right now, but "hard" and "crashing" are very different.

You Still Have Options. Here’s What To Do.

High rates don't mean homeownership is out of reach. It just means the path looks a little different. There are real strategies that can help, depending on your situation:

  • Ask your lender about different loan options. Adjustable-rate mortgages (ARMs) or rate buydowns may help lower your monthly payment in the short term.

  • Explore first-time buyer programs, down payment assistance, or seller concessions that could help offset costs.

  • Stay in close touch with a trusted agent and lender. When rates shift, and they will, you’ll want to be ready to move fast.

The right strategy, tailored to your goals, matters a lot more than waiting for the perfect moment that may never come.

[created_at] => 2026-06-02T19:52:50Z [description] =>

Data shows inflation is moving in the wrong direction. But before the headlines send anyone into a panic, here's what's actually going on, why it matters for the housing market, and what it means if you're thinking about buying or selling.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260602/Header-Image-Winter-2020-Buyer-Guide-11--original.png [id] => 108579 [kcm_ig_caption] => Inflation is still above where the Fed wants it, and that means mortgage rates are likely to stay elevated for a while. But for people who need to move, strategy matters far more than trying to perfectly time the market. Wondering what this means for your specific situation? Reach out today. Let's cut through the noise together and make a plan that actually works for you. [kcm_ig_hashtags] => Inflation,MortgageRates,KeepingCurrentMatters [kcm_ig_quote] => Here's what rising inflation means for your move. [modified] => [poll] => [public_bottom_line] =>

Inflation is still above where the Fed wants it, and that means mortgage rates are likely to stay elevated for a while. But for people who need to move, strategy matters far more than trying to perfectly time the market.

Wondering what this means for your specific situation? Connect with a local agent or lender.

[published_at] => 2026-06-04T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 108582 [content_type] => must-share [title] => 6/4 Must Share ) ) [shares] => 0 [slug] => what-rising-inflation-means-for-your-move [status] => published [tags] => Array ( ) [title] => What Rising Inflation Means for Your Move [updated_at] => 2026-06-02T19:52:50Z [url] => /2026/06/04/what-rising-inflation-means-for-your-move/ )

What Rising Inflation Means for Your Move

Data shows inflation is moving in the wrong direction. But before the headlines send anyone into a panic, here's what's actually going on, why it matters for the housing market, and what it means if you're thinking about buying or selling.

23
stdClass Object
(
    [agents_bottom_line] => 

Life changes. Priorities shift. Families grow. Kids move out. Careers evolve. And eventually, the house you’re in may stop fitting the life you’re living.

If that’s been weighing on you lately, let’s talk through what your options could realistically look like today, no matter where rates or prices are.

Life can’t always wait for perfect market conditions. Maybe you don’t have to either.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:06:50Z [id] => 320 [name] => Inventory [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:06Z [slug] => inventory [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Inventario ) ) [updated_at] => 2024-04-10T16:19:06Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) ) [content_type] => blog [contents] =>

You may be telling yourself you’re going to wait to move – maybe you’re hoping mortgage rates will come down, prices will fall, or the market will feel a little easier.

And honestly? A lot of people feel that way right now. But here’s what some are starting to realize.

Waiting doesn’t usually fix the thing that made you want to move in the first place.

Your family still desperately needs more room. Your empty nest still feels too...empty.

Your parents or grandparents still need you to live closer.

You just got married... or divorced.

Your vision of retirement has you living somewhere else.

Eventually, life can reach a point where waiting feels harder than moving.

That’s why some people are still deciding to buy right now, even in today’s market. Not because conditions are perfect. But because the life changes behind their move never really went away.

And maybe that’s exactly where you are too. If so, you’re certainly not alone.

The Real Reasons People Move 

Data from the National Association of Realtors (NAR) shows 1 in 5 buyers last year said they felt like they had to purchase a home at that time, no matter the market.

That's an important reminder right now. Sure, the dollars and cents of your move have to make sense for you. But big life changes happen whether mortgage rates and home prices are high, low, or somewhere in between. 

And those big life events happen more than you may think. NAR says roughly 22.5 million people experience major life changes in a typical two-year span (see graph below):

a graph of blue rectangular objects

These are exactly the kinds of things that can change how much space you need, where you want to live, or what kind of lifestyle makes sense now. Chen Zhao, Head of Economics Research at Redfin, explains:

“Life doesn’t stand still—people get new jobs, grow their families, downsize after retirement, or simply want to live in a different neighborhood.”

And that’s what makes waiting so hard. Every month you spend hoping the market changes is another month living in a house that no longer works for your life. It’s stressful to feel stuck. And that feeling usually doesn’t disappear.

There May Be More Opportunity Than You Think

But while affordability is still a challenge, there may still be a way for you to make your move.

The number of homes for sale has been growing for 4 straight years (see graph below). That means more homes to choose from and, in some markets, more room to negotiate than buyers had just a few years ago. 

a graph of growth of a straight year

That doesn’t mean moving is suddenly easy. But it does mean some buyers are finding ways to make a move work. So, if you’ve been putting your plans on hold, maybe the question isn’t just:

“What’s the market doing?” or “When will it get better?”

Maybe ask yourself this, too: “Can I still live where I'm at right now and make it work?”

If the answer to that second question is “no,” it may be worth having a conversation about what your options look like today – despite where rates or prices are. You could find your move is still possible after all. With more homes for sale, there’s a better chance to find one that fits your life (and your budget) right now.

[created_at] => 2026-05-26T16:23:13Z [description] =>

You may be telling yourself you’re going to wait to move – maybe you’re hoping mortgage rates will come down, prices will fall, or the market will feel a little easier.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260526/Header-Image-GettyImages-2160571794-original.png [id] => 108286 [kcm_ig_caption] => Life changes. Priorities shift. Families grow. Kids move out. Careers evolve. And eventually, the house you’re in may stop fitting the life you’re living. If that’s been weighing on you lately, let’s talk through what your options could realistically look like today, no matter where rates or prices are. Life can’t always wait for perfect market conditions. Maybe you don’t have to either. [kcm_ig_hashtags] => MakeMeMove,ReasonsToMove,KeepingCurrentMatters [kcm_ig_quote] => Here's the real reason some people are still moving right now. [modified] => [public_bottom_line] =>

Life changes. Priorities shift. Families grow. Kids move out. Careers evolve. And eventually, the house you’re in may stop fitting the life you’re living.

If that’s been weighing on you lately, talk to an agent about what your options could realistically look like today, no matter where rates or prices are.

Life can’t always wait for perfect market conditions. Maybe you don’t have to either.

[published_at] => 2026-05-28T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 108293 [content_type] => must-share [title] => 5/28 Must Share ) ) [shares] => 0 [slug] => the-real-reason-some-people-are-still-moving-right-now [status] => published [tags] => Array ( ) [title] => The Real Reason Some People Are Still Moving Right Now [updated_at] => 2026-05-26T16:23:13Z [url] => /2026/05/28/the-real-reason-some-people-are-still-moving-right-now/ )

The Real Reason Some People Are Still Moving Right Now

You may be telling yourself you’re going to wait to move – maybe you’re hoping mortgage rates will come down, prices will fall, or the market will feel a little easier.

24
stdClass Object
(
    [agents_bottom_line] => 

Yes, rates have been volatile, and global instability is keeping them from settling down anytime soon. There’s no sugar coating that. But the full picture of affordability is more nuanced than the headlines suggest.

Want to run the real numbers for your situation? Let's talk. Reach out and let's set up a quick, no-pressure conversation.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:20:58Z [id] => 325 [name] => Economy [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:04Z [slug] => economy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Economía ) ) [updated_at] => 2024-04-10T16:21:04Z ) ) [content_type] => blog [contents] =>

Let's be real with each other for a second about affordability. Because you deserve someone who will be honest and transparent about what’s going on, especially if you’ve got a move on your mind.

Here’s the full picture of what’s happening and why. The good – and the bad. So, you know what it truly means for your move. Because while rates are certainly a big part of affordability, they’re not the only factor at play.

Mortgage Rates Have Been Rising

After a year or more of rates trending down, they’ve started to climb again. And, if you’re looking to buy, that’s not what you want to see. But it has happened. And here’s why.

Uncertainty is the enemy of mortgage rates.

And with lingering global uncertainty, ongoing tensions in the Middle East, and inflation refusing to fully cool off, there’s a lot that’s having an effect on rates. Colin Robertson, Founder of The Truth About Mortgage, put it plainly:

"You can't have $100 a barrel oil and not expect inflation to rise, which translates to higher bond yields and mortgage rates."

Take a look at the graph below. It uses data from Mortgage News Daily to show just how much all of those factors have had an impact:

a graph with a line and a green arrowIt’s a pretty sharp contrast from where we’ve been, in a relatively short window. And it's probably making you wonder: Should I just wait this out? Will rates fall when the uncertainty eases?
It's possible. But it all depends on how the ongoing geopolitical conflict plays out and whether inflation continues to run hot afterwards – and for how long.

Rates probably aren't heading down until both of those things improve. And even when that does happen, experts agree rates likely won’t be dramatically lower – maybe in the low to mid-6s. That's the reality, and it's worth knowing.

So, should you wait for lower rates? The general consensus is, if you can afford to buy and you find a home you like, it’s still worth it. Because no one knows for sure when rates will start to come back down – and how long do you really want to put your life on hold?

Wages Are Outpacing Home Prices

You've probably heard that inflation is making everything more expensive, and there's no shortage of headlines about the cost-of-living outpacing paychecks. It's a legitimate concern. And maybe you’re feeling the pinch yourself. But here's what doesn't make the headlines. It's not all bad news.

Data from the Federal Reserve Bank of Atlanta and Redfin shows wages have actually been growing faster than home prices.

  • Recently, wages have been increasing at around 4% year-over-year. 

  • And home price growth is closer to 2% year-over-year.

As a buyer, you want your income to rise faster than prices because that helps make your purchase more manageable financially, and it quietly chips away at the affordability challenge over time. That’s exactly what we’re seeing lately. And every little bit is going to help.

A big reason wages have been gaining ground on home prices? Home prices have actually stayed pretty steady.

Existing Home Prices Have Held Steady

Check out the graph below. It shows home price data from the National Association of Realtors (NAR) over the past 4 years. Notice anything? There's been no dramatic runup, and no crash either. Just relative stability and slow growth:

a graph of blue lines

Part of what's keeping prices this stable is that buyers finally have more choices. That means less competition, more negotiating power, and more time to find the home that actually fits your life, not just the one you had to grab before someone else did.

And that gives you a chance to hopefully find something that works for your budget, even with today’s rates. At the same time, you're not losing ground pricewise while you take time to make a careful decision.

[created_at] => 2026-05-26T15:49:40Z [description] =>

Let's be real with each other for a second about affordability.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260526/Header-Image-20220208-Blog-original.png [id] => 108281 [kcm_ig_caption] => Yes, rates have been volatile, and global instability is keeping them from settling down anytime soon. There’s no sugar coating that. But the full picture of affordability is more nuanced than the headlines suggest. Want to run the real numbers for your situation? Let's talk. Reach out and let's set up a quick, no-pressure conversation. [kcm_ig_hashtags] => MortgageRates,HomeAffordability,KeepingCurrentMatters [kcm_ig_quote] => Here's the truth about affordability today. [modified] => [public_bottom_line] =>

Yes, rates have been volatile, and global instability is keeping them from settling down anytime soon. There’s no sugarcoating that. But the full picture of affordability is more nuanced than the headlines suggest.

Want to run the real numbers for your situation? Talk with a local real estate agent. They'd love to show you what's actually possible in today's market. Reach out to set up a quick, no-pressure conversation.

[published_at] => 2026-05-27T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 108284 [content_type] => must-share [title] => 5/27 Must Share ) ) [shares] => 0 [slug] => the-truth-about-affordability-today [status] => published [tags] => Array ( [0] => foundations ) [title] => The Truth About Affordability Today [updated_at] => 2026-05-26T15:49:40Z [url] => /2026/05/27/the-truth-about-affordability-today/ )

The Truth About Affordability Today

Let's be real with each other for a second about affordability.

25
stdClass Object
(
    [agents_bottom_line] => 

Builder incentives and lower new home prices are working to your advantage in a way they haven't in years. Want to see what's available in your area and what kind of deal a builder may be willing to make? Let's connect.

[assets] => Array ( ) [banner_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260527/STM-Banner-GettyImages-1765760671-original.jpg [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 45 [name] => New Construction [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => new-construction [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Nueva construcción ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

If you’ve always assumed a newly built home is just not in your budget, you should know the math just got a little friendlier.

The median sale price of a newly built home is now at its lowest level since 2021, according to the latest data from the Census. And on top of that, builders are still rolling out incentives to bring buyers through the door.

Here's what's happening, and what it means if you're shopping right now.

Prices on Newly Built Homes Have Come Down

After a steep climb during the pandemic years, prices have eased a bit. The median sale price of newly built homes is sitting at about $390,000. That’s the lowest it's been in nearly five years (see graph below):

a graph of a home pricesWhile local markets vary, the national trend is moving in your favor, especially if you’re a first-time buyer. According to Zonda, prices in the entry-level price range have dropped roughly 2.7% over the past 12 months – more than any other price tier.

That doesn't mean every home in every market is suddenly affordable. But it does mean that, broadly, you’ll see the best prices on new builds since 2021, if you’re buying now.

Why This Isn’t a Repeat of 2008

And just in case you’re thinking it, lower prices don't mean the new home market is in trouble. Builders today are being intentional about how much inventory they have, so it doesn't pile up the way it did in 2008.

If you look back up at the graph, you’ll see that even after the recent improvement in new home prices, they’re still higher than pre-pandemic norms. So, this isn’t a crash. It’s a builder strategy to keep inventory moving.

Homebuilders Are Still Sweetening the Deal

Lower sticker prices aren't the only break buyers are getting. According to the National Association of Home Builders (NAHB), 60% of builders are currently offering some form of incentive to attract buyers. Those typically include:

  • Help with closing costs: Some builders are covering thousands of dollars in fees to reduce the upfront cost of buying.

  • Extra upgrades: Think premium finishes, appliance packages, and designer features, often added at no extra cost.

  • Mortgage rate buydowns: When the builder pays to lower your mortgage rate, which reduces your monthly payment.

  • Price cuts: Over one in three builders (36%) are cutting prices right now, averaging about 5% off list price (see graph below):

a blue and grey pie chartThat last point catches a lot of buyers off guard – most assume that builders won’t budge on price.

But builders need to move what they've built. That's a different mindset than a homeowner deciding whether to budge on price. So, you may find they’re more open to adjusting the price than you’d think. As Joel Berner, Senior Economist at Realtor.com, puts it:

". . . many existing-home sellers resort to taking down their listing instead of taking less than their desired price, but builders are more motivated to sell their inventory than owner-occupants . ."

[created_at] => 2026-05-14T05:57:35Z [description] =>

If you’ve always assumed a newly built home is just not in your budget, you should know the math just got a little friendlier.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260514/Header-Image-GettyImages-1765760671-original.png [id] => 107879 [kcm_ig_caption] => Builder incentives and lower new home prices are working to your advantage in a way they haven't in years. Want to see what's available in your area and what kind of deal a builder may be willing to make? Let's connect. [kcm_ig_hashtags] => Homebuying ,NewHome ,KeepingCurrentMatters [kcm_ig_quote] => Newly built home prices hit a 5-year low. [modified] => [poll] => [public_bottom_line] =>

Builder incentives and lower new home prices are working to your advantage in a way they haven't in years. Connect with a local real estate agent to see what's available in your area and what kind of deal a builder may be willing to make.

[published_at] => 2026-05-21T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 107880 [content_type] => must-share [title] => 5/21 Must Share ) ) [shares] => 0 [slug] => newly-built-home-prices-hit-a-5-year-low [status] => published [tags] => Array ( ) [title] => Newly Built Home Prices Hit a 5-Year Low [updated_at] => 2026-05-14T06:04:15Z [url] => /2026/05/21/newly-built-home-prices-hit-a-5-year-low/ )

Newly Built Home Prices Hit a 5-Year Low

If you’ve always assumed a newly built home is just not in your budget, you should know the math just got a little friendlier.