New Search

If you are not happy with the results below please do another search

1492 search results for: baby its cold outside infographic

1
stdClass Object
(
    [agents_bottom_line] => 

The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, let's map out a plan that works at today's rates.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:16:32Z [id] => 321 [name] => Agent Value [parent] => [parent_id] => [published_at] => 2024-04-10T16:17:42Z [slug] => agent-value [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Valor del agente ) ) [updated_at] => 2024-04-10T16:17:42Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) [6] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:20:58Z [id] => 325 [name] => Economy [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:04Z [slug] => economy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Economía ) ) [updated_at] => 2024-04-10T16:21:04Z ) [7] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) ) [content_type] => blog [contents] =>

You've probably heard the Federal Reserve (the Fed) is raising rates again. And if you're planning to buy or sell a house, you may be wondering what that means for you.

With all the headlines, it’s easy to think the Fed sets mortgage rates. That’s actually a common myth. But the Fed’s decisions can still have an impact on them.

So, where does that leave you? The next few months could get a little bumpy. But the Fed is playing the long game. And with the right plan, you can still make a move that works. Let’s break it down.

Why the Fed Is Raising Rates

It all comes back to inflation. With prices rising fast, everything is getting more expensive – and that leaves buyers with less spending power and makes homes cost more to build.

So, the Fed raises its key short-term rate (the Federal Funds Rate) to slow down inflation. And that’s where a lot of people get tripped up.

  • MYTH: The Fed controls mortgage rates.

  • REALITY: The Fed has an impact on mortgage rates, but it’s only one piece of the puzzle.

As NerdWallet explains:

“The Federal Reserve influences mortgage rates, but doesn't set them. . . Mortgage rates are influenced by many elements, including the inflation rate, the pace of job creation, and whether the economy is growing or shrinking. The Federal Reserve's monetary policy is a factor, too . . .”

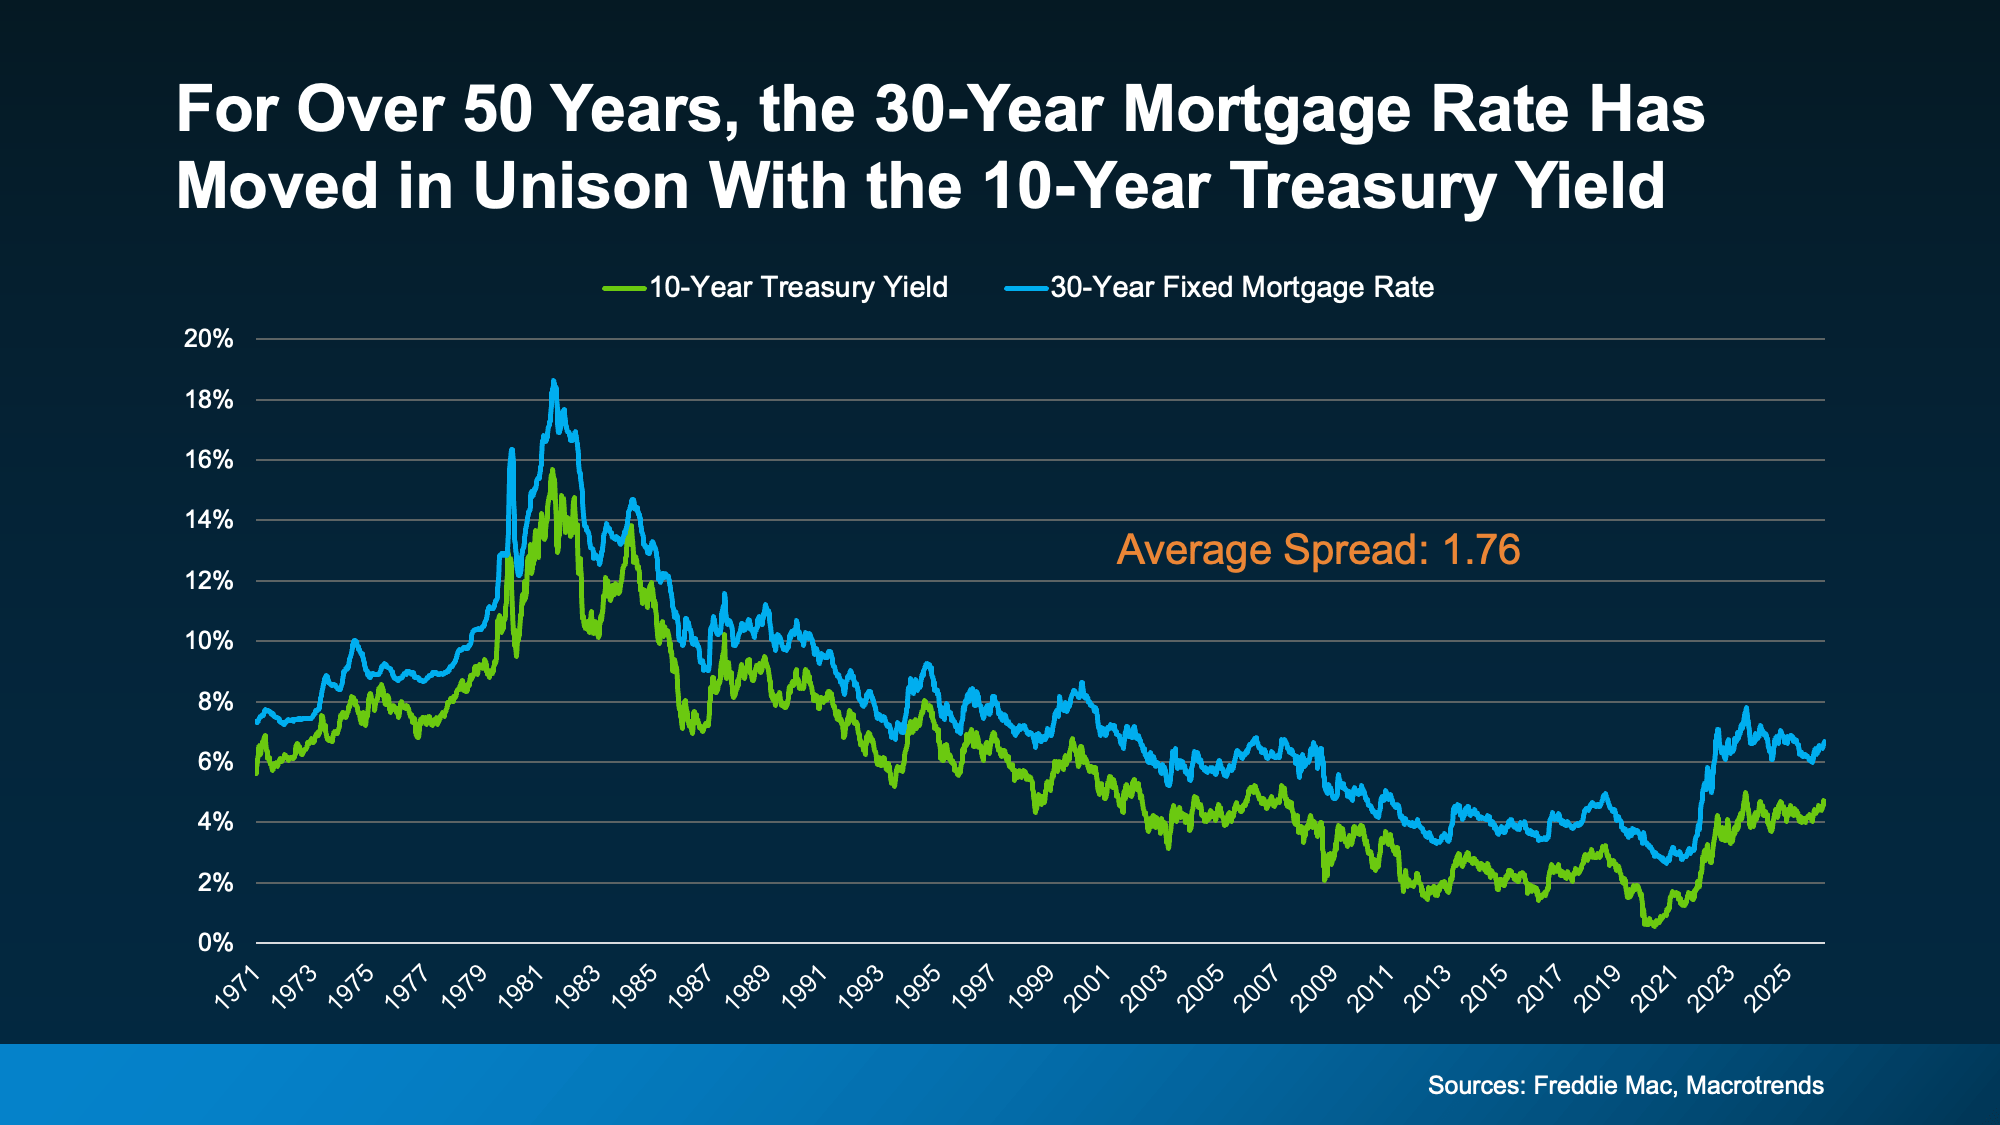
Here’s the simplest way to explain how it all fits together. Mortgage rates tend to follow something called the 10-year treasury yield. That’s the return investors get for lending money to the government for 10 years. And that yield moves up and down based on what investors expect from inflation and the economy.

Right now, one of the biggest things moving that yield is the conflict in Iran. It’s pushed oil prices higher, which has investors worried about inflation. That’s why any news about the conflict can move mortgage rates. If there’s resolution in Iran, that could take some pressure off inflation and mortgage rates. But the timing is hard to predict.

What the Fed does can move that yield, too. When they hike the Federal Funds Rate to fight inflation, investors pay attention. That can push the 10-year yield up, and mortgage rates usually follow. But once inflation cools, the yield has room to come back down, and mortgage rates can, too. That gives buyers some of their purchasing power back (see graphic below):
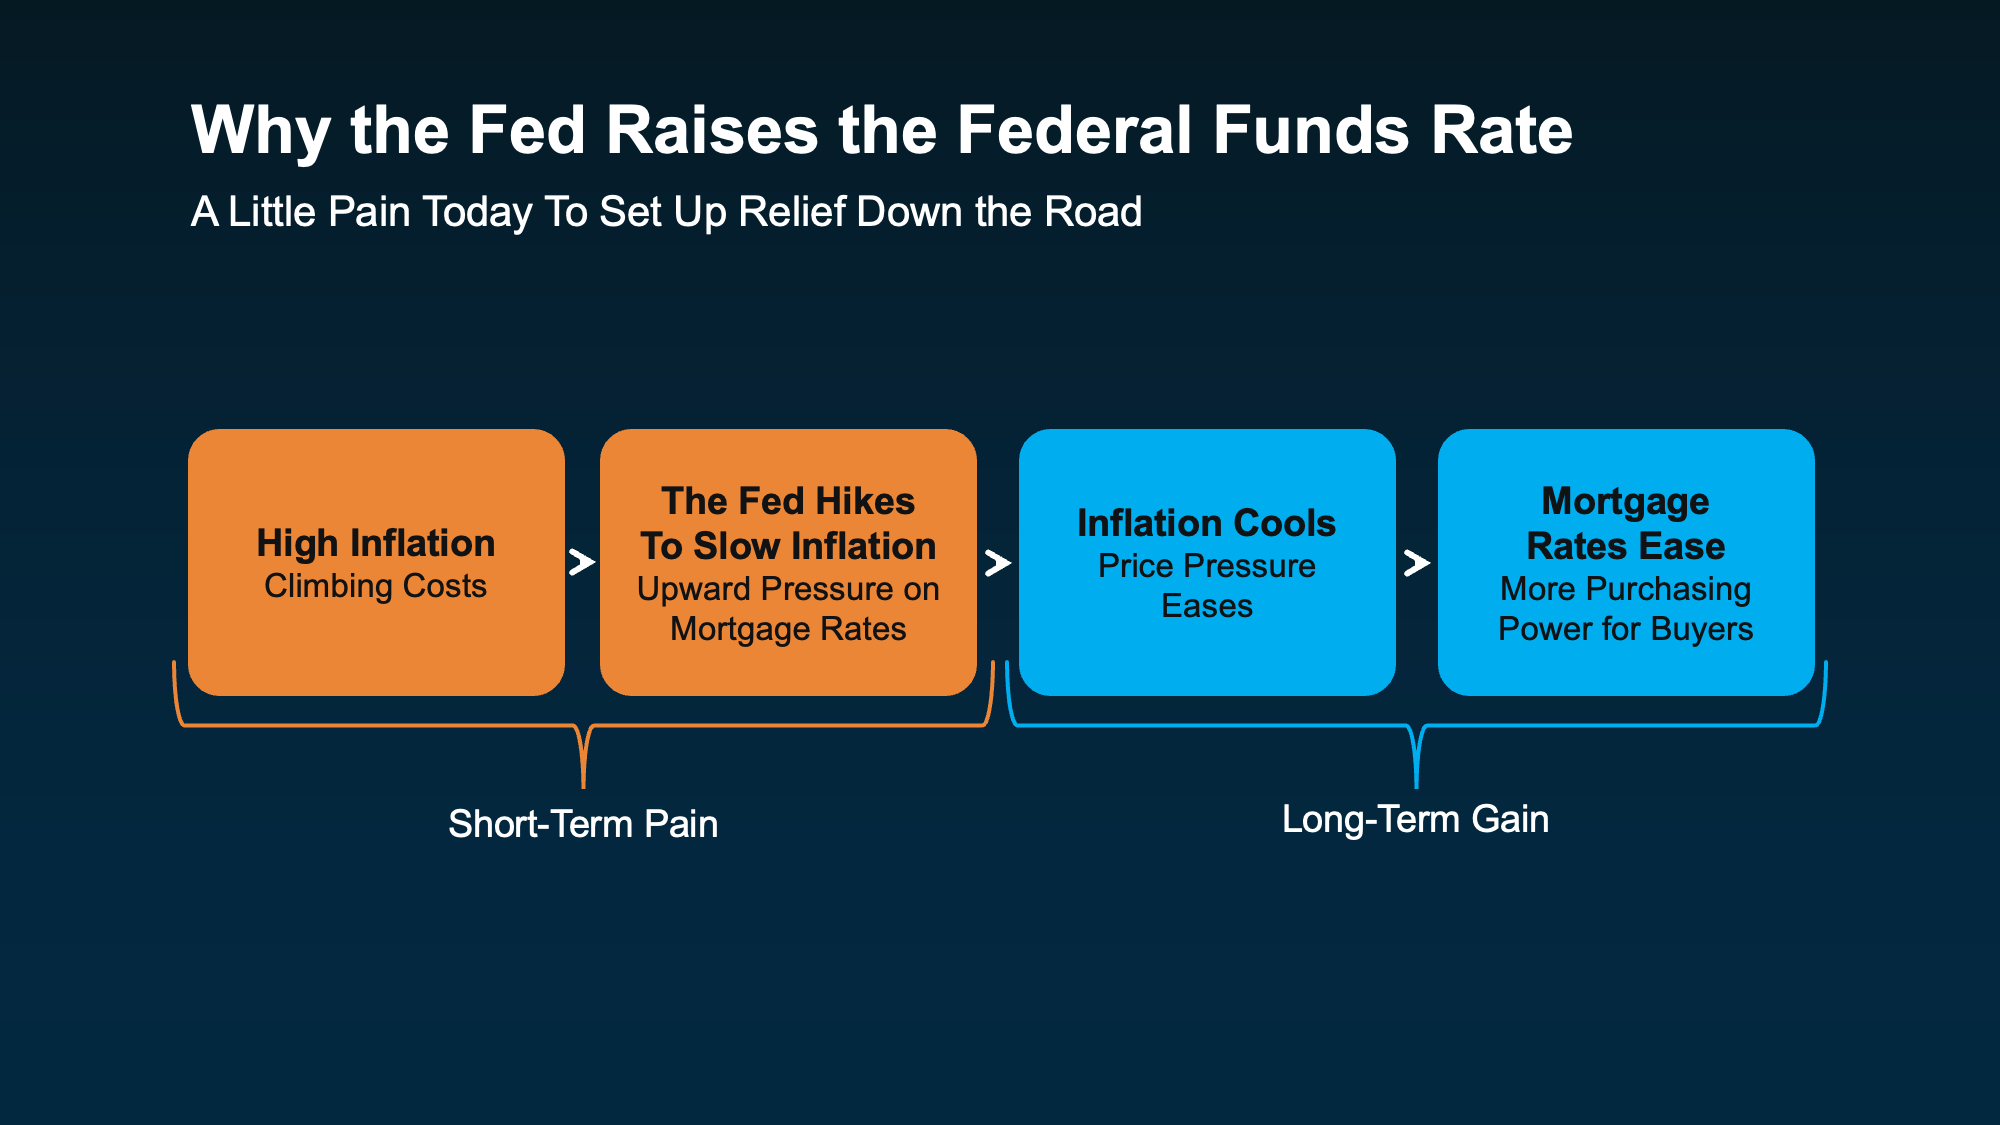
a diagram of a federal funds rate

Think of it as a little pain today to set up some relief down the road. But how long could that short-term pain last? A lot depends on what the Fed does next.

There’s a Strong Possibility the Fed Will Hike Again This Year

According to CME FedWatch, there’s over an 80% chance the Fed hikes their federal funds rate at least once more before the end of 2026 (see graph below):
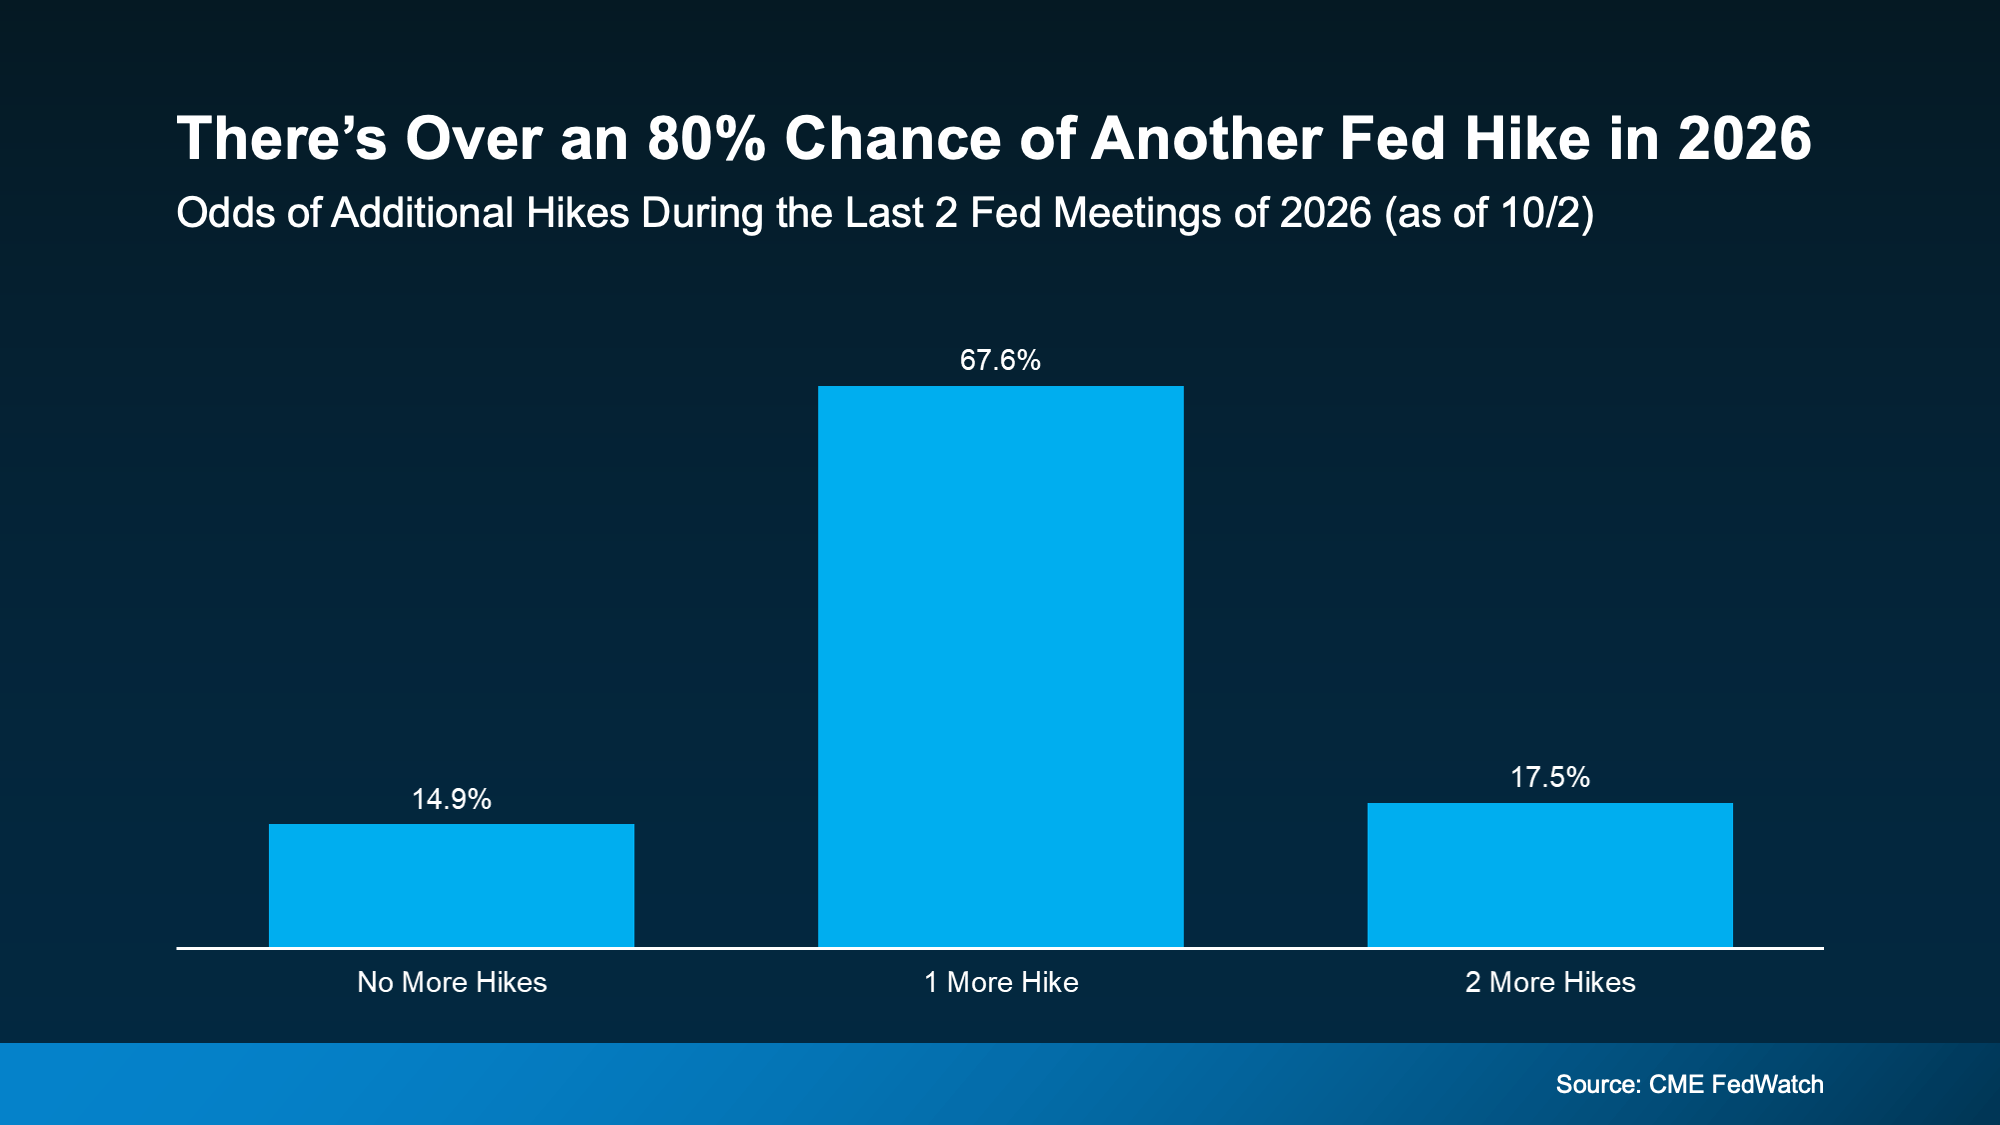
a graph of hikers with blue squares

Remember, the Fed doesn’t set mortgage rates. But another hike will likely keep upward pressure on them in the short term. So, should you wait it out? Sam Williamson, Senior Economist at First American, says this:

"Over time, firmer Fed action could help steady the bond market and open the door to lower mortgage rates, but only if investors become more confident that inflation is coming under control."

And there are some early signs that’s starting to happen. Inflation cooled faster than experts expected in August:

  • PCE inflation dropped to 3.4%, down from 3.7% in July.

  • Core PCE (the Fed’s preferred measure which leaves out food and energy prices) fell to 3%, down from 3.3%.

That’s a step in the right direction, and it’s part of why the odds of a hike at the Fed’s October meeting have come down recently. But inflation’s still above the Fed’s 2% target, and it’s been that way for about 5 years. So, lower rates could still take a while. Your best bet is a plan that works at today’s rates.

How To Make Your Move Work Right Now

While this rate hike cycle isn’t the headline you want to see, it doesn’t mean you have to wait. There are still ways to move, even now.

  • If you're buying: Get pre-approved so you know your real budget. Ask your lender about your options to get the best rate possible. And once you're under contract, lock your rate so a jump before closing doesn't raise your payment.

  • If you're selling: Decide what matters most to you – a quick sale or top dollar. Each one can call for a different plan. Price for today's buyers, whose budgets are smaller with higher rates. And think about offering a rate buydown or other concession. They can do more for a buyer’s budget than a price cut.

[created_at] => 2026-10-06T15:42:09Z [description] =>

You've probably heard the Federal Reserve (the Fed) is raising rates again. And if you're planning to buy or sell a house, you may be wondering what that means for you.
[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20261006/Header-Image-GettyImages-1804102108.png [id] => 112518 [kcm_ig_caption] => The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, let's map out a plan that works at today's rates. [kcm_ig_hashtags] => MortgageRates,HomeBuying,KeepingCurrentMatters [kcm_ig_quote] => Myth vs. Reality: Does the Fed control mortgage rates? [modified] => [poll] => [public_bottom_line] =>

The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, connect with a local real estate agent to map out a plan that works at today's rates.

[published_at] => 2026-10-07T10:30:00Z [related] => Array ( ) [related_to] => Array ( ) [shares] => 0 [slug] => myth-vs-reality-does-the-fed-control-mortgage-rates [status] => published [tags] => Array ( [0] => foundations ) [title] => Myth vs. Reality: Does the Fed Control Mortgage Rates? [updated_at] => 2026-10-06T15:42:09Z [url] => /2026/10/07/myth-vs-reality-does-the-fed-control-mortgage-rates/ )

Myth vs. Reality: Does the Fed Control Mortgage Rates?

You've probably heard the Federal Reserve (the Fed) is raising rates again. And if you're planning to buy or sell a house, you may be wondering what that means for you.
2
stdClass Object
(
    [agents_bottom_line] => 

Four different housing markets are running at once: cash buyers, financed buyers, locked-in owners, and builders. Each one plays by its own rules, and the right move for one is exactly the wrong move for another.

Let's figure out which one you're actually in and build your next move from there.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 45 [name] => New Construction [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => new-construction [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Nueva construcción ) ) [updated_at] => 2019-06-03T18:18:43Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:16:32Z [id] => 321 [name] => Agent Value [parent] => [parent_id] => [published_at] => 2024-04-10T16:17:42Z [slug] => agent-value [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Valor del agente ) ) [updated_at] => 2024-04-10T16:17:42Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) [6] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) ) [content_type] => blog [contents] =>

Today’s housing market splits into four distinct types. You’ve got cash buyers, buyers financing a purchase, owners who feel locked into a low rate, and builders with homes to sell. Which type you’re in changes how you should buy or sell. Ryan Serhant, CEO of SERHANT agrees:

“There is no longer a housing market . . . There are four Americas.”

Here’s what each looks like, and what it means for you.

Cash Buyers: 1 in 4 Buyers Are Paying with Cash

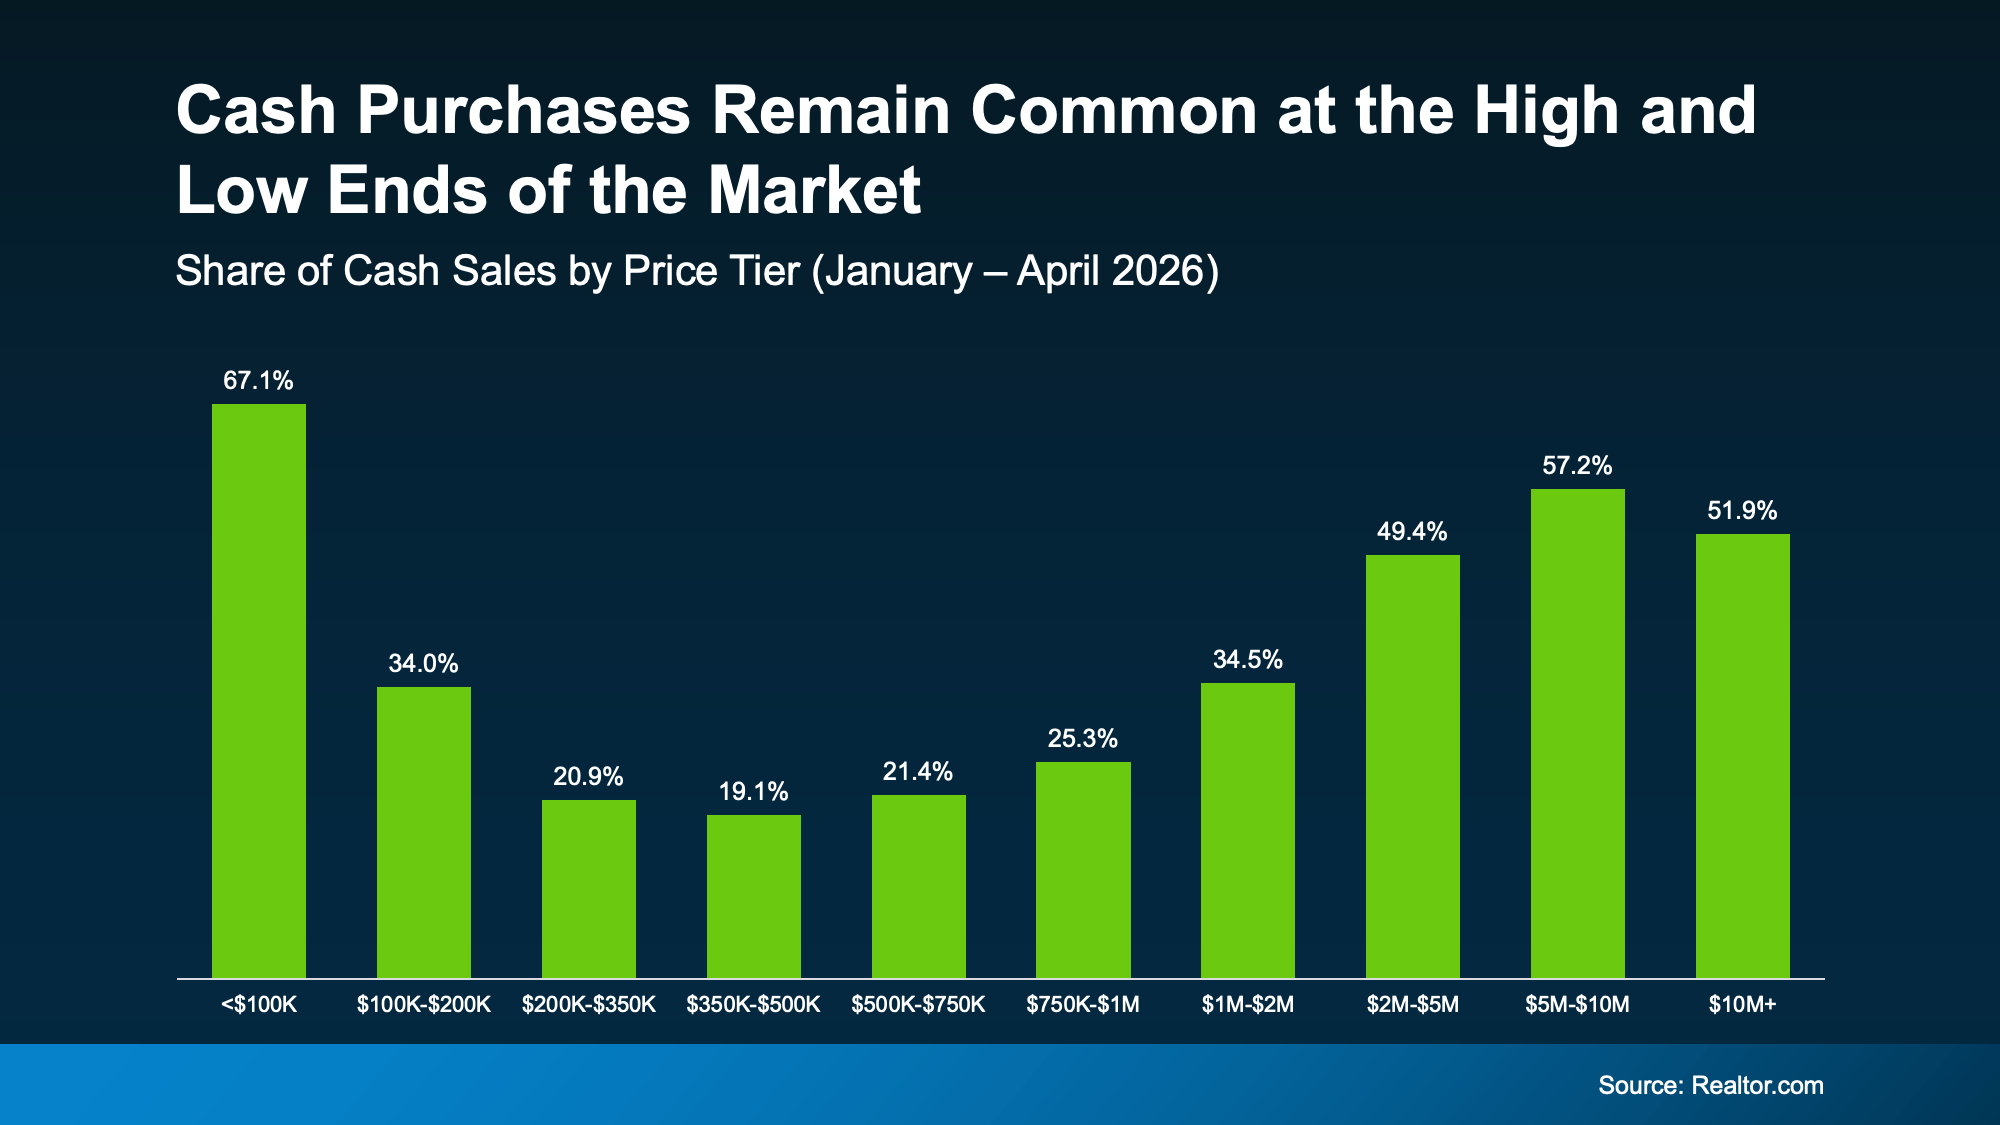
If you already own a home, you may be able to buy your next place in cash thanks to your equity. In fact, 26% of existing home sales this summer were all-cash, according to the National Association of Realtors (NAR). That's roughly 1 in 4 buyers skipping a home loan entirely.

Data from Realtor.com shows most are at the very top and very bottom of the market by price point (see graph below):

a graph of green bars

For Buyers: If you’re able to buy in cash too, having no financing contingency means your offer is going to look really appealing to sellers. You may get a faster close and more room to negotiate.

For Sellers: A cash offer can mean less risk of the deal falling through, but that certainty sometimes comes with a lower number attached. Compare the whole picture before deciding it’s automatically your best offer.

Buyers Using Financing: They’re Not Getting Help from Rates, But They Are from Sellers

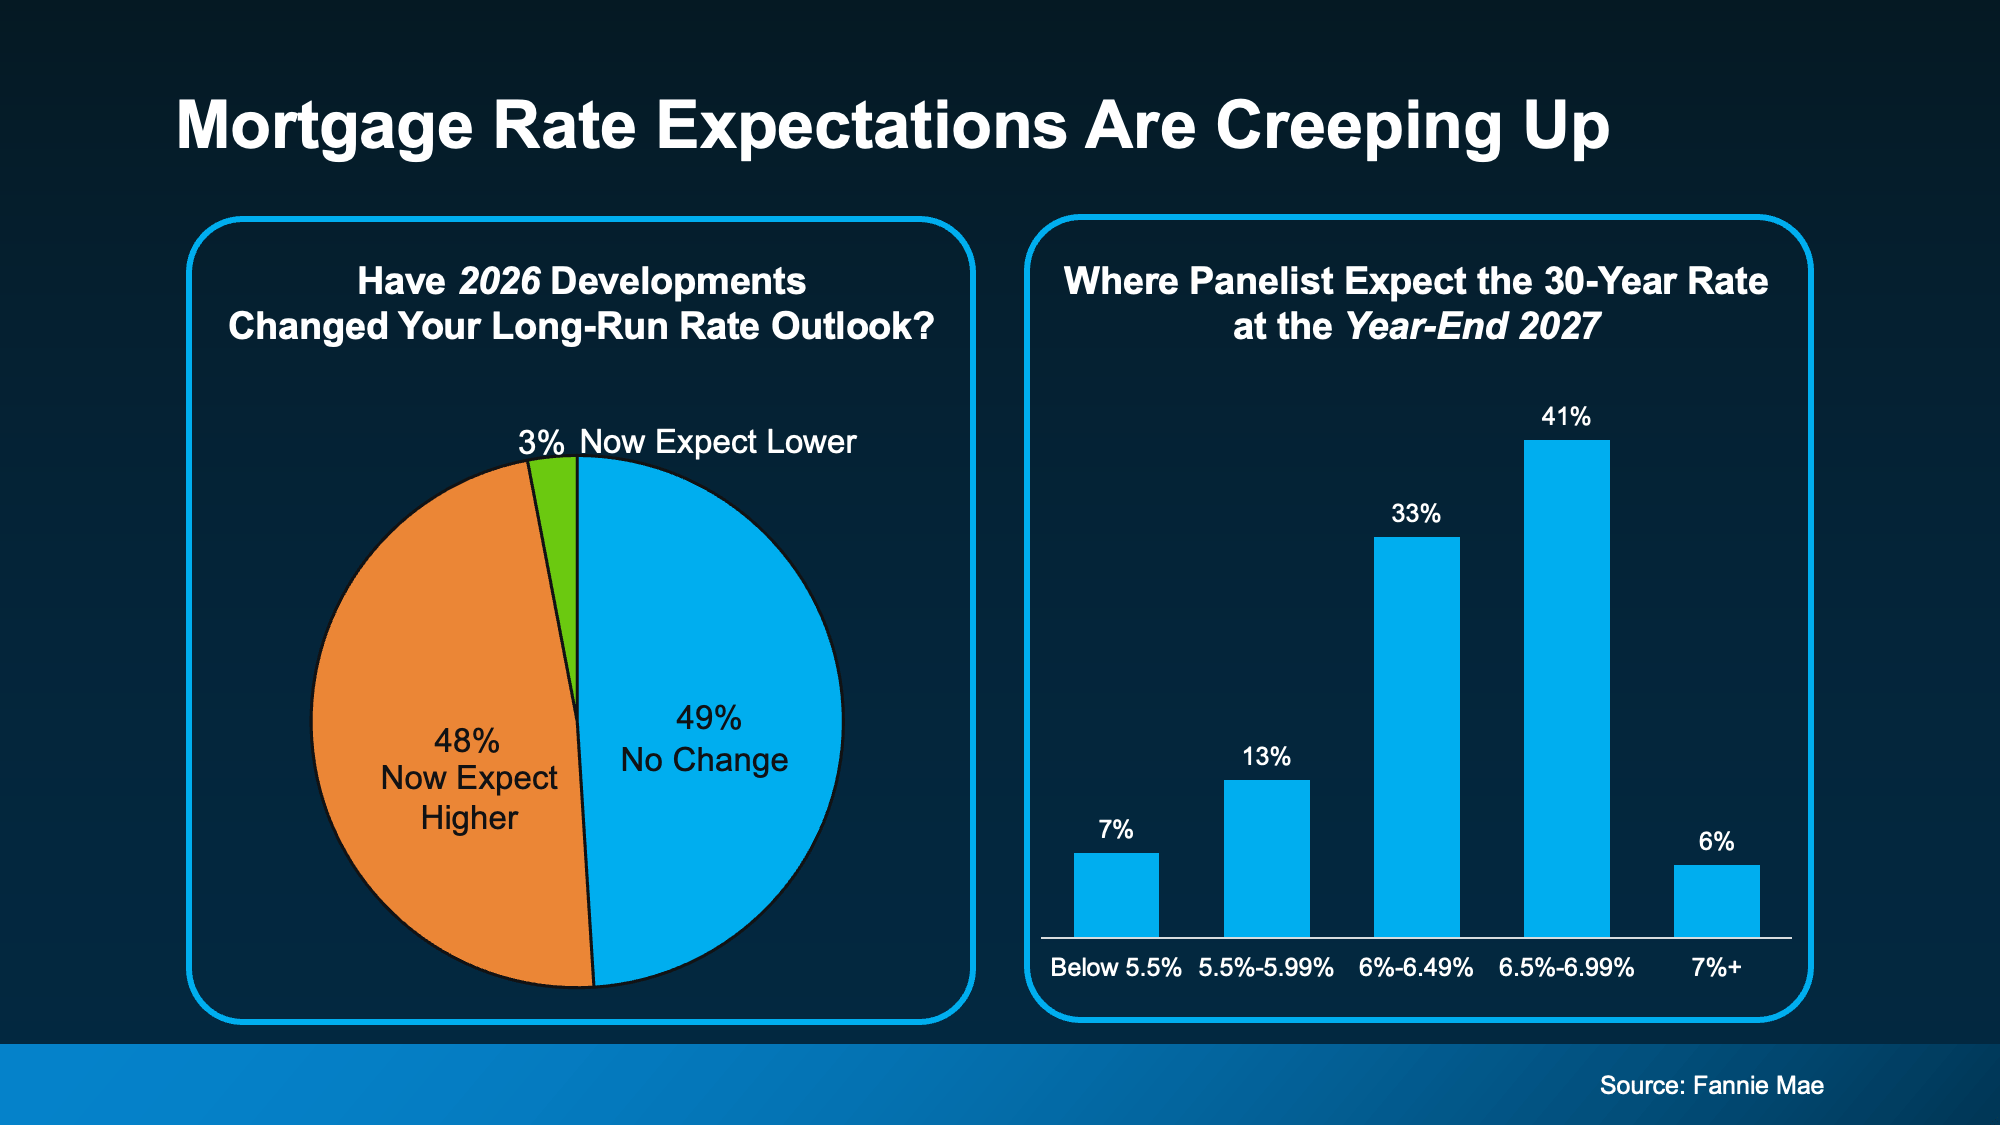
If you’re looking to take out a mortgage, you should know mortgage rates aren’t likely to come down anytime soon. Data from Fannie Mae shows nearly half of experts actually raised their long-term rate forecast this year (see graphs below):

a graph of growth and growth

That’s tough for homebuyers relying on a mortgage, especially first-time buyers. But it’s not all bad news.

While buyers may not be getting the lower rates they want, at least there’s help to be had if you ask sellers for what you really need. Redfin data shows almost half of May sales included a concession like a rate buydown or closing-cost credit from the homeowner.

For Buyers: Stop waiting on rates to drop. Negotiate the concession instead. If the payment works today, that's your signal.

For Sellers: Expect to negotiate. Build a concession into your pricing strategy from the start could be the thing that gets a deal done.

Rate-Locked Homeowners: Most Are Sitting on a Rate Below 5%

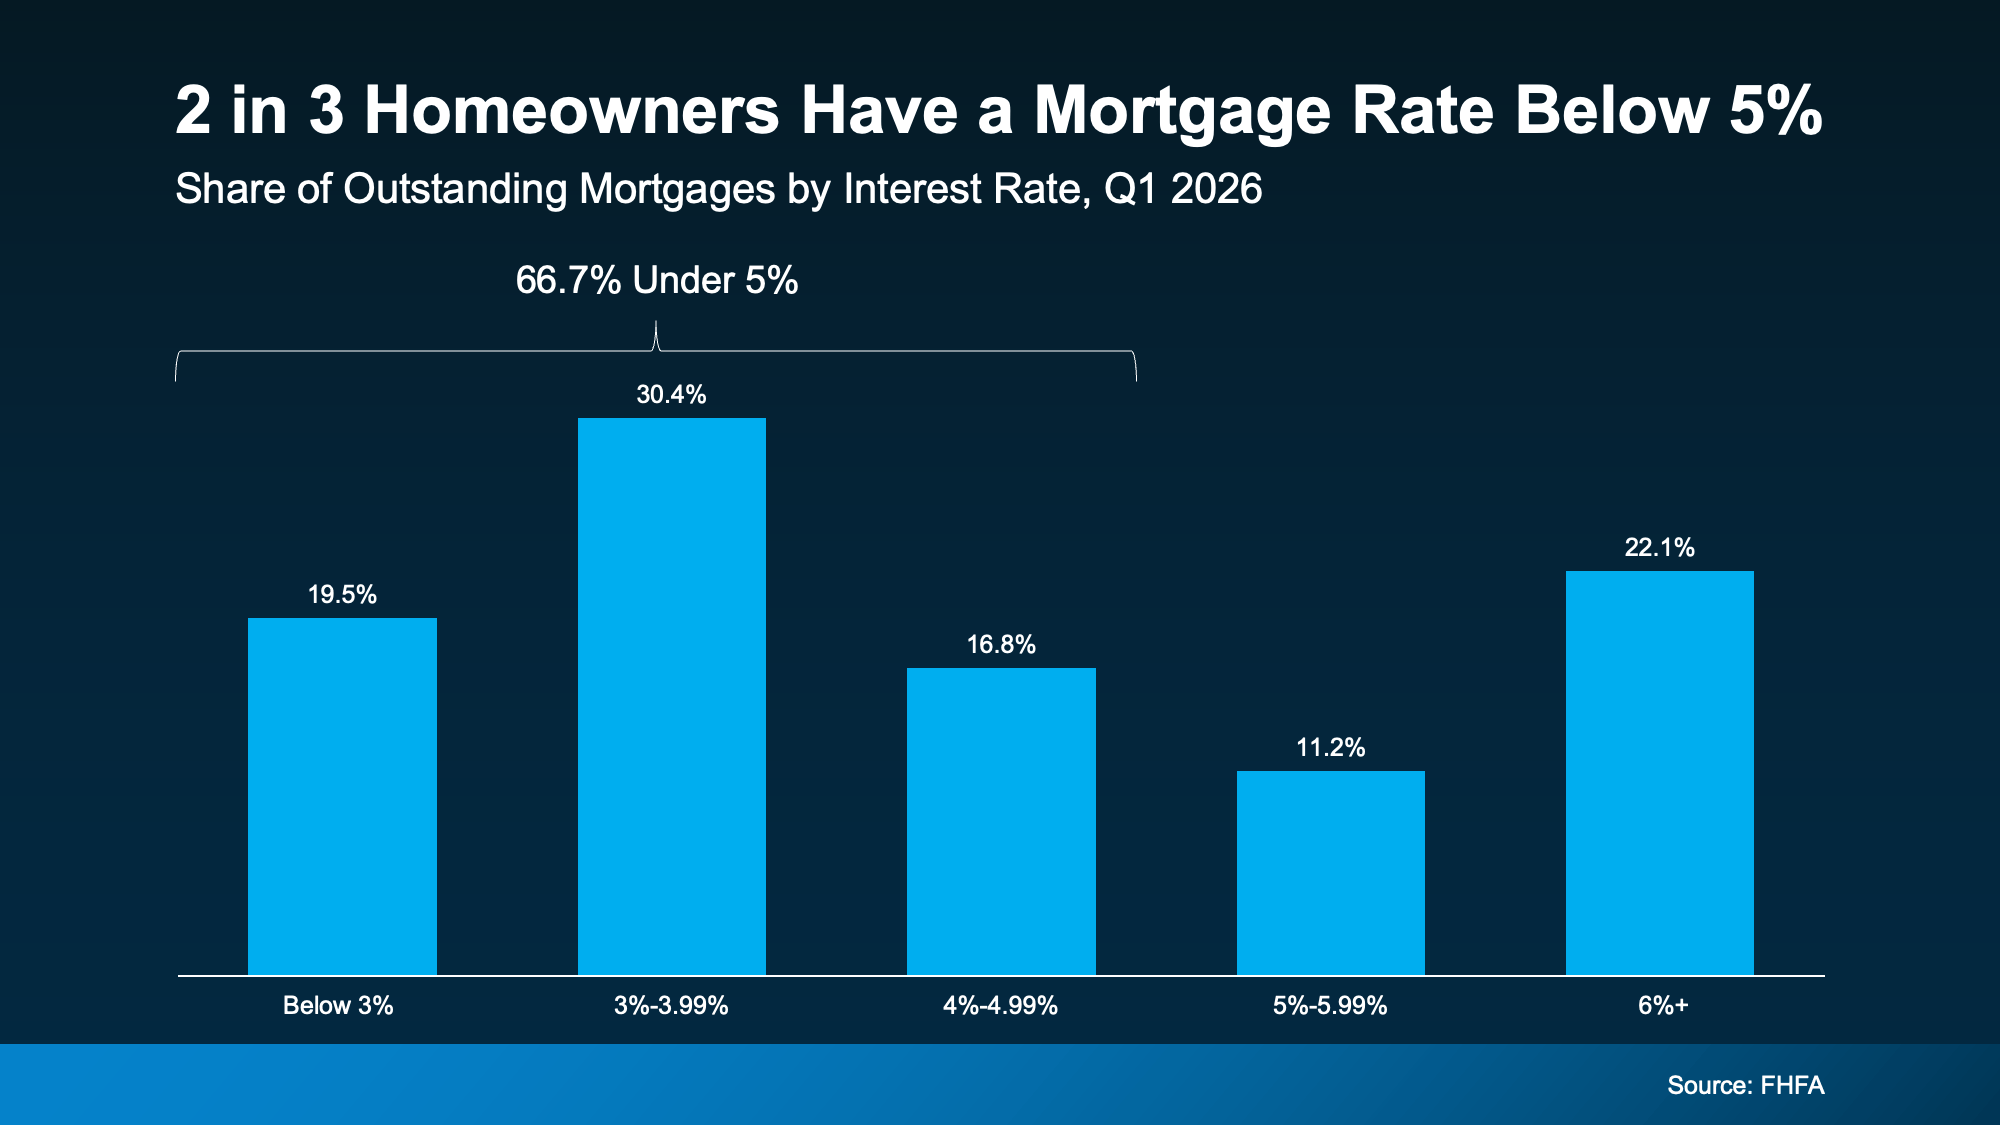
If you own a home already, you might not want to move and take on a higher rate than the one you’ve got. That’s the case for a lot of people. About 2 in 3 homeowners have a mortgage rate under 5%, according to Federal Housing Finance Agency (FHFA) data (see graph below).

When a homeowner has a rate that low, it’s harder for them to want to move and leave behind that ultra-low rate. Because, they’d likely have to take on a higher one on their next home. Hence “rate locked” – they feel locked in.

a graph of a graph with text

And, according to Fannie Mae data, most experts think that lock-in will stick around another 3-5 years. That means this will continue to be a factor in how many homes come up for sale.

For Buyers: Fewer homeowners are listing, but the ones who do usually have a real reason to move. They’re often more flexible, motivated sellers.

For Sellers: Run the math on what your equity actually buys before ruling out a move. Got an FHA or VA loan? Ask about making it assumable. It's rare, but it's a real selling point.

Homebuilders: They’re Negotiating More Than You Think

If you’re looking at new construction, this might be your moment. According to the latest Census data, builders have more unsold new homes sitting around than usual, enough that it would take nearly 10 months to sell them all at the current pace (well above the normal 4-6 months pace). That's pushing builders toward price cuts and rate buydowns.

For Buyers: That's where the deals are right now. Just be sure to use your own agent and compare the whole incentive package, not only the price tag.

For Sellers: Lead with what a builder can’t offer – mature landscaping, an established neighborhood, and a house that’s ready today, not in 8 months. That can help your house seem like a better optiona

[created_at] => 2026-09-10T20:02:24Z [description] =>

Today’s housing market splits into four distinct types. You’ve got cash buyers, buyers financing a purchase, owners who feel locked into a low rate, and builders with homes to sell.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260910/Header-Image-PULLED-20230424-Blog-original.png [id] => 111693 [kcm_ig_caption] => Four different housing markets are running at once: cash buyers, financed buyers, locked-in owners, and builders. Each one plays by its own rules, and the right move for one is exactly the wrong move for another. Let's figure out which one you're actually in and build your next move from there. [kcm_ig_hashtags] => HousingMarket,MortgageRates,KeepingCurrentMatters [kcm_ig_quote] => There are 4 types of housing markets right now. Which 1 are you in? [modified] => [poll] => [public_bottom_line] =>

Four different housing markets are running at once: cash buyers, financed buyers, locked-in owners, and builders. Each one plays by its own rules, and the right move for one is exactly the wrong move for another.

Connect with a local real estate agent to figure out which one you're actually in and build your next move from there.

[published_at] => 2026-09-23T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 111694 [content_type] => must-share [title] => 9/23 Must Share ) ) [shares] => 0 [slug] => there-are-4-types-of-housing-markets-right-now-which-1-are-you-in [status] => published [tags] => Array ( [0] => foundations ) [title] => There Are 4 Types of Housing Markets Right Now. Which 1 Are You In? [updated_at] => 2026-09-10T20:02:24Z [url] => /2026/09/23/there-are-4-types-of-housing-markets-right-now-which-1-are-you-in/ )

There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?

Today’s housing market splits into four distinct types. You’ve got cash buyers, buyers financing a purchase, owners who feel locked into a low rate, and builders with homes to sell.

3
stdClass Object
(
    [agents_bottom_line] => 

If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer.

Want help figuring out when those advantages typically show up in our market?

Let's have a quick conversation about how our market works and the steps you’ll need to take to get ready. 

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.

Yes, mortgage rates have been ticking up lately – and that’s creating some real challenges with affordability. No one’s arguing that. But there are also predictable trends that happen this time every year that can put some wind back in your sails.

According to research coming out of Realtor.com, nationally, the week of September 27 – October 3 will be the best time to buy this year for this very reason:

“The week of September 27–October 3 brings together the market conditions buyers value most—elevated inventory, less competition and prices that have eased from their seasonal high—giving prepared buyers a way to offset high rates with savings on price and room to negotiate with confidence."

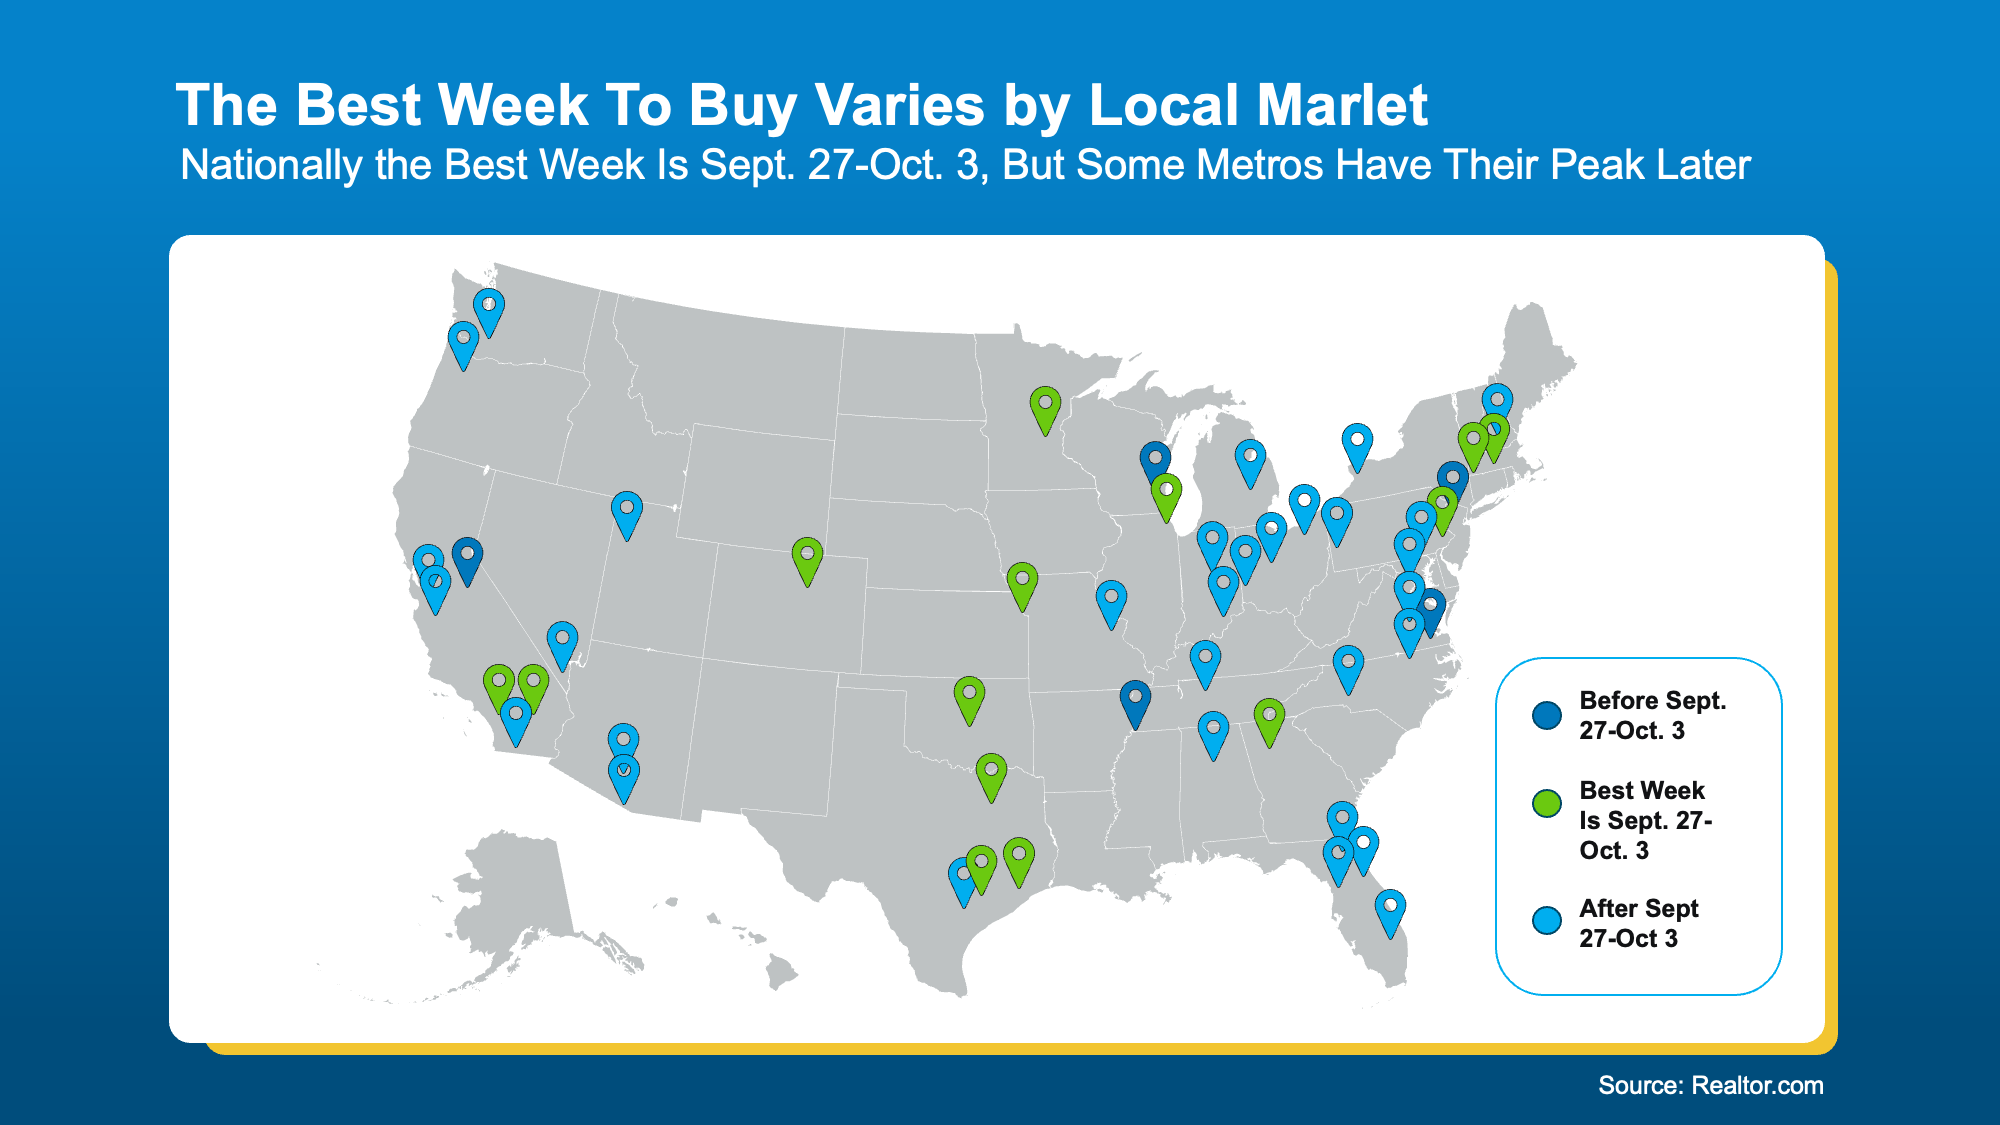
But that’s the national best week. Depending on where you live, your local sweet spot may come a little earlier or later (see map below):

a map of the united states with pins

It all depends on local trends and how inventory and buyer demand ebbs and flows seasonally where you want to live. But no matter when your market hits its peak, here are some of the perks you can expect this time of year.

More Choices, Better Prices, and Less Competition

For starters, there are more homes to choose from. In fact, data from the National Association of Realtors (NAR) shows the number of homes for sale recently reached its highest level in more than 10 years:

“NAR’s data does show a strong uptick in for-sale inventory at the end of the summer, reaching the highest level in more than 10 years.”

That means you may have a better shot at finding something you love and can afford without making as many compromises. And that’s not the only advantage.

Realtor.com says buyers during this window could see home prices about $14,000 lower than the summer peak, along with 30% less competition from other buyers. Plus, homes tend to stay on the market almost 2 weeks longer (13 days), giving you a little more breathing room to make a decision. 

  • More choices.

  • Better pricing.

  • Less competition.

That combination could be enough to ease some of the pressure higher mortgage rates are putting on your budget.

The Window Doesn’t Close After This One Week

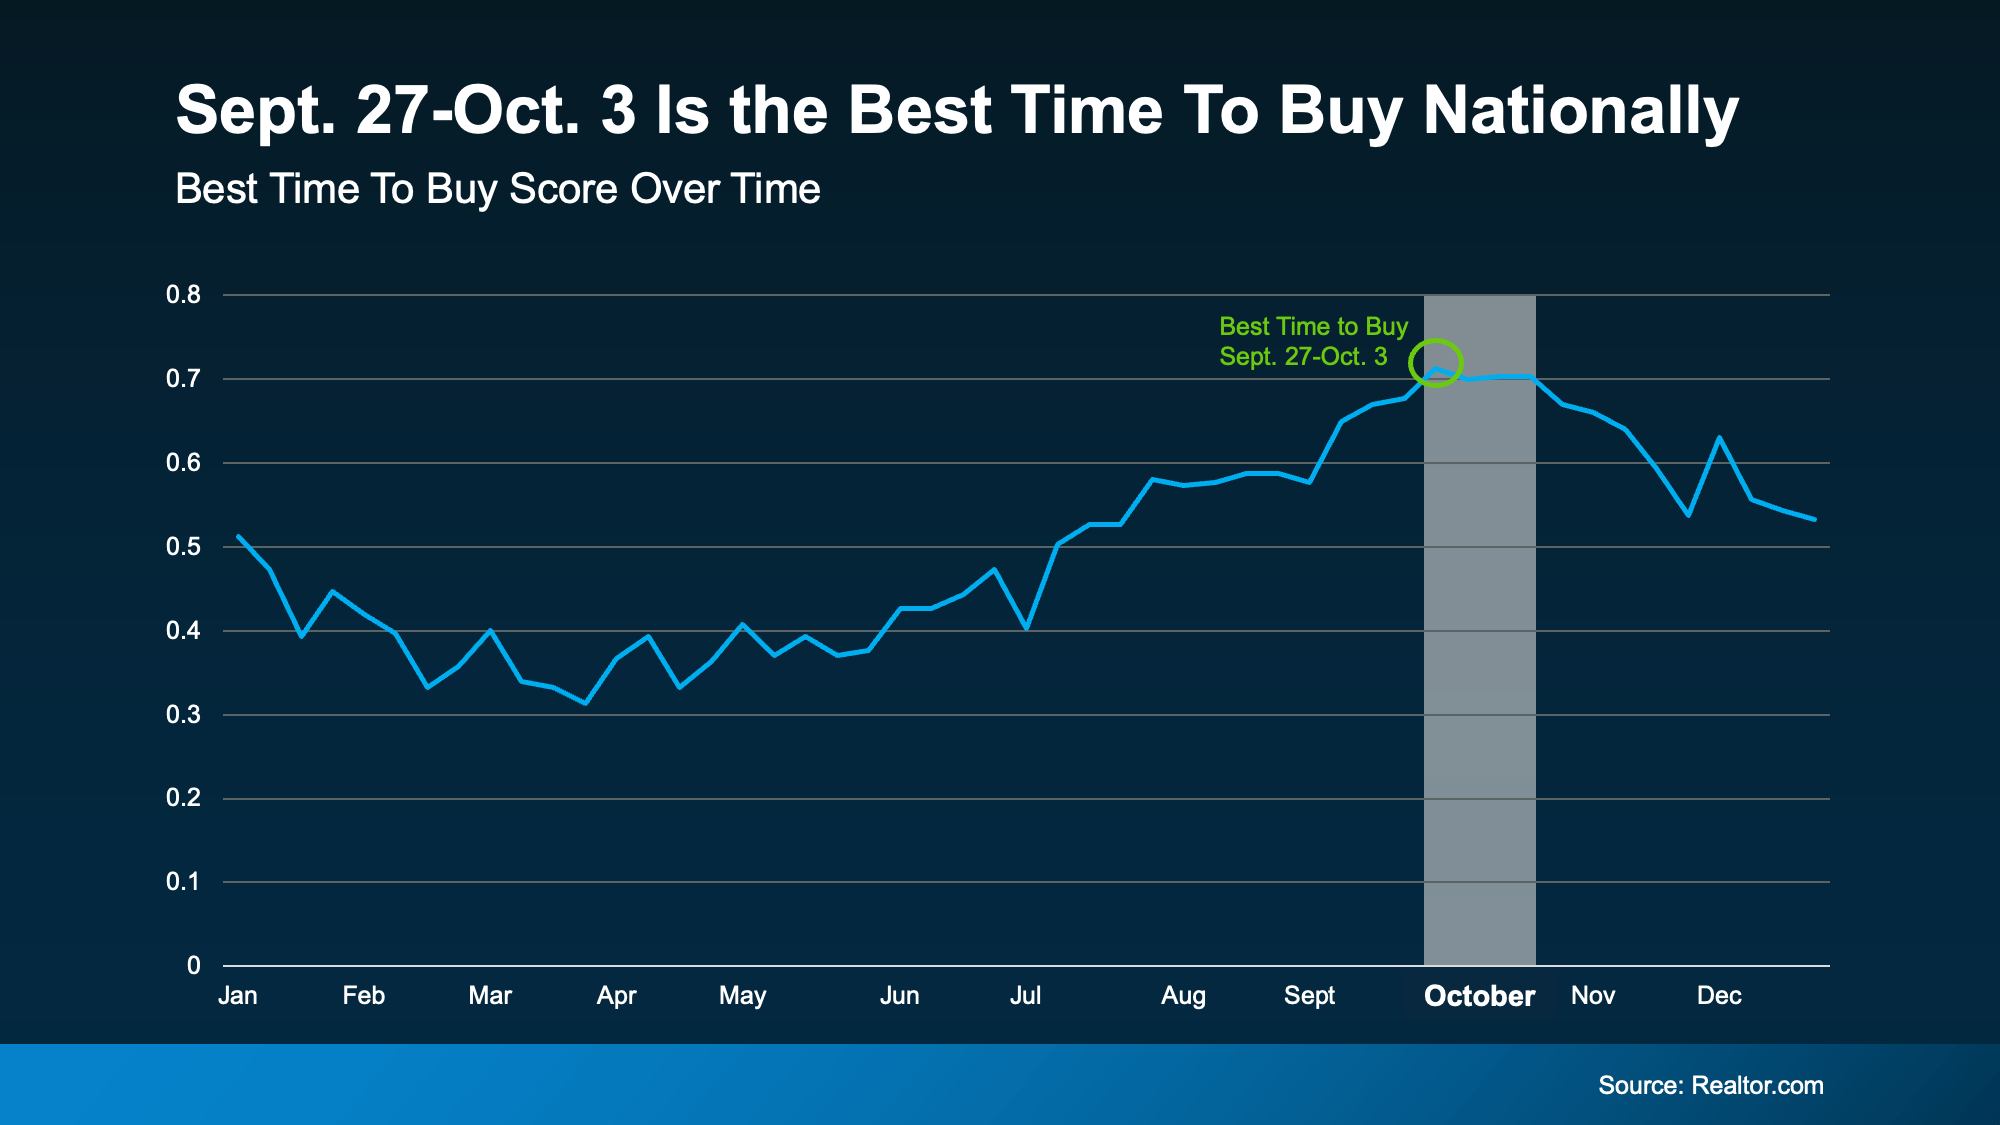
But you certainly don’t have to buy during that very specific window. This isn’t a one-week-only opportunity. History tells us conditions should be tipped in your favor for the entire month of October:

a graph on a dark background

In fact, Realtor.com says 42 of the 50 largest metros see their best week to buy fall sometime during October. So, don’t feel like you have to rush to hit one specific date. Use the time now to get things lined up, then jump in when the timing is right for you. As Guaranteed Rate explains: 

“The best time to buy a home depends on your needs. Certain seasons can give you an advantage when starting your homebuying journey.”

[created_at] => 2026-09-15T17:52:22Z [description] =>

Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260915/Header-Image-20230327-Blog-original.png [id] => 111810 [kcm_ig_caption] => If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer. Want help figuring out when those advantages typically show up in our market? Let's have a quick conversation about how our market works and the steps you’ll need to take to get ready. [kcm_ig_hashtags] => BestTimeToBuyAHome,HomebuyingTips,KeepingCurrentMatters [kcm_ig_quote] => The best time to buy a home in 2026 is almost here. [modified] => [poll] => [public_bottom_line] =>

If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer.

Want help figuring out when those advantages typically show up in your market?

Have a quick conversation with a lender and a local agent about how your market works and the steps you’ll need to take to get ready. 

[published_at] => 2026-09-16T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 111812 [content_type] => must-share [title] => 9/16 Must Share ) ) [shares] => 0 [slug] => the-best-time-to-buy-a-home-in-2026-is-almost-here [status] => published [tags] => Array ( [0] => foundations ) [title] => The Best Time To Buy a Home in 2026 Is Almost Here [updated_at] => 2026-09-15T17:52:22Z [url] => /2026/09/16/the-best-time-to-buy-a-home-in-2026-is-almost-here/ )

The Best Time To Buy a Home in 2026 Is Almost Here

Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.

4
stdClass Object
(
    [agents_bottom_line] => 

Ask yourself this: if your perfect home popped up tomorrow, would you be ready to make a move?

If the answer is no and you want to buy, it may be time to get pre-approved. You don’t feel behind before your search even officially kicks off.

[assets] => Array ( ) [can_share] => no [categories] => Array ( ) [content_type] => blog [contents] =>

Be honest. Have you started looking at homes online yet? If you have, it’s already time to get pre-approved. Because here’s what not enough people know. 

If buying a home is on your radar – even if it’s more of a someday plan than a right now plan – you don’t want to wait until later on in the process to tackle this step.

No matter what you’ve heard, pre-approval isn’t about commitment. It’s about clarity.

And here are the two big ways pre-approval sets you up for success.

You Know Your Numbers Up Front

During the pre-approval process, a lender will walk through your finances and tell you what you can borrow based on your income, debts, credit score, and more. And once you have that number, your search becomes a lot more focused.

With a mortgage pre-approval, you know what you can borrow, so it’s easier to figure out your ideal price point, and what you can actually afford. And that clarity is key.

Because if you just start browsing online and just guess at your price point, you run the risk of falling for a house that’s outside of your price range – or missing out on ones that aren’t.

You want this number to be clearly defined before your search. Here’s why.

You Can Move Quickly When You Find the One

This is how a lot of home searches go today. You scroll through listings just to see what’s out there, and then it happens. You fall in love with something you’ve seen online. 

If you’re already pre-approved? You’re probably in great shape.

But if you’re not…

Instead of being able to jump on that house and quickly make an offer, you have to scramble to get a lender, gather the financial documents, and then submit the necessary pre-approval paperwork first. And while you’re waiting to hear back from your lender, someone else who’s more prepared could beat you to the house. As Bankrate explains:

“The best time to get a mortgage preapproval is before you start looking for a home. If you find a home you love but don’t have a preapproval in hand, you likely won’t have time to get preapproved before you need to make an offer . . .”

And that’s avoidable, with the right prep. 

Because while you can’t control when the right home shows up, you can be ready for it. Think of it like showing up to the starting line with your shoes tied and your warm-up done – while everyone else is still looking for parking.

It’s not about rushing your timeline. It’s about removing the delay between finding the right home and being able to move on it.

One Thing You Need To Know About Pre-Approvals

Speaking of timing, pre-approvals do have an expiration date. So, be sure to ask your lender how long it’s good for. The Mortgage Reports explains:

“Mortgage preapproval letters are typically valid for anywhere from 30 to 90 days. However, a preapproval can be updated and extended if the lender re-checks your information.” 

Doing the right prep and knowing this information can make the whole process a lot smoother.

You don’t have to be ready to buy to be ready to buy.

Getting pre-approved doesn’t mean you’re committing to buy right now. It just means you’ve taken a step to understand your numbers. And when a home catches your attention, you’re prepped and good to go.

[created_at] => 2026-09-17T17:13:58Z [description] =>

Be honest. Have you started looking at homes online yet? If you have, it’s already time to get pre-approved. Because here’s what not enough people know.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260917/Header-Image-Spring-2021-Buyer-Guide-2--original.png [id] => 111913 [kcm_ig_caption] => Ask yourself this: if your perfect home popped up tomorrow, would you be ready to make a move? If the answer is no and you want to buy, it may be time to get pre-approved. You don’t feel behind before your search even officially kicks off. [kcm_ig_quote] => Don’t wait until you find a house to do this. [modified] => [poll] => [public_bottom_line] =>

Ask yourself this: if your perfect home popped up tomorrow, would you be ready to make a move?

If the answer is no and you want to buy, it may be time to get pre-approved. You don’t feel behind before your search even officially kicks off.

[published_at] => 2026-08-31T10:30:00Z [related] => Array ( ) [related_to] => Array ( ) [shares] => 0 [slug] => dont-wait-until-you-find-a-house-to-do-this [status] => published [tags] => Array ( ) [title] => Don’t Wait Until You Find a House To Do This [updated_at] => 2026-09-17T17:13:58Z [url] => /2026/08/31/dont-wait-until-you-find-a-house-to-do-this/ )

Don’t Wait Until You Find a House To Do This

Be honest. Have you started looking at homes online yet? If you have, it’s already time to get pre-approved. Because here’s what not enough people know.

5
stdClass Object
(
    [agents_bottom_line] => 

If you're not finding a home you love, the new home market is buzzing with opportunity. With record-high incentives, price cuts in play, and builders itching to move inventory, this is the best time in years to buy new construction.

Curious how far today’s incentives could stretch your budget? Let’s connect so you can see what builders are offering in our area.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 38 [name] => Move-Up [parent] => [parent_id] => [published_at] => 2024-04-10T16:00:35Z [slug] => move-up [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de casa mas grande ) ) [updated_at] => 2024-04-10T16:00:35Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 45 [name] => New Construction [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => new-construction [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Nueva construcción ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

Even with more homes on the market right now, some buyers are still having a tough time finding the right one at the right price. Maybe the layout feels off. Maybe it still needs some updating. Or maybe it’s just more of the same.

That’s why more buyers are turning to new construction – and finding some of the best deals available today.

Why? Today, many builders have more homes that are finished and sitting on the market than normal. And that means they’re motivated to sell. They’re running a business, and they don’t want to sit on their inventory. They want to sell it before they build more homes. And that can definitely work in your favor. 

As Lance Lambert, Co-Founder of ResiClub, puts it: 

“In housing markets where unsold completed inventory has built up, many homebuilders have pulled back on their spec builds—and many are doing bigger incentives or outright price cuts to move unsold inventory.”

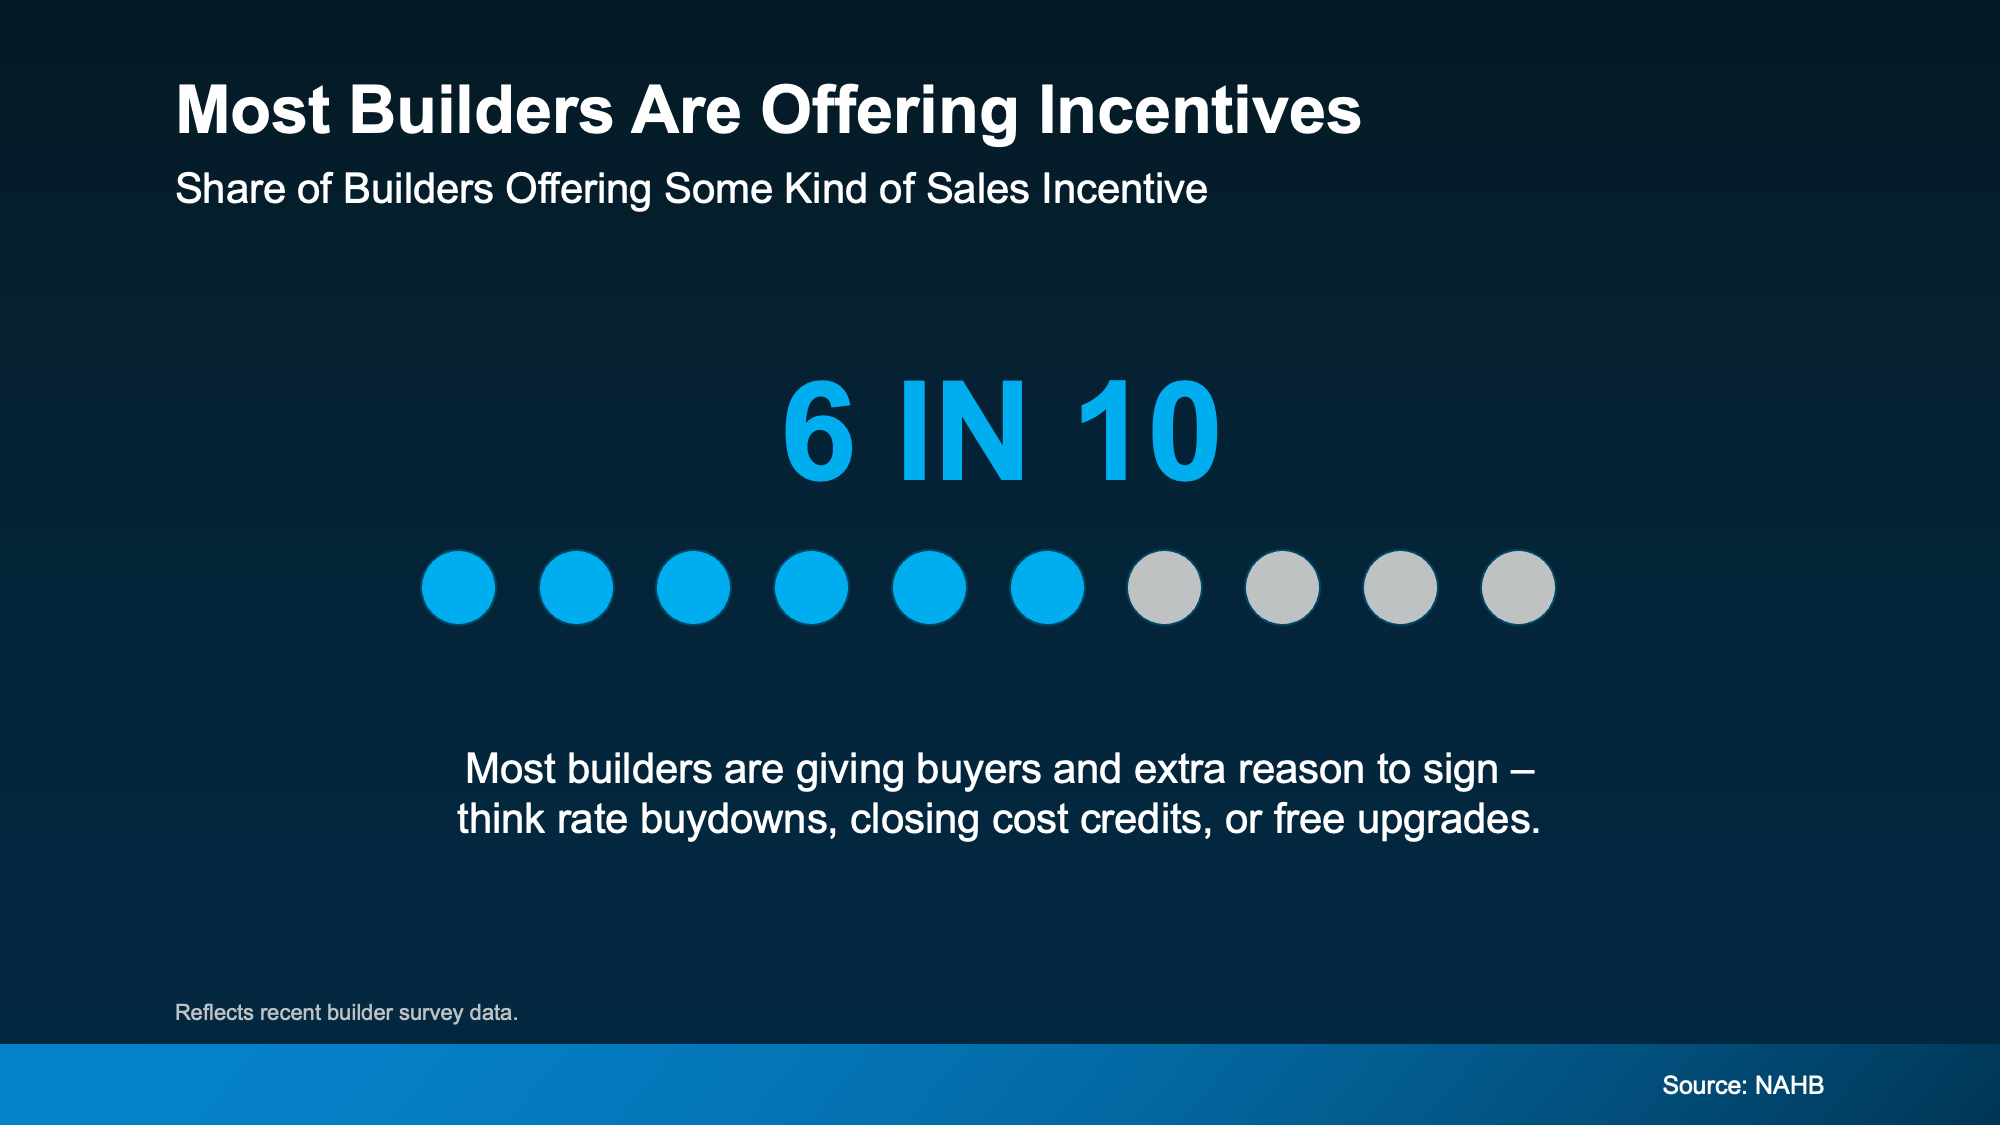
Over Half of Builders Are Offering Incentives 

Survey data from the National Association of Home Builders (NAHB) shows 6 in 10 builders are offering sales incentives.

a blue and grey dot with white text

That means most builders are throwing in something extra to get deals done. And when builders do that, it’s the buyers like you who win.

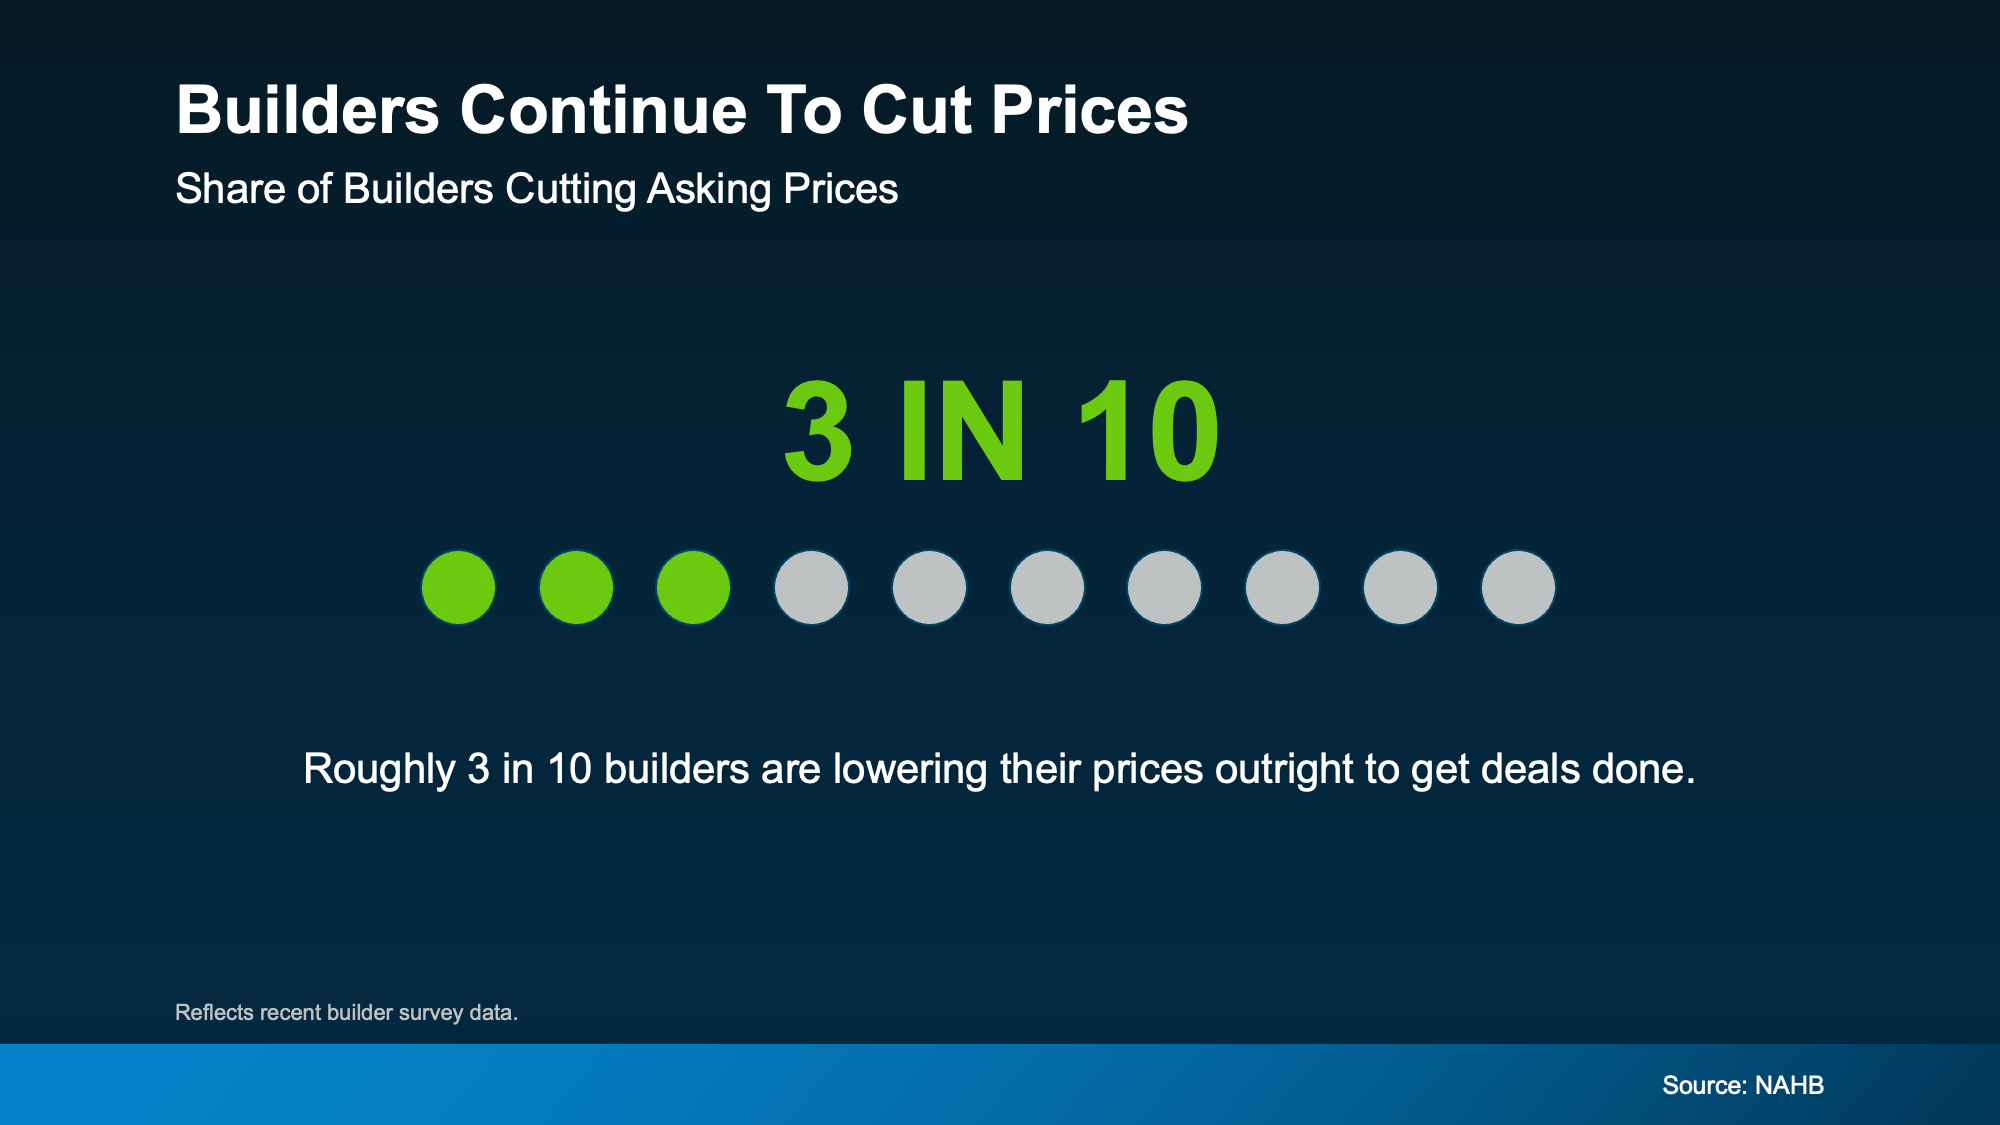
Price Cuts Are Back on the Table

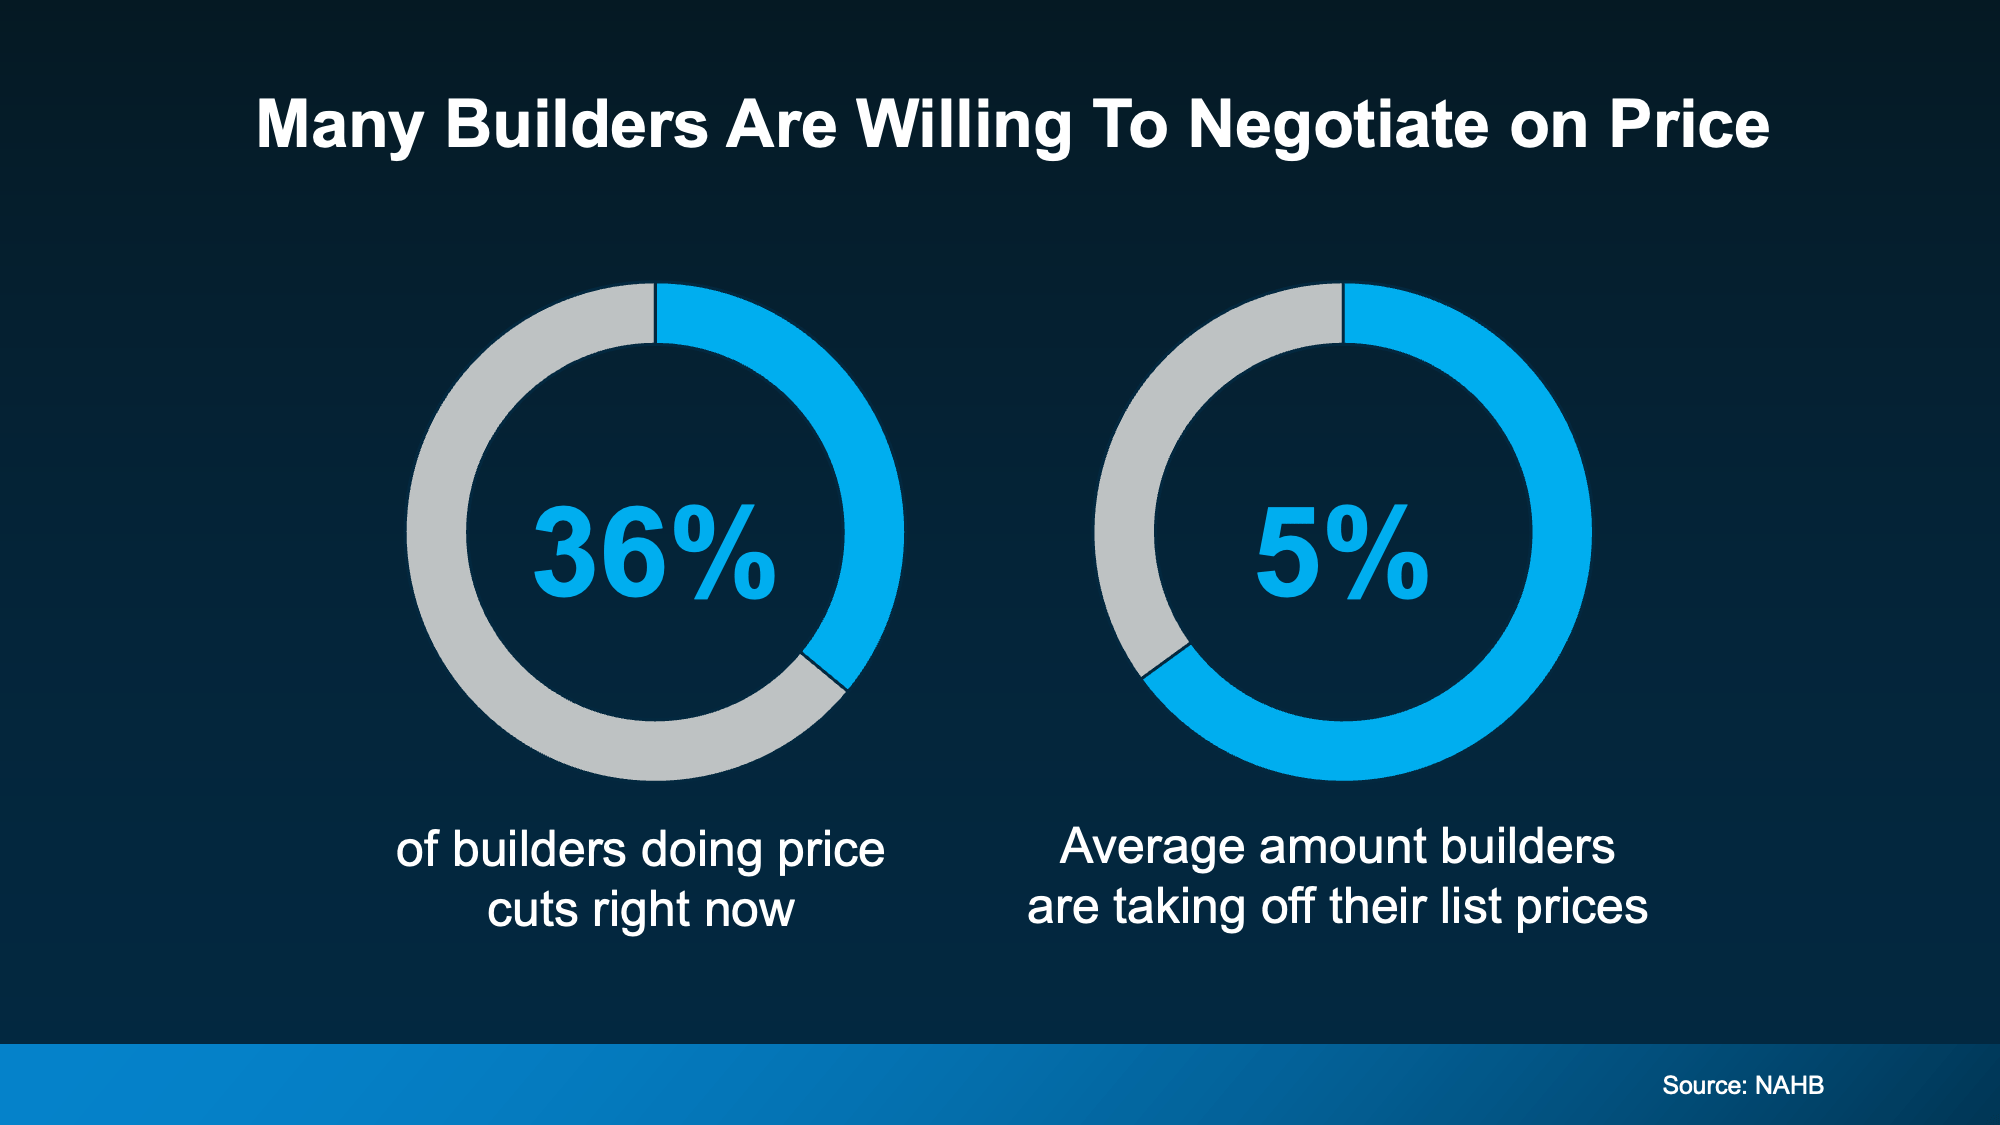
One of the most common incentives they’re offering right now is adjusting the price. According to NAHB, 3 in 10 of builders are doing price cuts (see graph below):

a screen shot of a blue and green screen

On average they’re taking off 5-6% off the purchase price of the house. For a buyer, 5% could be the difference between reluctantly settling and finally getting a home that works for you.

Take a $500,000 house as an example. If builders reduce the price by 5%, you’re saving $25,000.

And even if the builder you’re interested in won’t budge on price, they’ve got plenty of other levers to pull. As Realtor.com explains:

“. . . there are deals to be found in the market for new homes, with builders increasingly willing to negotiate on price or offer incentives such as rate buydowns and closing cost assistance.”

Why This Matters for You

As a buyer, you probably have a clear vision for your ideal home. Because you’re not just buying any house. You’re buying your house. The one with the space, features, and lifestyle you’ve been hoping for. New builds can check those boxes since they usually have:

  • Bigger kitchens and open layouts

  • Energy efficiency (hello lower utility bills)

  • Smart-home upgrades

  • Fewer repair headaches on day one

And today’s incentives make buying a new home more attainable than it's been in years.

One Word of Advice: Don’t Go At It Alone

If you want to take advantage of this opportunity, just be sure to use your own agent. Builder reps aren’t there to save you money. They protect the builder’s bottom line. That’s why you need to bring your agent with you. Your agent will:

  • Cut through the sales pitch and run the cold hard numbers

  • Spot which incentives are actually worth it (and which ones are fluff)

  • Handle negotiations so you walk away with the best deal possible

  • Keep your best interest as their top priority

[created_at] => 2026-09-17T17:44:34Z [description] =>

Even with more homes on the market right now, some buyers are still having a tough time finding the right one at the right price.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260917/Header-Image-20220323-Blog-original.png [id] => 111915 [kcm_ig_caption] => If you're not finding a home you love, the new home market is buzzing with opportunity. With record-high incentives, price cuts in play, and builders itching to move inventory, this is the best time in years to buy new construction. Curious how far today’s incentives could stretch your budget? Let’s connect so you can see what builders are offering in our area. [kcm_ig_hashtags] => NewConstruction,HomeBuilder,KeepingCurrentMatters [kcm_ig_quote] => The majority of builders are offering incentives. [modified] => [poll] => [public_bottom_line] =>

If you're not finding a home you love, the new home market is buzzing with opportunity. With record-high incentives, price cuts in play, and builders itching to move inventory, this is the best time in years to buy new construction.

Curious how far today’s incentives could stretch your budget? Connect with an agent to see what builders are offering in your area.

[published_at] => 2026-08-31T10:30:00Z [related] => Array ( ) [related_to] => Array ( ) [shares] => 0 [slug] => the-majority-of-builders-are-offering-incentives [status] => published [tags] => Array ( ) [title] => The Majority of Builders Are Offering Incentives [updated_at] => 2026-09-17T17:44:34Z [url] => /2026/08/31/the-majority-of-builders-are-offering-incentives/ )

The Majority of Builders Are Offering Incentives

Even with more homes on the market right now, some buyers are still having a tough time finding the right one at the right price.

6
stdClass Object
(
    [agents_bottom_line] => 

Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment.

That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while.

But if you’re interested, let this reassure you. If you want to talk through what home prices are doing in our market, your goals, or your timelines, let’s have a quick conversation.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 53 [name] => Rent vs. Buy [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => rent-vs-buy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Alquilar Vs. Comprar ) ) [updated_at] => 2019-06-03T18:18:43Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:21:25Z [id] => 326 [name] => Equity [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:42Z [slug] => equity [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Equidad ) ) [updated_at] => 2024-04-10T16:21:42Z ) ) [content_type] => blog [contents] =>

It’s one of the biggest hold ups some buyers have right now: “What if I buy, and home prices go down?”

With everything in the news, that concern makes some sense. No one wants to make a big financial decision at the wrong time. But here’s what’s important to know. You don’t want to get hung up on the few places seeing slight declines right now.

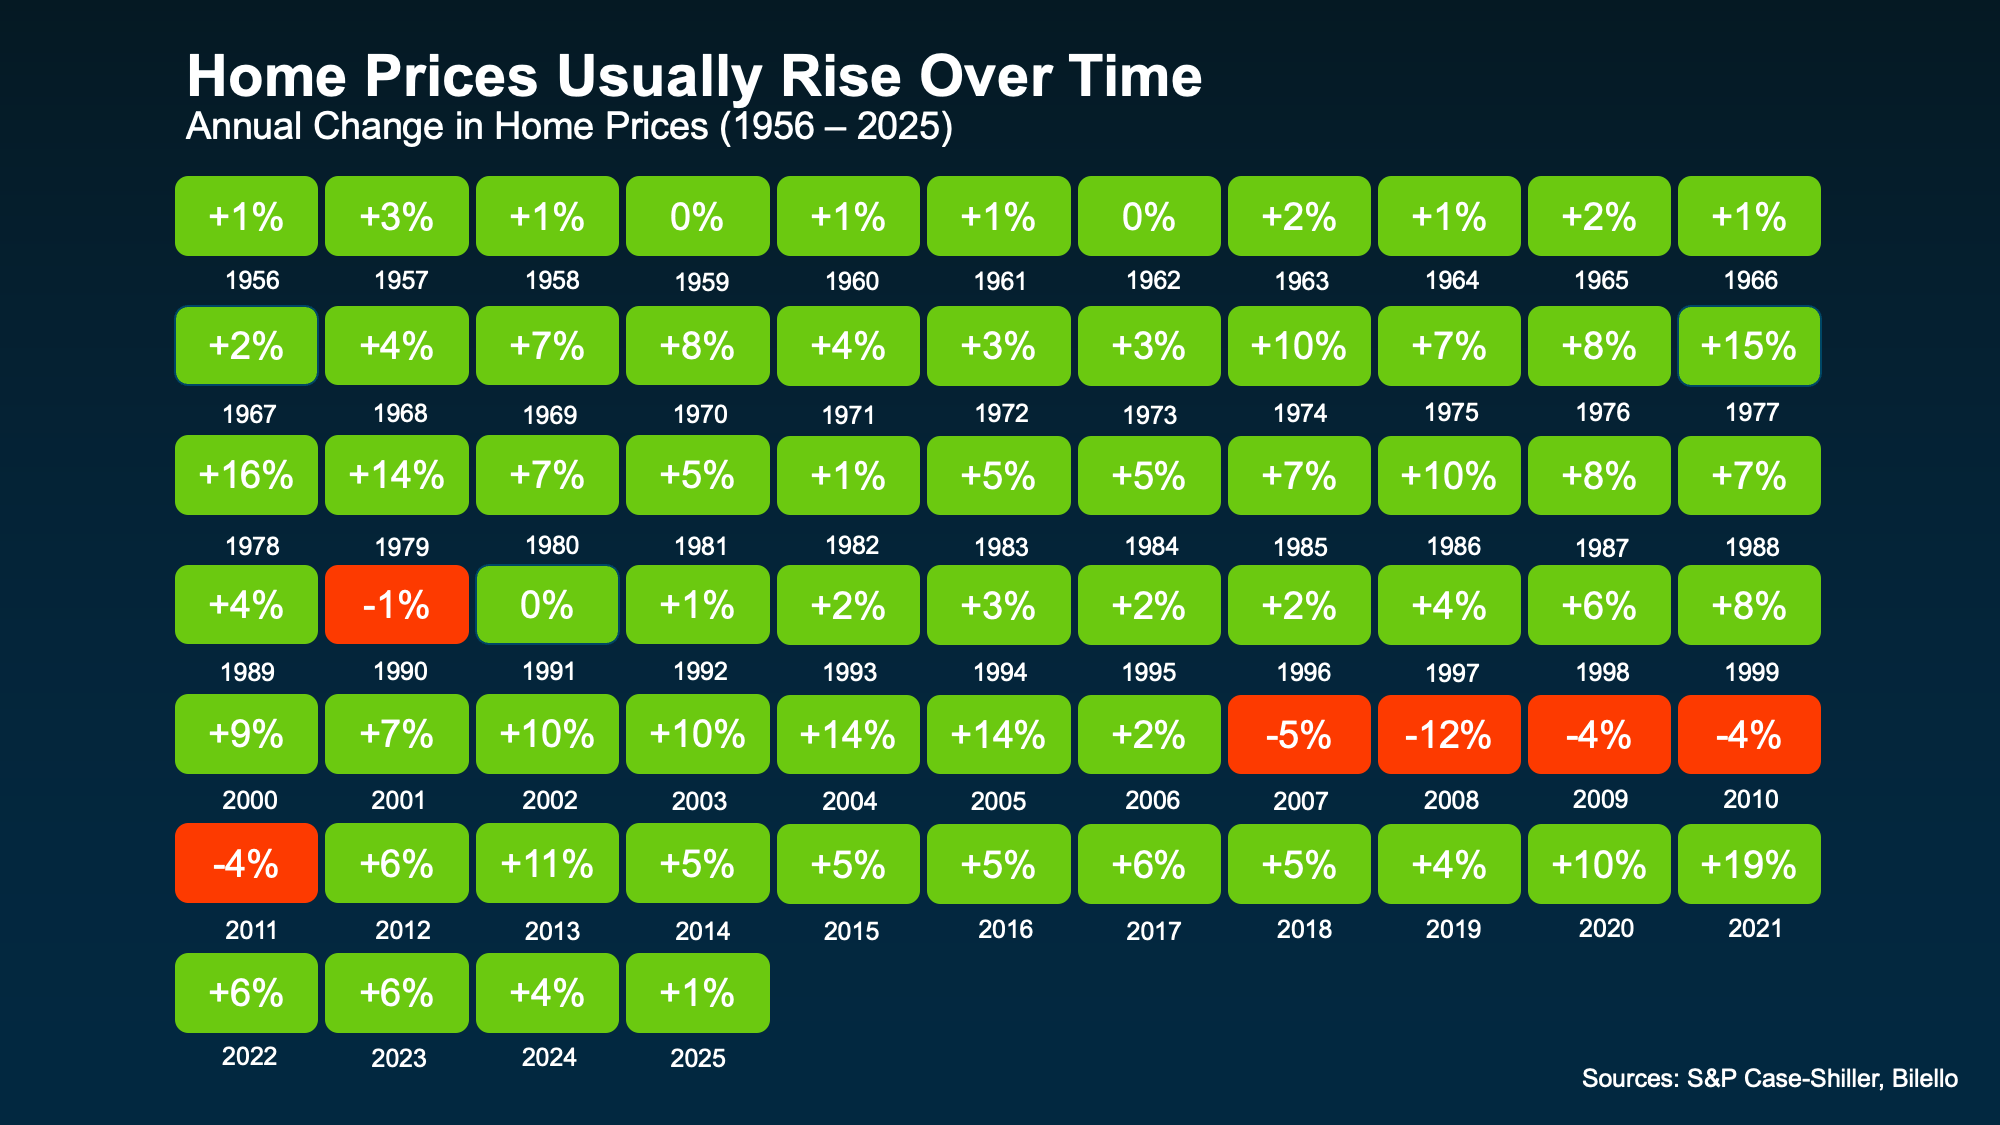
When you zoom out and look at the full picture, home prices usually rise over time.

What the Data Really Shows

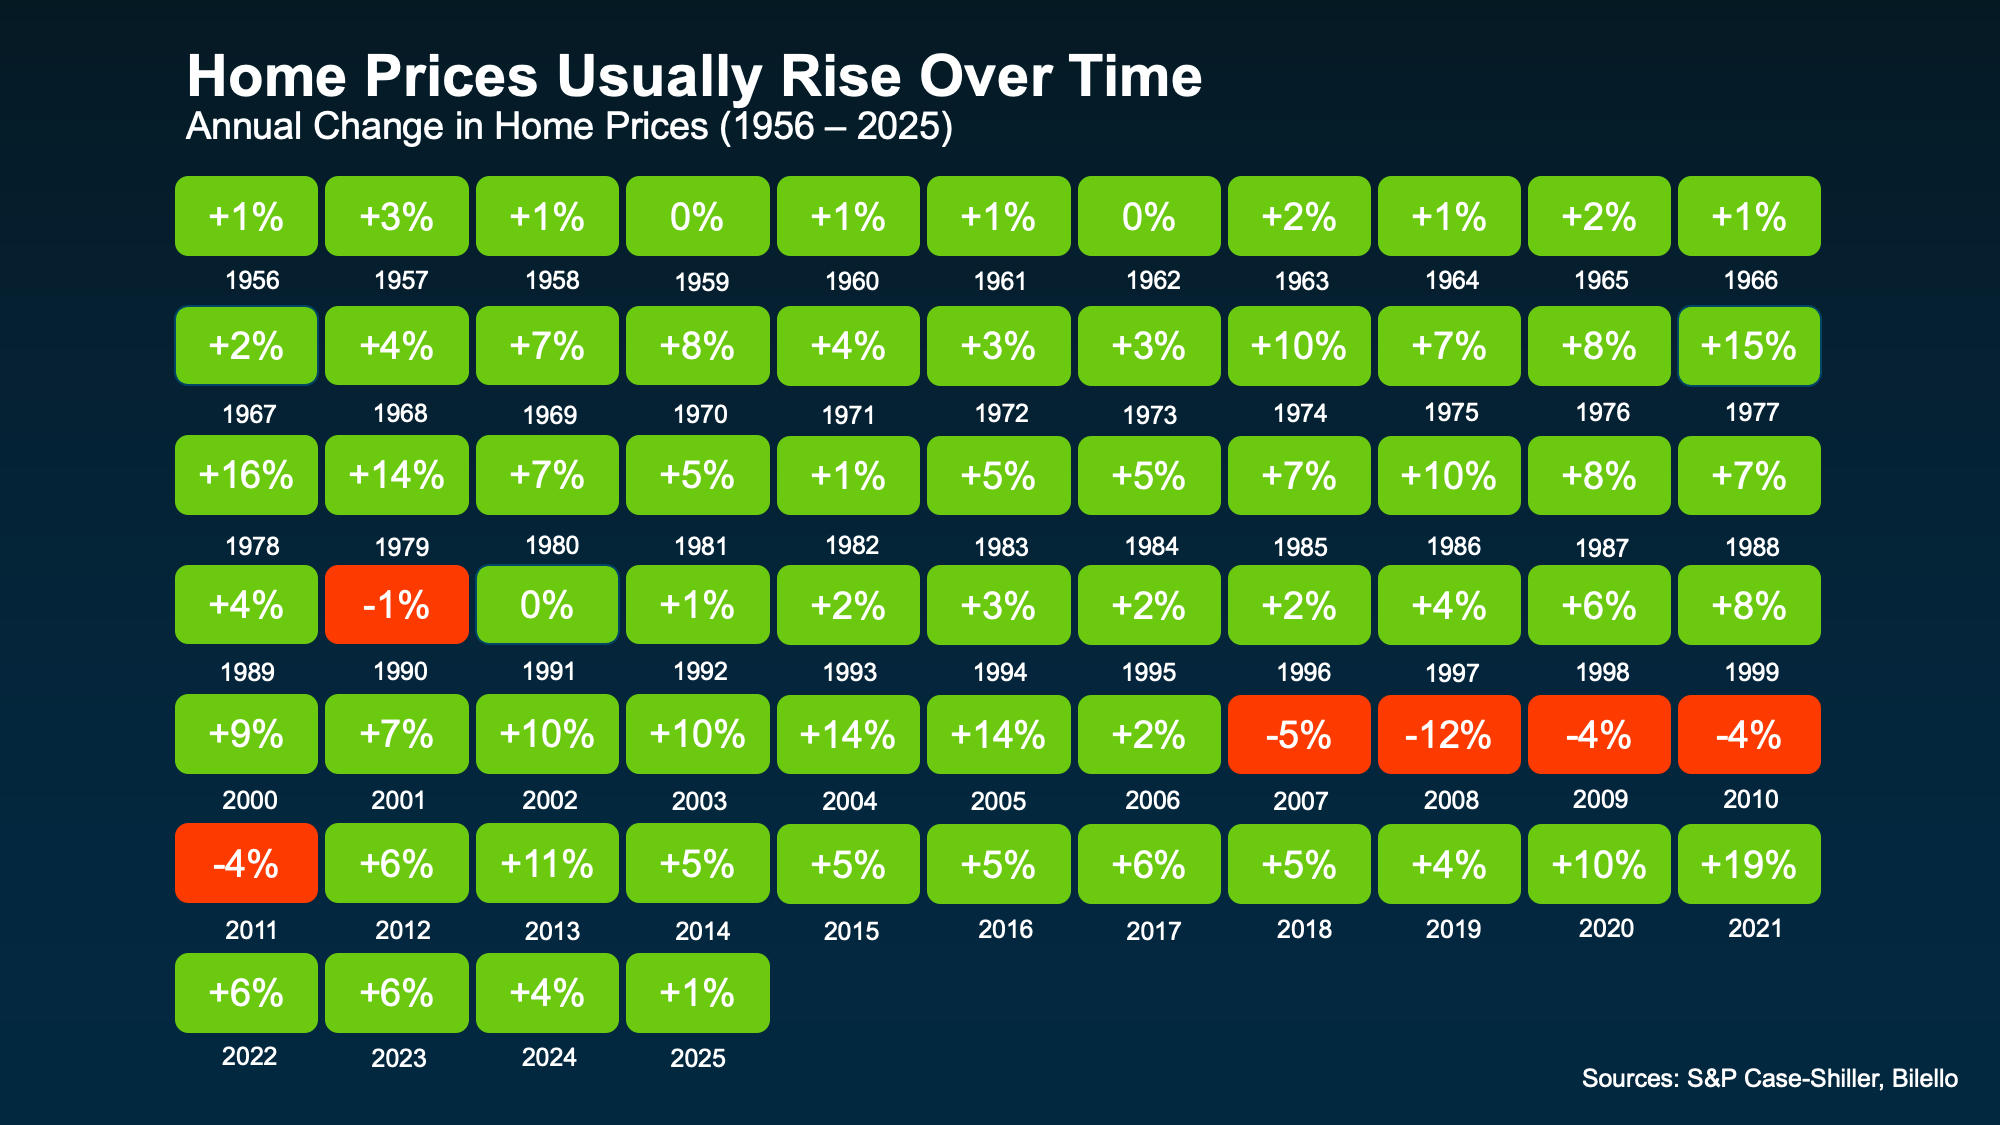
Take a look at the visual below. It uses data from Case-Shiller and Bilello to show how home prices have changed year by year going all the way back to the 1950s.

Here’s the key takeaway.

Outside of the housing crash, home prices have either held steady or increased in just about every year for decades (see visual below):

a chart of percentages and numbers

That’s a remarkably consistent track record. And it shows something a lot of headlines miss.

While short-term shifts can happen, it’s the long-term gains that really matter.

Why Prices Tend To Rise Over Time

There are a few core reasons prices usually go up each year:

  • There are always people who need to move. People need a place to live, and that demand will never fully go away. It may ebb and flow, but someone will always have to move as big changes happen in their life. So, homes stay in demand.

  • There still aren't enough homes for sale. While the number of homes for sale has grown, nationally there’s still an undersupply based on how many people want a home. That keeps upward pressure on prices.

  • Inflation has an impact. Over time, the cost of goods (including homes) naturally increases. That pushes home values higher.

What That Means for You as a Buyer

It’s easy to get caught up in what might happen with home prices next month or next year, especially if you’re a first-time buyer and you’re feeling a little anxious about making such a big financial commitment. But the big picture is clear. Prices usually rise.

That doesn’t mean prices will go up every single year in every market. Real estate is local, and there can be short-term ups and downs. We’re seeing that in some places right now. You can even see it in the few annual dips in the visual above.

But historically, the declines have been temporary.

That’s why it’s generally recommended to buy a home only if you plan to stay for a while – typically at least five years. That’s normally enough time to see your house grow in value. And, it’s enough so you can ride out any short-term changes in the market.

Because when you can do that, something powerful happens. Those rising home values grow your net worth, and by extension, help you build wealth.

The right decision isn’t about timing the market perfectly. It’s about making a move that works for your life and staying in it long enough to benefit from the bigger trend.

[created_at] => 2026-09-17T18:28:42Z [description] =>

It’s one of the biggest hold ups some buyers have right now: “What if I buy, and home prices go down?”

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260917/Header-Image-GettyImages-1192403701-1--original.png [id] => 111918 [kcm_ig_caption] => Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment. That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while. But if you’re interested, let this reassure you. If you want to talk through what home prices are doing in our market, your goals, or your timelines, let’s have a quick conversation. [kcm_ig_hashtags] => Homebuying,HomePrices,KeepingCurrentMatters [kcm_ig_quote] => Are home prices going to fall? Here’s what history says. [modified] => [poll] => [public_bottom_line] =>

Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment.

That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while.

But if you’re interested, let this reassure you. If you want to talk about what home prices are doing in our market, your goals, or your timelines, reach out to a local agent.

[published_at] => 2026-08-31T10:30:00Z [related] => Array ( ) [related_to] => Array ( ) [shares] => 0 [slug] => are-home-prices-going-to-fall-heres-what-history-says [status] => published [tags] => Array ( ) [title] => Are Home Prices Going To Fall? Here’s What History Says. [updated_at] => 2026-09-17T18:28:42Z [url] => /2026/08/31/are-home-prices-going-to-fall-heres-what-history-says/ )

Are Home Prices Going To Fall? Here’s What History Says.

It’s one of the biggest hold ups some buyers have right now: “What if I buy, and home prices go down?”

7
stdClass Object
(
    [agents_bottom_line] => 

The rest of the world may feel unpredictable right now, but the housing market doesn't have to. Prices, inventory, and rates have all found solid ground.

If stability is what you've been waiting for, it's already here. Let’s connect if you want to talk through what that means for your move.

[assets] => Array ( ) [banner_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260831/STM-Banner-2021-Fall-Buyer-Guide-7-original.jpg [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 42 [name] => Featured [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => featured [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Featured ) ) [updated_at] => 2019-06-03T18:18:43Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:06:50Z [id] => 320 [name] => Inventory [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:06Z [slug] => inventory [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Inventario ) ) [updated_at] => 2024-04-10T16:19:06Z ) ) [content_type] => blog [contents] =>

A recent survey from Talker Research asked Americans to pick one word to describe how 2026 has felt so far. The winner? Stressful. And honestly, there’s been a lot going on.

So, it’s understandable if you've been putting off buying or selling a home until things settle down. But you may be waiting on something that's already happened. While everything else has felt shaky, the housing market has become one of the steadiest things out there. Look at the data.

Home Prices Have Leveled Out

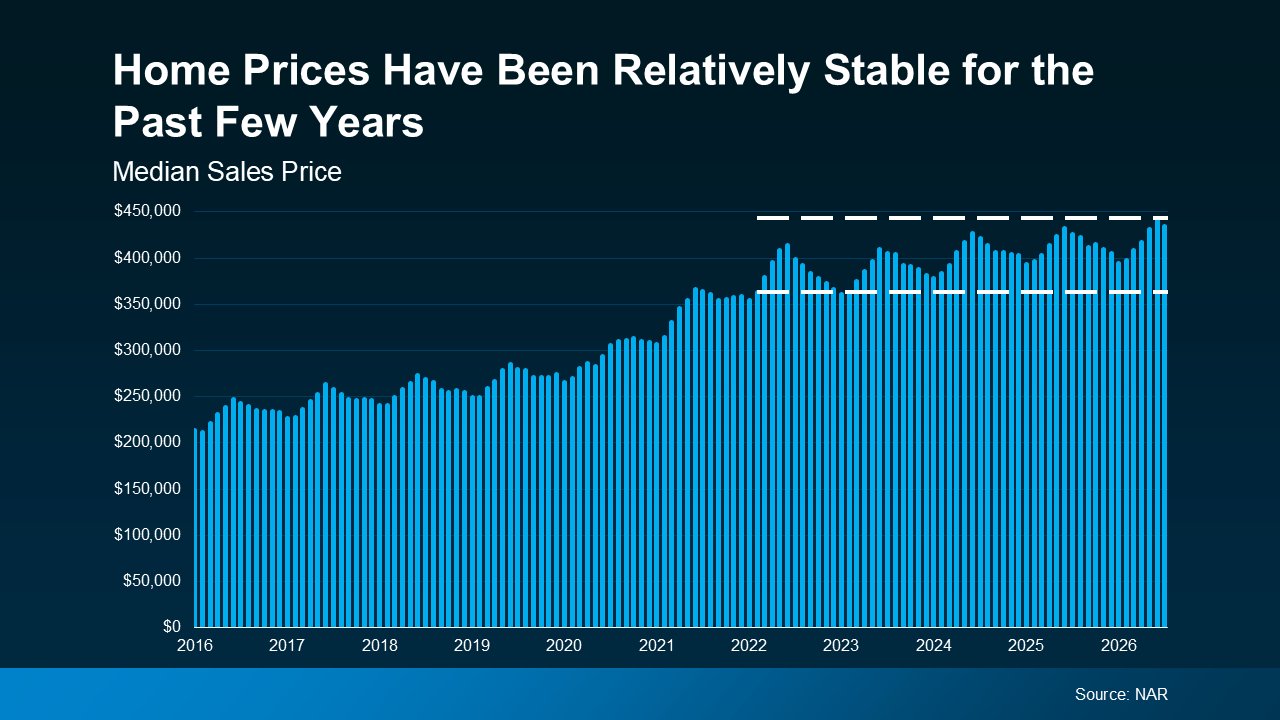
After years of fast increases, data from the National Association of Realtors (NAR) shows home prices have been remarkably steady for the past 4 years (see graph below):

a graph of blue linesAnd experts say that's what to expect going forward, too. As Selma Hepp, Chief Economist at Cotality, explains:
"In 2026, we expect home prices to remain broadly stable, with modest appreciation at a national level."

No wild swings. Just slow, steady growth. That's a healthy market. Of course, that pace can vary a bit depending on where you live. But nationally, steady growth like this makes it easier to plan your budget, whether you’re buying or selling.

The Supply of Homes for Sale Has Steadied

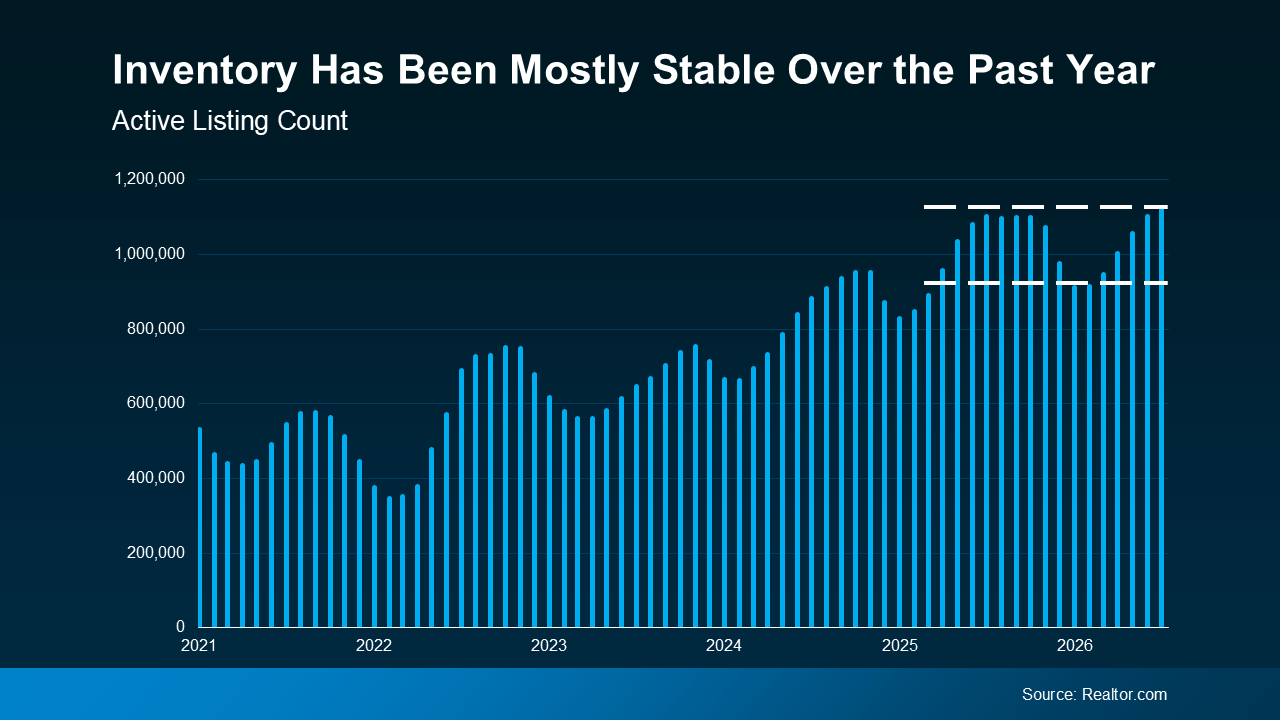
For years, the supply of homes for sale was a moving target. It dropped fast during the pandemic and has been climbing pretty reliably ever since. Now, that pace of growth has slowed down. According to Realtor.com, inventory today is very close to where it was this time last year (see graph below): 

a graph of blue linesThat’s helpful no matter which side you’re on. When the number of homes for sale isn’t changing much, you know what you’re walking into – how many options you’ll have as a buyer, and how much competition you’ll face as a seller.
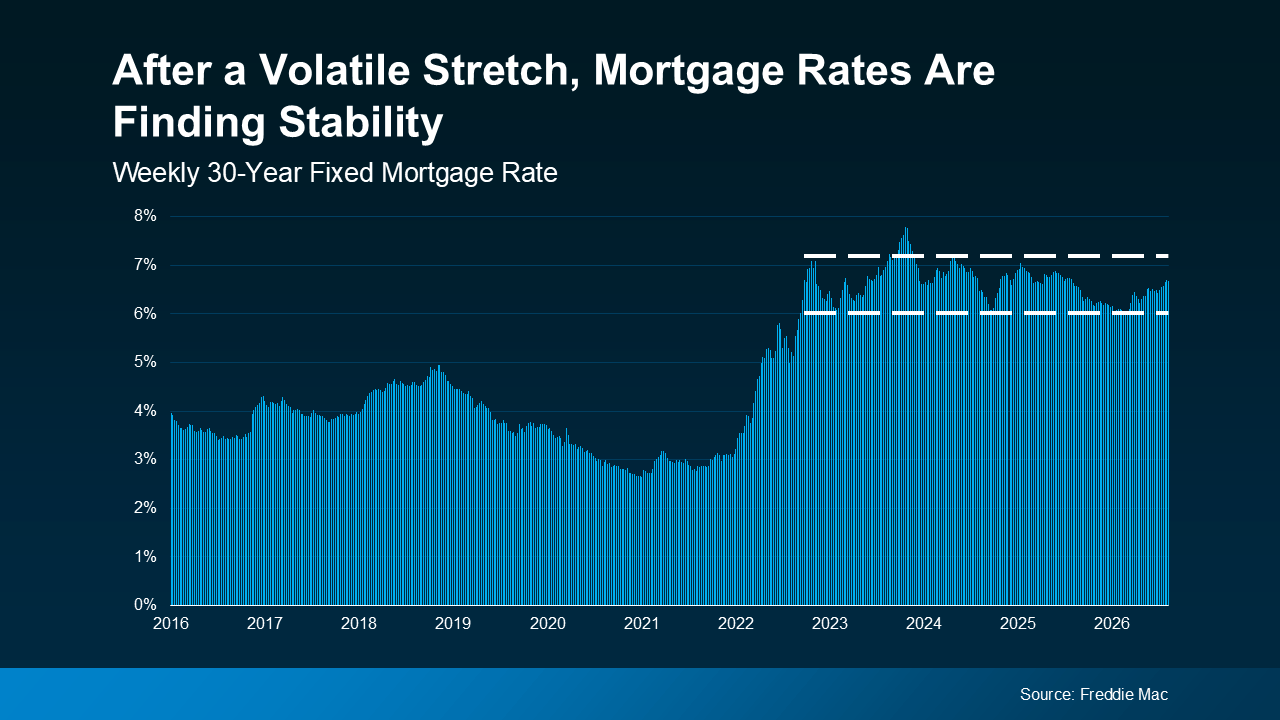
Mortgage Rates Found Their Range

Yes, rates jumped dramatically back in 2022. But since then, Freddie Mac data shows they've stayed between 6% and 7% for the better part of the last 3 or so years (see graph below):

a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph ofYes, there was one brief spike above that threshold, but overall, rates have stayed in that range for a while now. That predictability helps when you’re planning a move. 
And now that this seems to be a longer-term trend, people have accepted it as the new normal. Buyers have gotten comfortable purchasing in that range, and sellers have gotten just as comfortable listing in it.

That comfort’s important because when both sides know what to expect, they keep making moves. In other words, the market isn't frozen waiting for something to change. It's moving calmly.

[created_at] => 2026-08-24T15:08:59Z [description] =>

A recent survey from Talker Research asked Americans to pick one word to describe how 2026 has felt so far. The winner? Stressful. And honestly, there’s been a lot going on.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260824/20260826-Blog-Header-Image-1--original.png [id] => 111004 [kcm_ig_caption] => The rest of the world may feel unpredictable right now, but the housing market doesn't have to. Prices, inventory, and rates have all found solid ground. If stability is what you've been waiting for, it's already here. Let’s connect if you want to talk through what that means for your move. [kcm_ig_hashtags] => HousingMarket,RealEstate,KeepingCurrentMatters [kcm_ig_quote] => Worried about a housing crash? The numbers tell a calmer story. [modified] => [poll] => [public_bottom_line] =>

The rest of the world may feel unpredictable right now, but the housing market doesn't have to. Prices, inventory, and rates have all found solid ground.

If stability is what you've been waiting for, it's already here. Connect with a local real estate agent if you want to talk through what that means for your move.


[published_at] => 2026-08-26T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 111005 [content_type] => must-share [title] => 8/26 Must Share ) ) [shares] => 0 [slug] => worried-about-a-housing-crash-the-numbers-tell-a-calmer-story [status] => published [tags] => Array ( [0] => foundations ) [title] => Worried About a Housing Crash? The Numbers Tell a Calmer Story. [updated_at] => 2026-08-24T15:08:59Z [url] => /2026/08/26/worried-about-a-housing-crash-the-numbers-tell-a-calmer-story/ )

Worried About a Housing Crash? The Numbers Tell a Calmer Story.

A recent survey from Talker Research asked Americans to pick one word to describe how 2026 has felt so far. The winner? Stressful. And honestly, there’s been a lot going on.

8
stdClass Object
(
    [agents_bottom_line] => 

Most home sales still close, and the biggest thing that could get in the way of yours is the one thing you can actually do something about.

With the right prep, your sale has every reason to make it to the finish. So, let’s connect and get your house sold. 

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:16:32Z [id] => 321 [name] => Agent Value [parent] => [parent_id] => [published_at] => 2024-04-10T16:17:42Z [slug] => agent-value [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Valor del agente ) ) [updated_at] => 2024-04-10T16:17:42Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2025-10-30T18:12:44Z [id] => 339 [name] => Expired/Withdrawn/Canceled [parent] => [parent_id] => [published_at] => 2025-10-30T18:12:44Z [slug] => expiredwithdrawncanceled [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => ) ) [updated_at] => 2025-10-30T18:12:44Z ) ) [content_type] => blog [contents] =>

Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window.

But if you’re getting ready to sell, here’s what you should know. Even in today’s market, it rarely comes to that. Buyers who are moving at today’s rates and prices are generally moving because of some big life change. That means they’re motivated, and eager to get all the way to the closing table.

According to the latest data from Redfin, only about 1 in 7 pending sales are falling through. Meaning the vast majority make it all the way to closing.

And the single biggest thing that puts a deal at risk is the one you have the most power to prevent. It just takes a little smart planning before your house hits the market.

Why Some Deals Fall Apart Before Closing

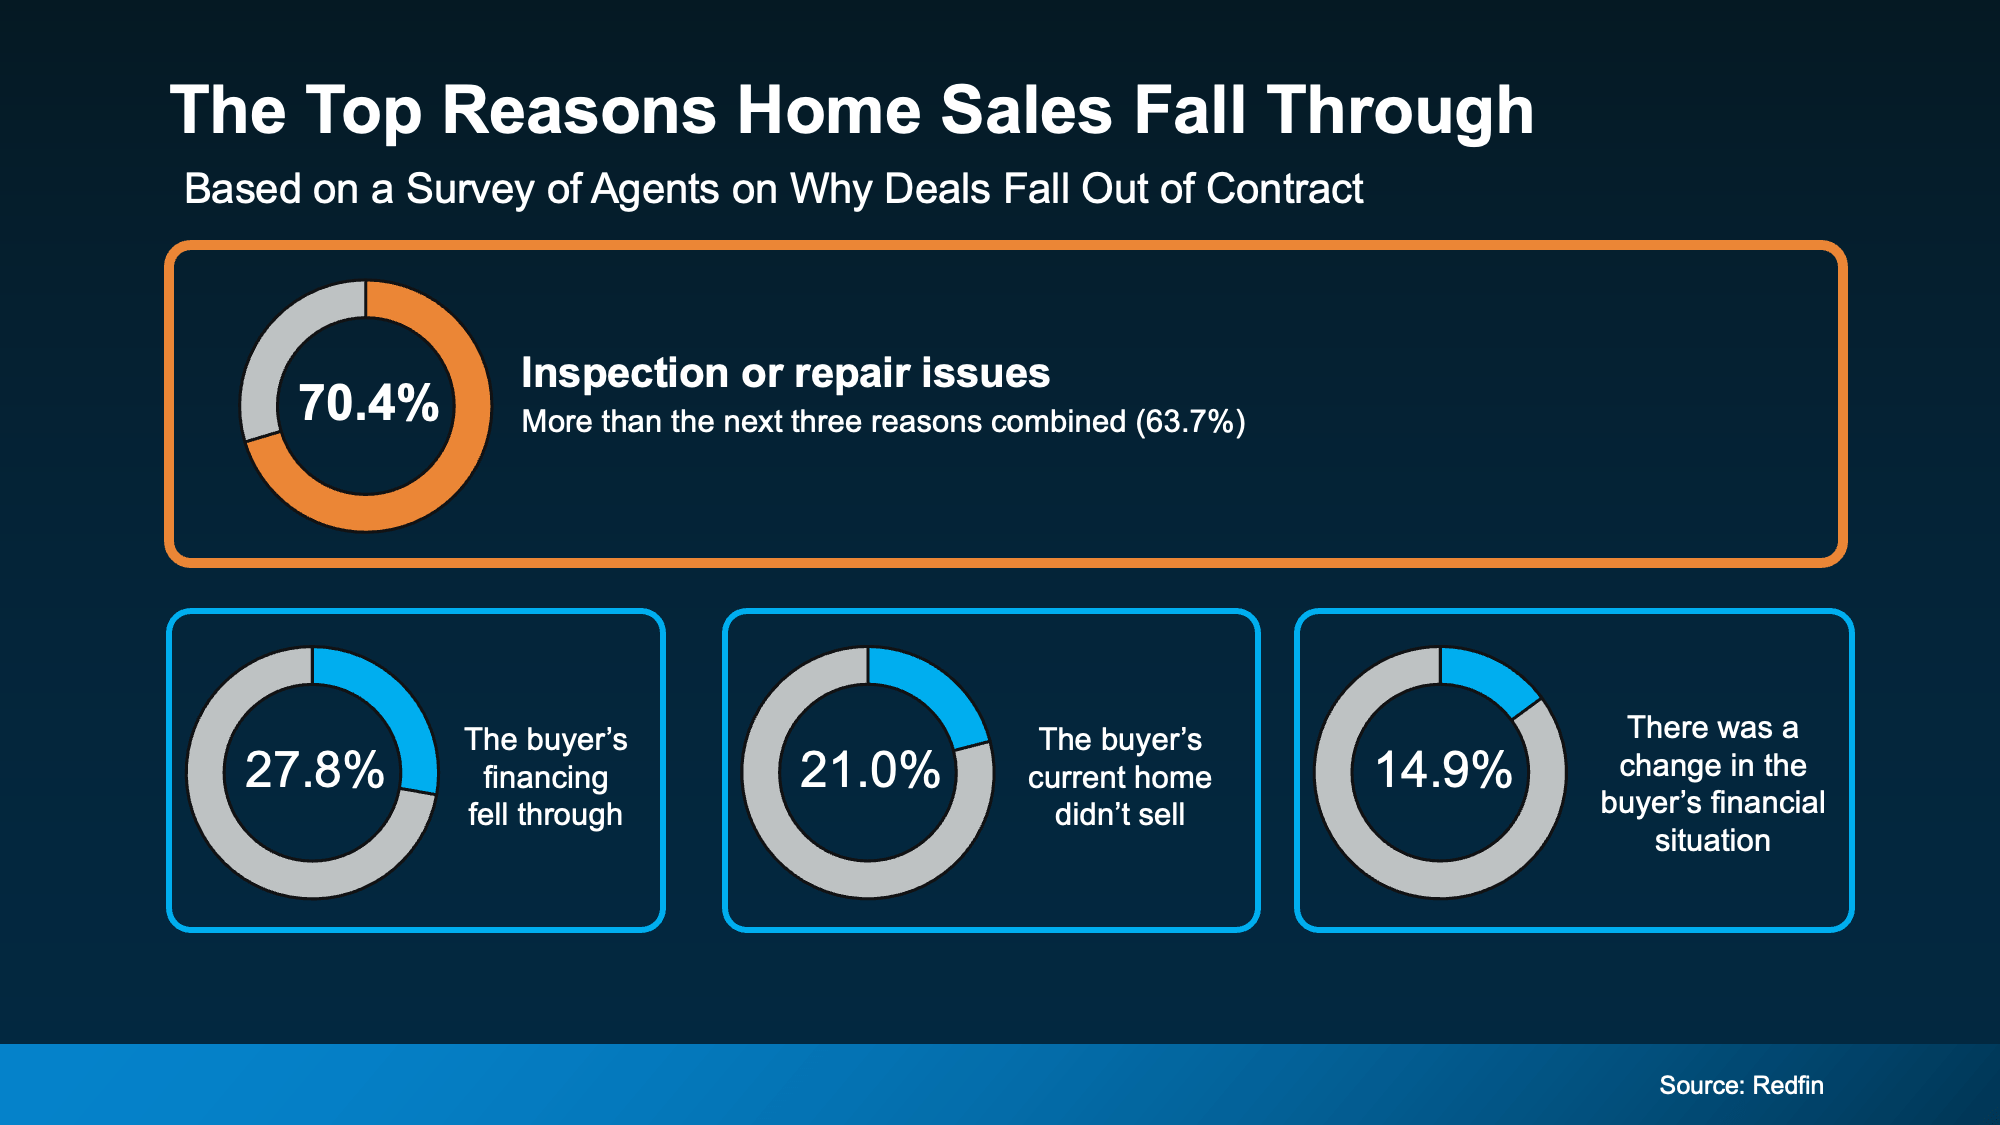
A Redfin survey sheds light on the most common things that trip up a sale (see visual below):

a blue and orange chart with text

Here’s a bit more information on each one.

  • Inspection or repair issues. This is the big one. When a buyer’s inspector finds a problem, whether with the roof, the plumbing, the foundation, or elsewhere, the buyer can push back, ask you to make repairs, request a credit so they can do it themselves, or see if you’ll lower your price. If they don’t get what they want, they may walk away from the deal altogether.

  • The buyer’s financing fell through. Their mortgage loan has to be fully approved in time for closing day. If the loan doesn’t come together, the sale can’t move forward. 

  • The buyer’s current house didn’t sell. Some buyers need to sell their own home before they can close on yours. If that takes longer than expected, you may run into some issues with your timeline or even see them give up on their move.

  • There was a change in buyer’s financial situation. A new job, a big purchase, or new debt can change what a buyer qualifies for on their mortgage loan, even after they were pre-approved.

Where Your Agent Makes the Difference

Some of those reasons are outside your control, like whether a buyer’s loan clears or whether they sell their own home in time. But according to Zillow, there are a few proactive things you can do to help make sure your sale goes as smoothly as possible:

  • Save yourself the headache and get a pre-listing inspection. That’s when you get your own inspection before a buyer gets theirs. It lets you find the big issues before a buyer’s inspector does, so you can fix them or disclose them on your terms, instead of scrambling once you're under contract. In this situation, your agent will help you decide what's worth addressing and what to just disclose. Handle it now, and the biggest risk to your sale is behind you before a buyer ever brings it up.

  • Look at more than just the offer price. Your agent will help you weigh the whole offer, including the buyer’s timeline and any contingencies attached. When a buyer’s offer depends on selling their own home first, the success of your sale rides on a second deal you can’t see. Sometimes, a slightly lower offer with fewer strings is the safer one. Your agent will help you weigh your options and make a plan that works well for you. 

One of those is something you can’t do until you have offers in hand, but the other is something you can get ahead of right now. The pre-listing inspection.

That relatively small cost upfront can save you the much bigger hassle of a deal falling apart later. And while getting your own inspection before listing may not make sense in every market, your agent can tell you whether it’s worth it based on your market, your house, and what buyers are prioritizing in your area.

Sometimes the smartest move is staying one step ahead.

[created_at] => 2026-08-20T17:43:45Z [description] =>

Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260820/Header-Image-20220509-Blog-original.png [id] => 110901 [kcm_ig_caption] => Most home sales still close, and the biggest thing that could get in the way of yours is the one thing you can actually do something about. With the right prep, your sale has every reason to make it to the finish. So, let’s connect and get your house sold. [kcm_ig_hashtags] => SellingTips,SellYourHouse,KeepingCurrentMatters [kcm_ig_quote] => Most home sales close – Here’s how to keep yours on track. [modified] => [poll] => [public_bottom_line] =>

Most home sales still close, and the biggest thing that could get in the way of yours is the one thing you can actually do something about.

With the right prep, your sale has every reason to make it to the finish, and a good local agent can help you get there.

[published_at] => 2026-08-24T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110904 [content_type] => must-share [title] => 8/24 Must Share ) ) [shares] => 0 [slug] => most-home-sales-close-heres-how-to-keep-yours-on-track [status] => published [tags] => Array ( ) [title] => Most Home Sales Close – Here’s How To Keep Yours on Track [updated_at] => 2026-08-20T17:43:45Z [url] => /2026/08/24/most-home-sales-close-heres-how-to-keep-yours-on-track/ )

Most Home Sales Close – Here’s How To Keep Yours on Track

Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window.

9
stdClass Object
(
    [agents_bottom_line] => 

The number of homes for sale is growing slowly but surely, and that means more options for your move. Want to see what’s available in our area? Reach out, and let's take a look together.

[assets] => Array ( ) [banner_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260831/STM-Banner-6-original.jpg [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 42 [name] => Featured [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => featured [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Featured ) ) [updated_at] => 2019-06-03T18:18:43Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:06:50Z [id] => 320 [name] => Inventory [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:06Z [slug] => inventory [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Inventario ) ) [updated_at] => 2024-04-10T16:19:06Z ) ) [content_type] => blog [contents] =>

You may have heard the number of homes for sale isn’t growing like it was. And maybe that has you worried you won’t find a home you love when it’s time to make your move.

But that may be about to change. Here’s why your pool of options may actually start ticking back up again.

Growth Has Slowed, But It Hasn’t Stopped

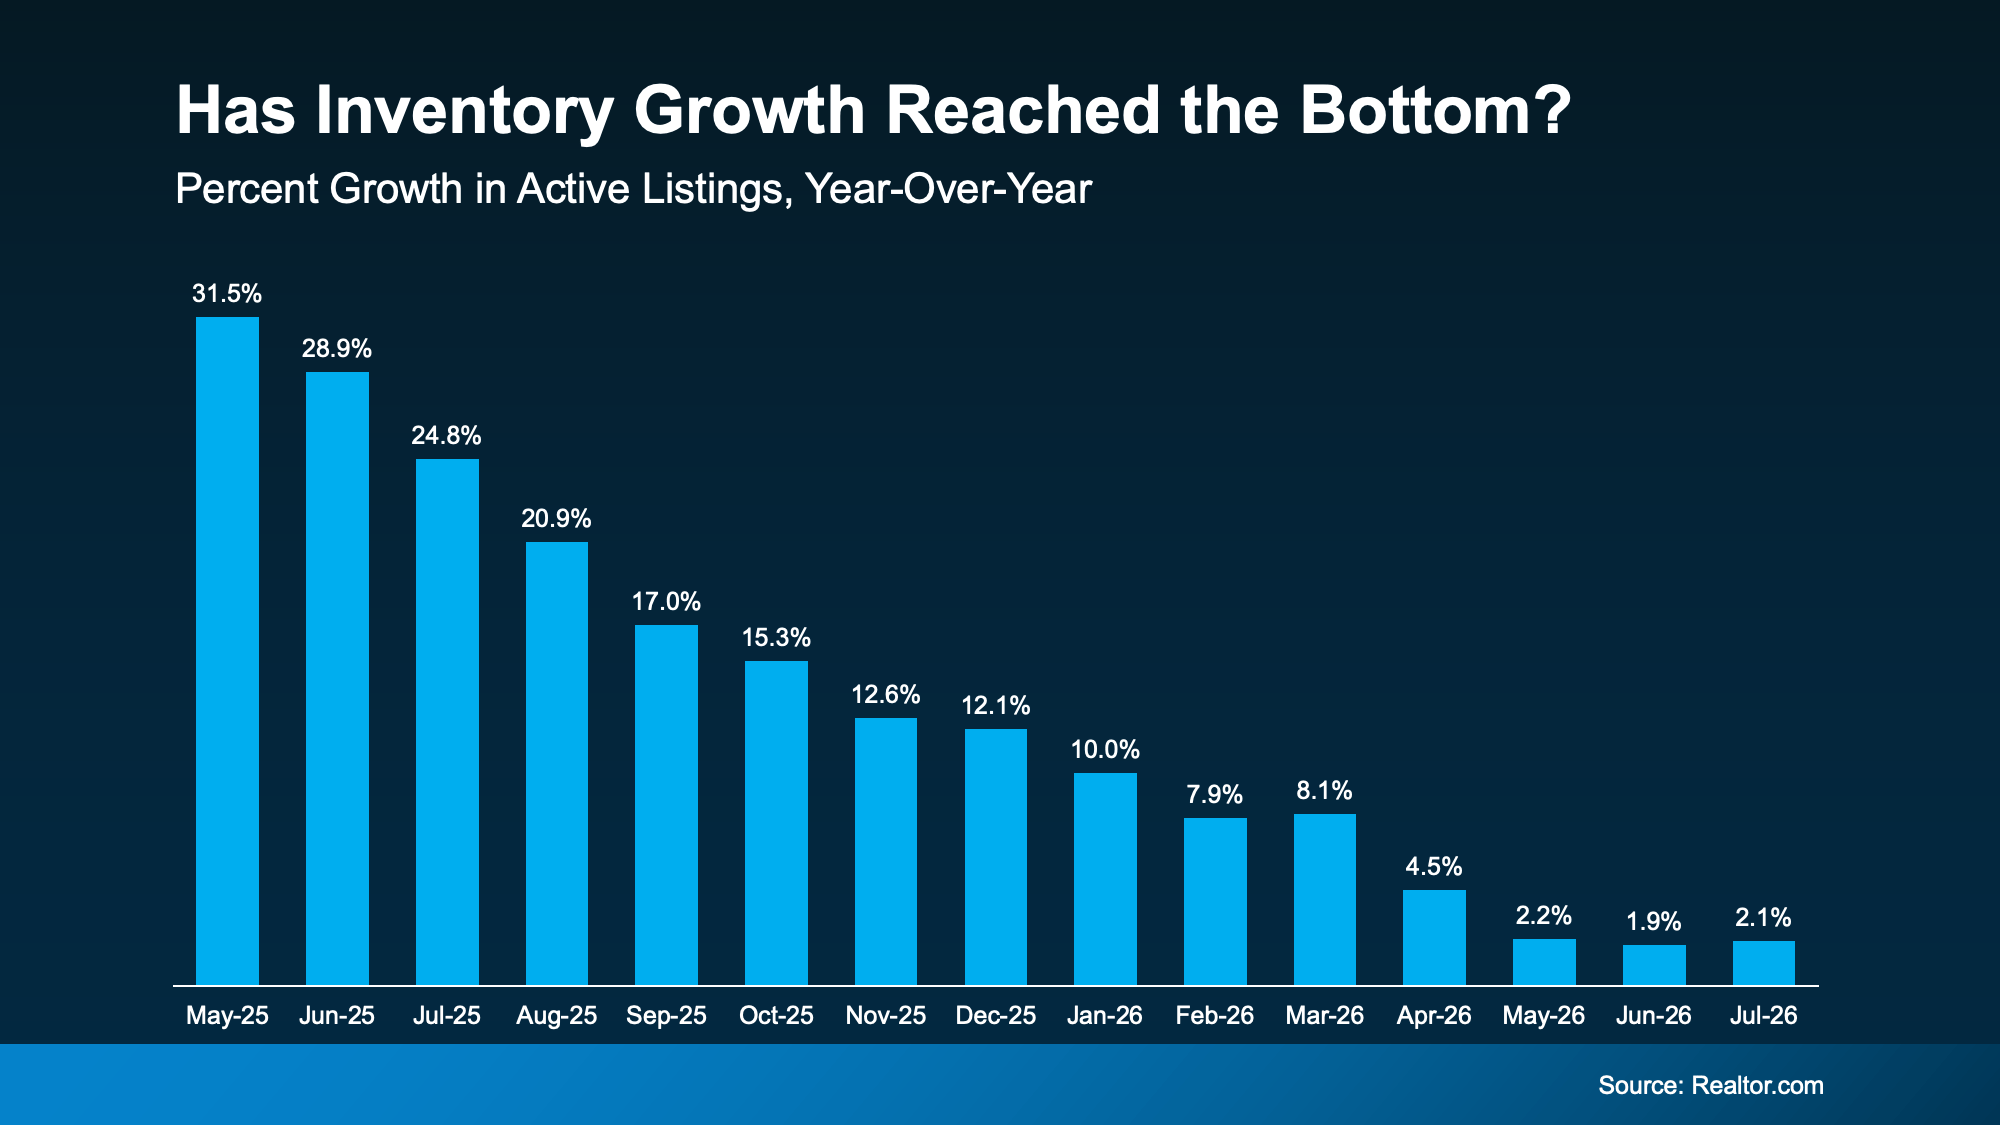
Active listings were up 2.1% year-over-year in July, according to Realtor.com. Back in January, inventory was up 10%. And in May of 2025, it was up 31.5%. So, growth has cooled off a lot over the last year.

The past 3 months, though, have all seen inventory growth land in roughly the same range, which is a sign this slowdown may be nearing its floor (see graph below):

a graph of growth in a blue background

So, what does that mean for you?

Homes are still coming onto the market. Every single one of these bars shows a period where inventory grew. So, don’t be discouraged or let this make you think you’re out of options. Plus, we’ve seen more stability in the numbers lately, which is a good sign.

The Most Homes for Sale Since 2019

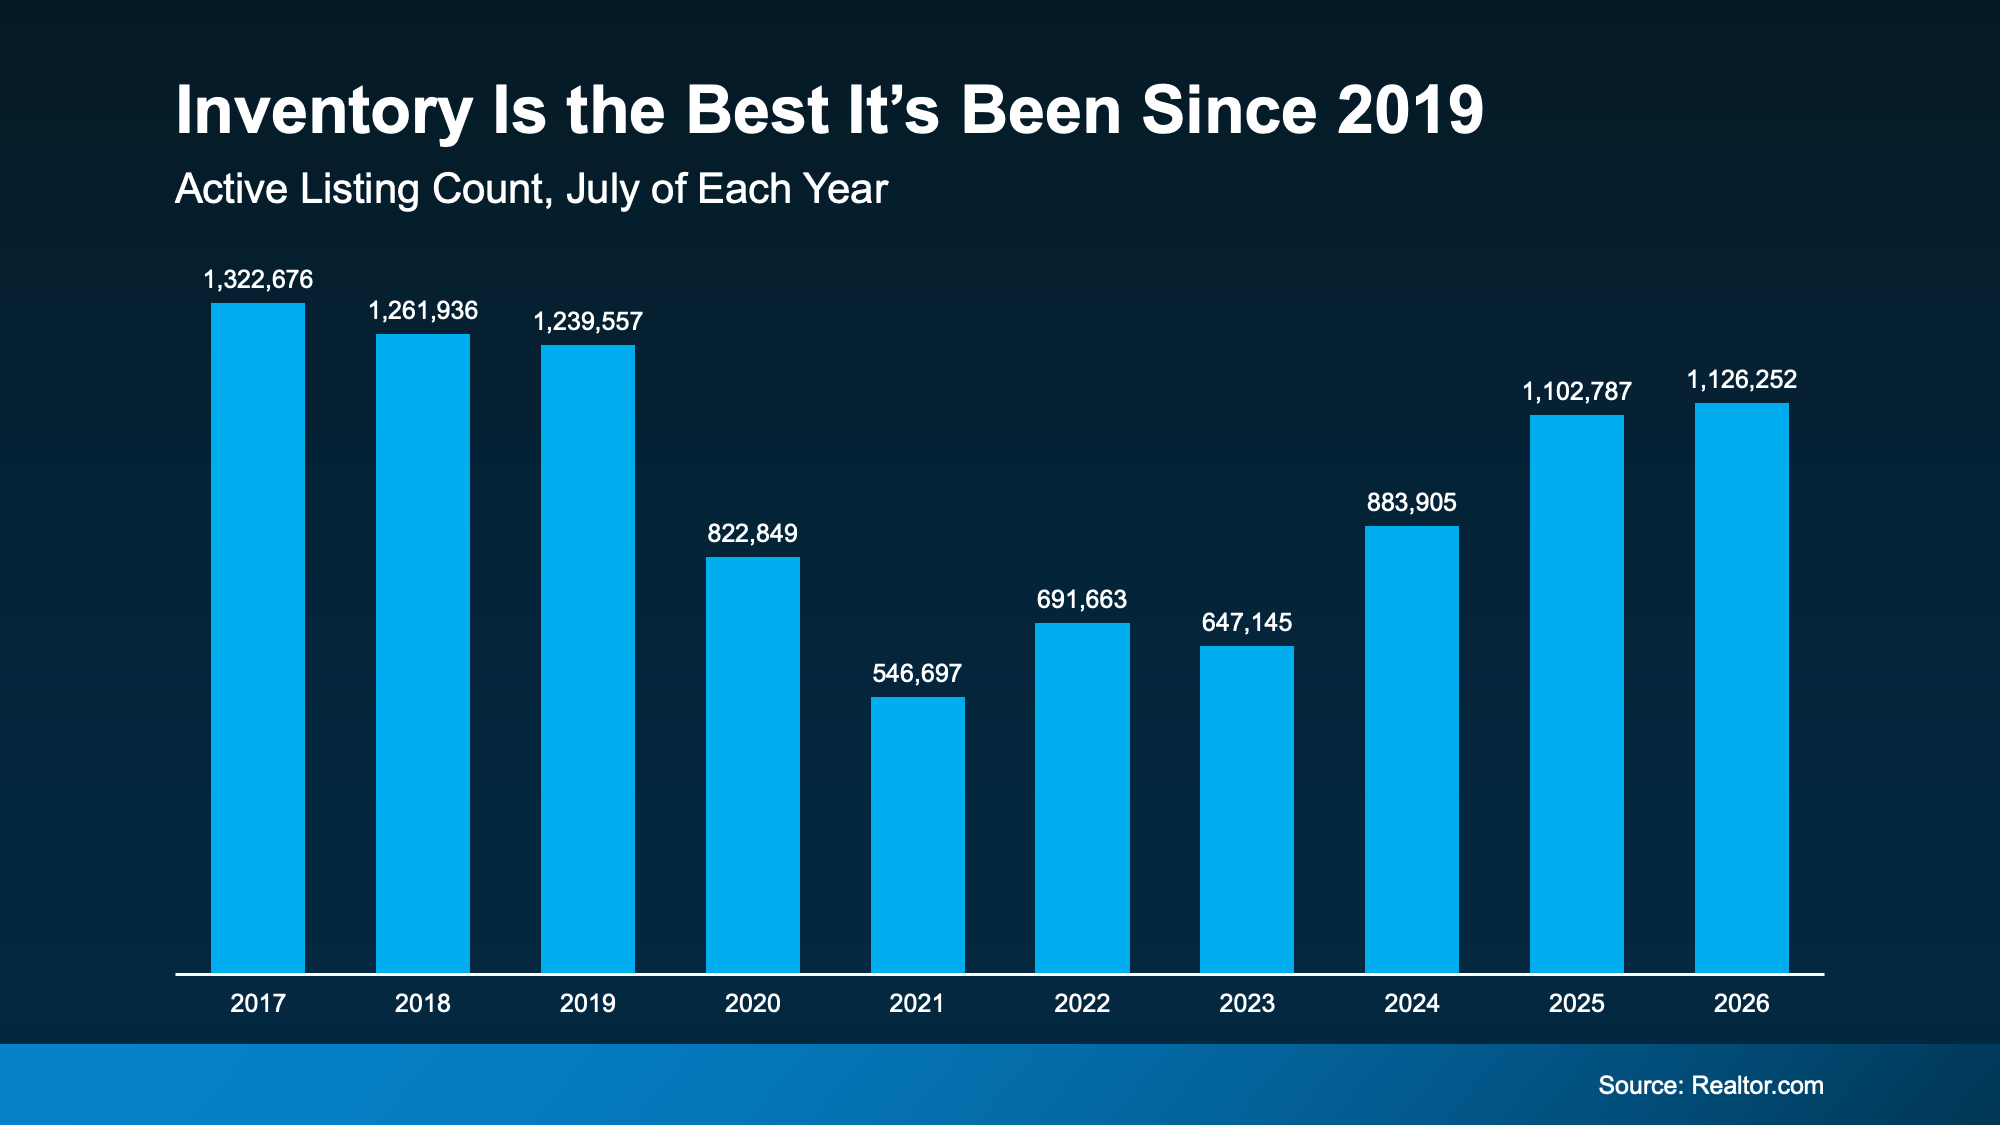
Compared to the rock-bottom lows of 2021, inventory has climbed back substantially. Nationally, the number of homes for sale has been up year-over-year consistently now for 33 months. And inventory has almost doubled in just a few years. So don’t get too hung up on the pace of that increase.

This July was actually the best July for inventory since 2019 (see graph below):

a graph of blue bars with white text

Now, the market still needs about 150k listings to get back to pre-pandemic levels, but things are quickly approaching normal. And experts think we may even be back to 2019 levels by the end of this year, even with the slowdown we’ve already seen.

And that’s thanks to one unlikely factor: mortgage rates. 

Why Higher Rates May Actually Help Inventory Grow

It works like this. When mortgage rates climb, inventory tends to climb with them. As Mike Simonsen, Chief Economist at Compass, explains:

“When rates rise; inventory rises. When rates fall; inventory falls. So, from July last year to March this year, rates ease lower and all the inventory growth of the past several years evaporated. If rates move higher from here or stay elevated for [a] longer period of time, then we should expect supply to build again.”

Well, rates are expected to hold in the mid-to-upper 6% range for a while longer, and Realtor.com's latest forecast has inventory ending 2026 up 3.6% year-over-year.

That means 2 things:

  • Inventory growth is forecast to pick up a little bit throughout the rest of the year.

  • And, inventory is projected to close the year at a historically normal level, right about where it stood at the end of 2019.

For buyers, that’s a win. Even if today’s rates aren’t your favorite, they’re helping the number of homes on the market to grow. And more homes for sale means more choices, more room to negotiate, and less pressure to rush your search.

[created_at] => 2026-08-18T15:24:39Z [description] =>

You may have heard the number of homes for sale isn’t growing like it was. And maybe that has you worried you won’t find a home you love when it’s time to make your move.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260818/Header-Image-6-original.png [id] => 110813 [kcm_ig_caption] => The number of homes for sale is growing slowly but surely, and that means more options for your move. Want to see what’s available in our area? Reach out, and let's take a look together. [kcm_ig_hashtags] => HomesForSale,HousingMarket,KeepingCurrentMatters [kcm_ig_quote] => Higher rates could actually help housing supply – Here’s how. [modified] => [poll] => [public_bottom_line] =>

The number of homes for sale is growing slowly but surely, and that means more options for your move. Want to see what’s available in your area? Reach out to a local real estate agent.

[published_at] => 2026-08-19T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110815 [content_type] => must-share [title] => 8/19 Must Share ) ) [shares] => 0 [slug] => higher-rates-could-actually-help-housing-supply-heres-how [status] => published [tags] => Array ( [0] => foundations ) [title] => Higher Rates Could Actually Help Housing Supply – Here’s How. [updated_at] => 2026-08-18T15:24:39Z [url] => /2026/08/19/higher-rates-could-actually-help-housing-supply-heres-how/ )

Higher Rates Could Actually Help Housing Supply – Here’s How.

You may have heard the number of homes for sale isn’t growing like it was. And maybe that has you worried you won’t find a home you love when it’s time to make your move.

10
stdClass Object
(
    [agents_bottom_line] => 

Your multi-generational-friendly, or simply larger-than-average, house might meet criteria a lot of buyers can't find in a standard one. That's what gets attention. And offers. So, let’s chat about what it could get you in our market right now.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:20:20Z [id] => 324 [name] => Downsize [parent] => [parent_id] => [published_at] => 2024-04-10T16:20:26Z [slug] => downsize [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Reducir el tamaño ) ) [updated_at] => 2024-04-10T16:20:26Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) ) [content_type] => blog [contents] =>

That spare room on the main floor. The finished basement with a kitchenette and its own entrance. The bonus room you've been using for storage.

To you, it's extra space. But to a growing pool of buyers, it's the reason they'd pick your house. Here’s why. Multi-generational homebuying is on the rise.

Millions of Families Are Living Multi-Generationally

The number of multi-generational households is climbing. That’s when 3 or more generations live under one roof. And data shows those households grew from 3.2 million to almost 4 million between 2014 and 2024, according to Realtor.com.

And each year, more people are shopping for a larger home that fits their combined needs.

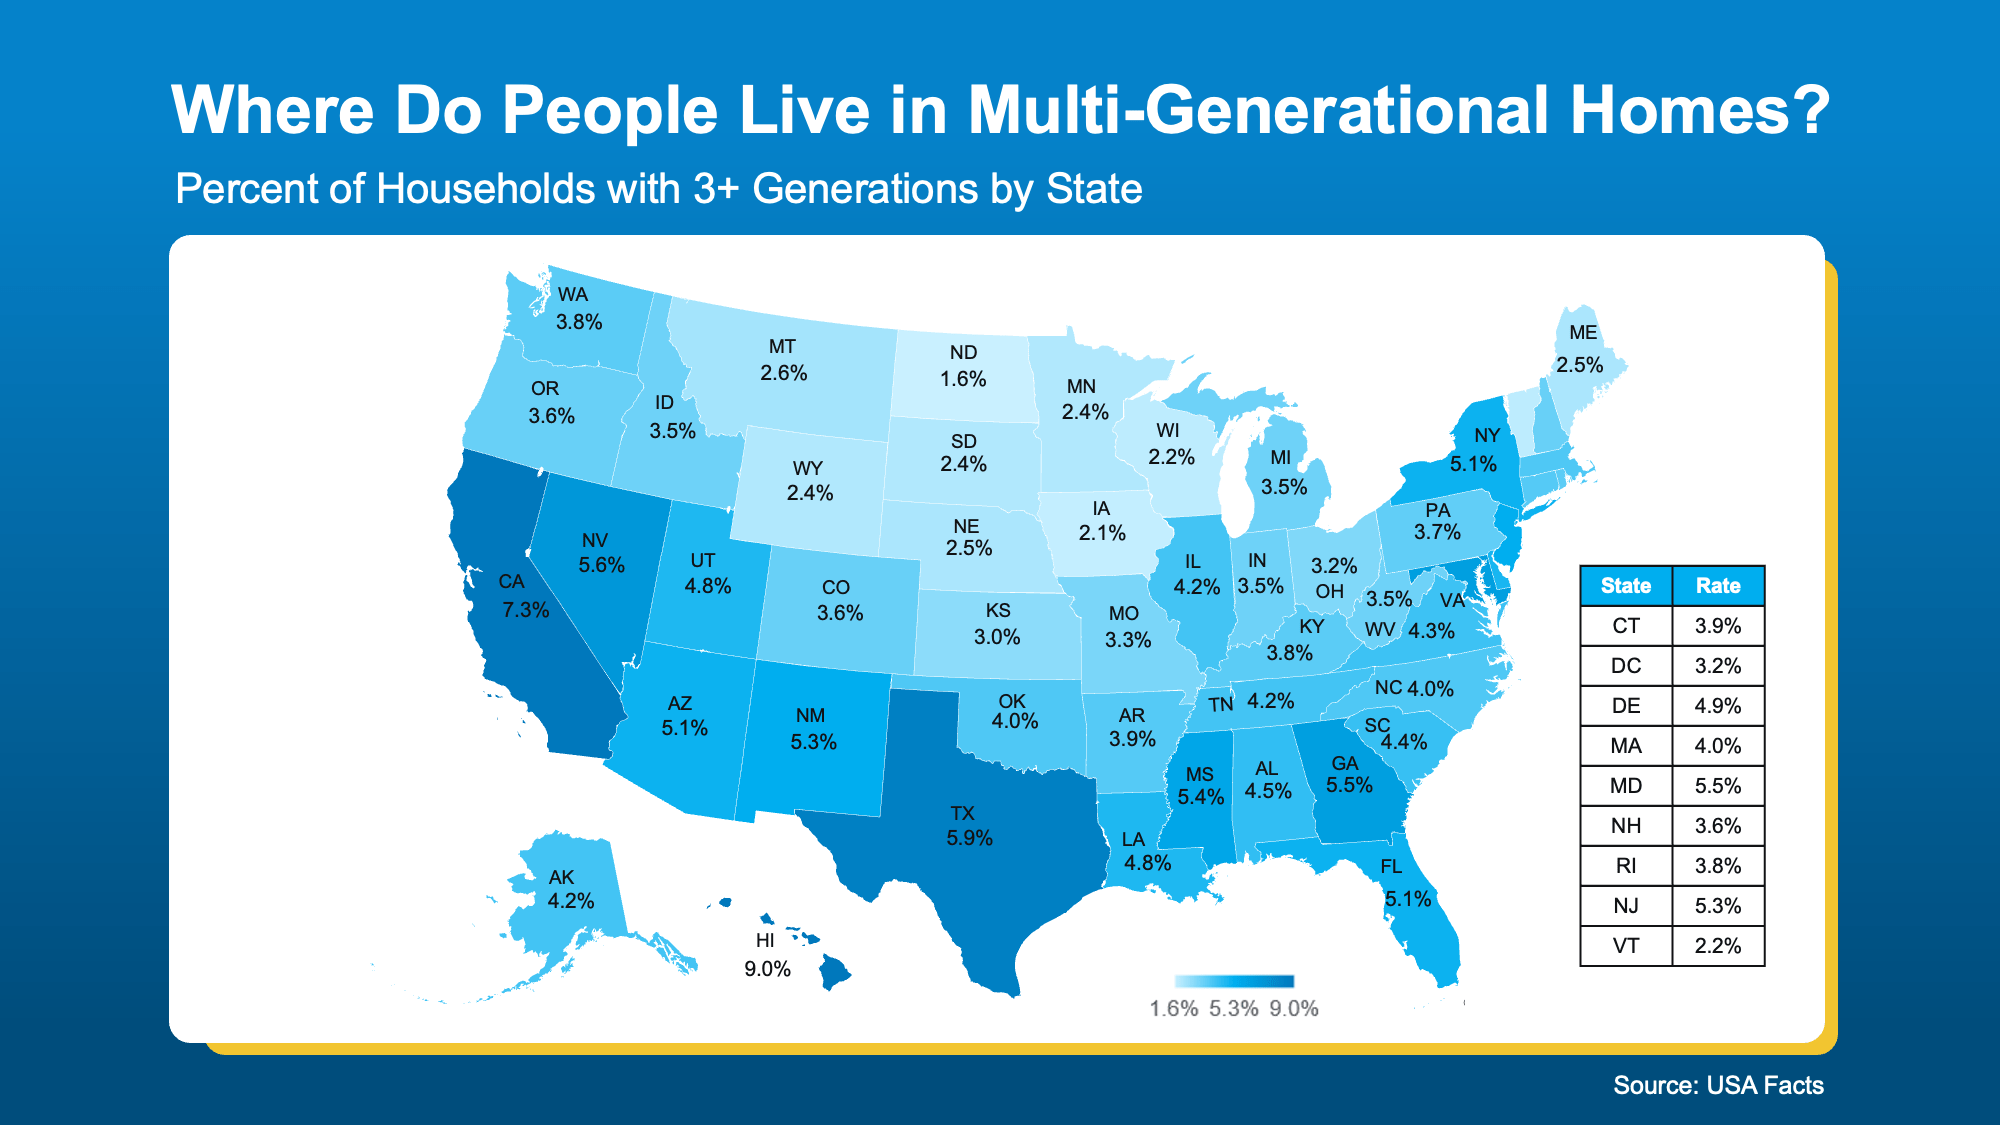
While the appetite for this type of house is rising across the board, data from USAFacts shows multi-generational living is more common in some states than others. The darker the state in the map below, the more common it is in that area (see map below):

a map of the united states

Where does your state fall? Depending on where you are, the pool of buyers looking for a house like yours could be even bigger than you’d think. But the overall bottom line is this.

There’s a real market out there for larger homes with room for multiple generations under one roof, especially since affordability is still so tight. And if you own a house like that, it’s in demand.

Multi-Generational Houses Sell at a Premium

And that extra room carries real value with the right buyer. According to Realtor.com, in 2025 the median asking price for a multi-generational house was $709,000 – roughly 65% higher than the $429,900 median for a standard house.

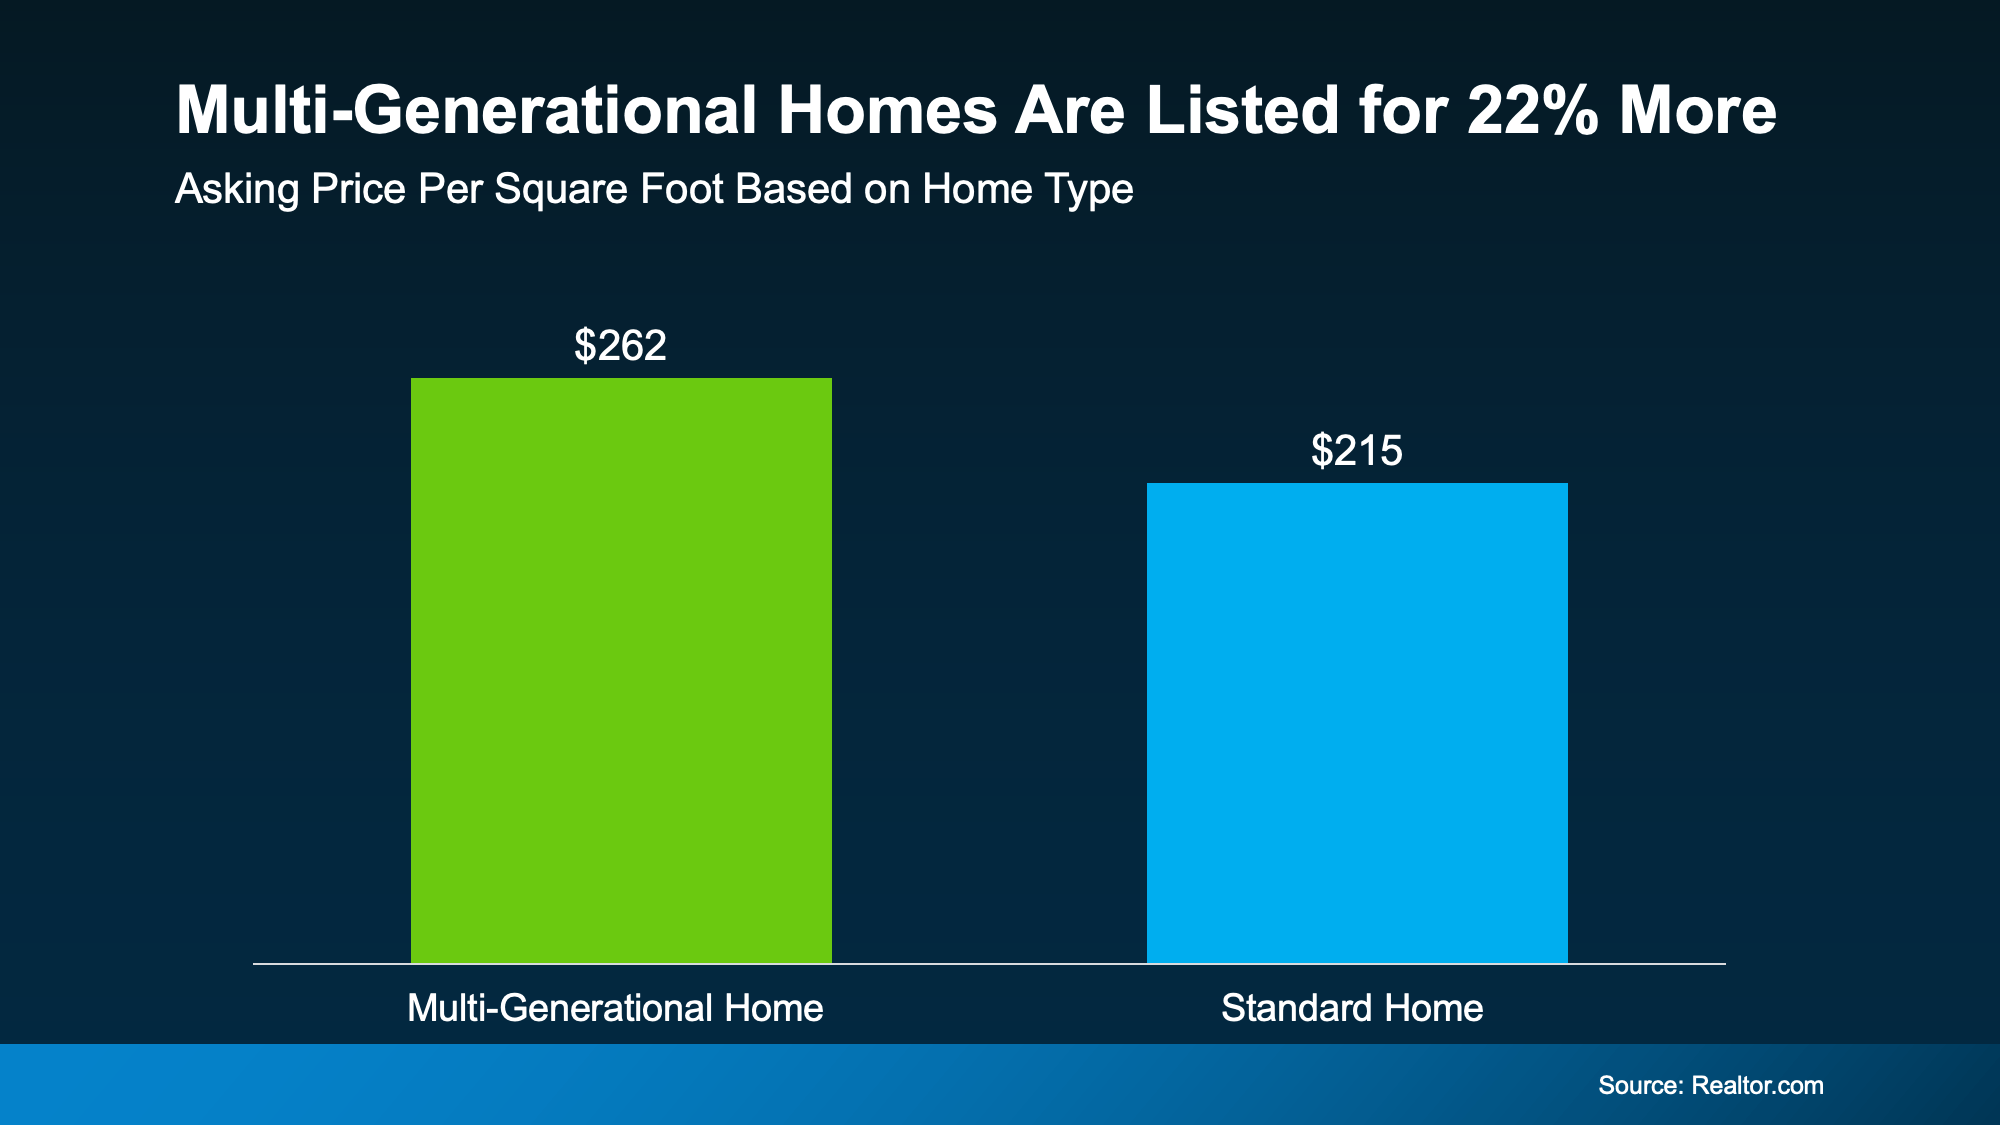
Some of that is simply size. But compare multi-generational homes to regular homes with the same amount of square footage, and they still come out on top – $262 per square foot versus $215.

That’s a 22% premium you could command for special features like in-law suites, second kitchens, and separate entries (see graph below):

a graph of a home sales

When you sell, this could help you walk away with more money in your pocket, especially when your agent highlights your home’s multi-generational-friendly features in your listing.

And Buyers Aren’t Getting Sticker Shock

And even with slightly higher price tags, buyers aren't flinching. Multi-generational houses drew 13.5% more online views than standard ones, and they still sold just as fast – in about 59 days – per the same Realtor.com report.

Hannah Jones, Senior Economic Research Analyst at Realtor.com, explains:

"The strong demand and steep premiums we are seeing in inventory-constrained markets point to a real mismatch between what buyers are looking for and what is actually available. For sellers in these markets, this type of home can be a significant asset."

Basically, when buyers want something that's very specific, the house that checks the box tends to stand out.

[created_at] => 2026-08-11T18:44:31Z [description] =>

That spare room on the main floor. The finished basement with a kitchenette and its own entrance. The bonus room you've been using for storage. To you, it's extra space. But to a growing pool of buyers, it's the reason they'd pick your house.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260811/Header-Image-GettyImages-1426174516-original.png [id] => 110570 [kcm_ig_caption] => Your multi-generational-friendly, or simply larger-than-average, house might meet criteria a lot of buyers can't find in a standard one. That's what gets attention. And offers. So, let’s chat about what it could get you in our market right now. [kcm_ig_hashtags] => MultiGenerationalHome,HomeSellingTips,KeepingCurrentMatters [kcm_ig_quote] => The kind of house buyers are willing to pay more for. [modified] => [poll] => [public_bottom_line] =>

Your multi-generational-friendly, or simply larger-than-average, house might meet criteria a lot of buyers can't find in a standard one. That's what gets attention. And offers. So, talk to a local real estate agent about what it could get you in your market right now.

[published_at] => 2026-08-17T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110572 [content_type] => must-share [title] => 8/17 Must Share ) ) [shares] => 0 [slug] => the-kind-of-house-buyers-are-willing-to-pay-more-for [status] => published [tags] => Array ( ) [title] => The Kind of House Buyers Are Willing To Pay More For [updated_at] => 2026-08-11T18:44:31Z [url] => /2026/08/17/the-kind-of-house-buyers-are-willing-to-pay-more-for/ )

The Kind of House Buyers Are Willing To Pay More For

That spare room on the main floor. The finished basement with a kitchenette and its own entrance. The bonus room you've been using for storage. To you, it's extra space. But to a growing pool of buyers, it's the reason they'd pick your house.

11
stdClass Object
(
    [agents_bottom_line] => 

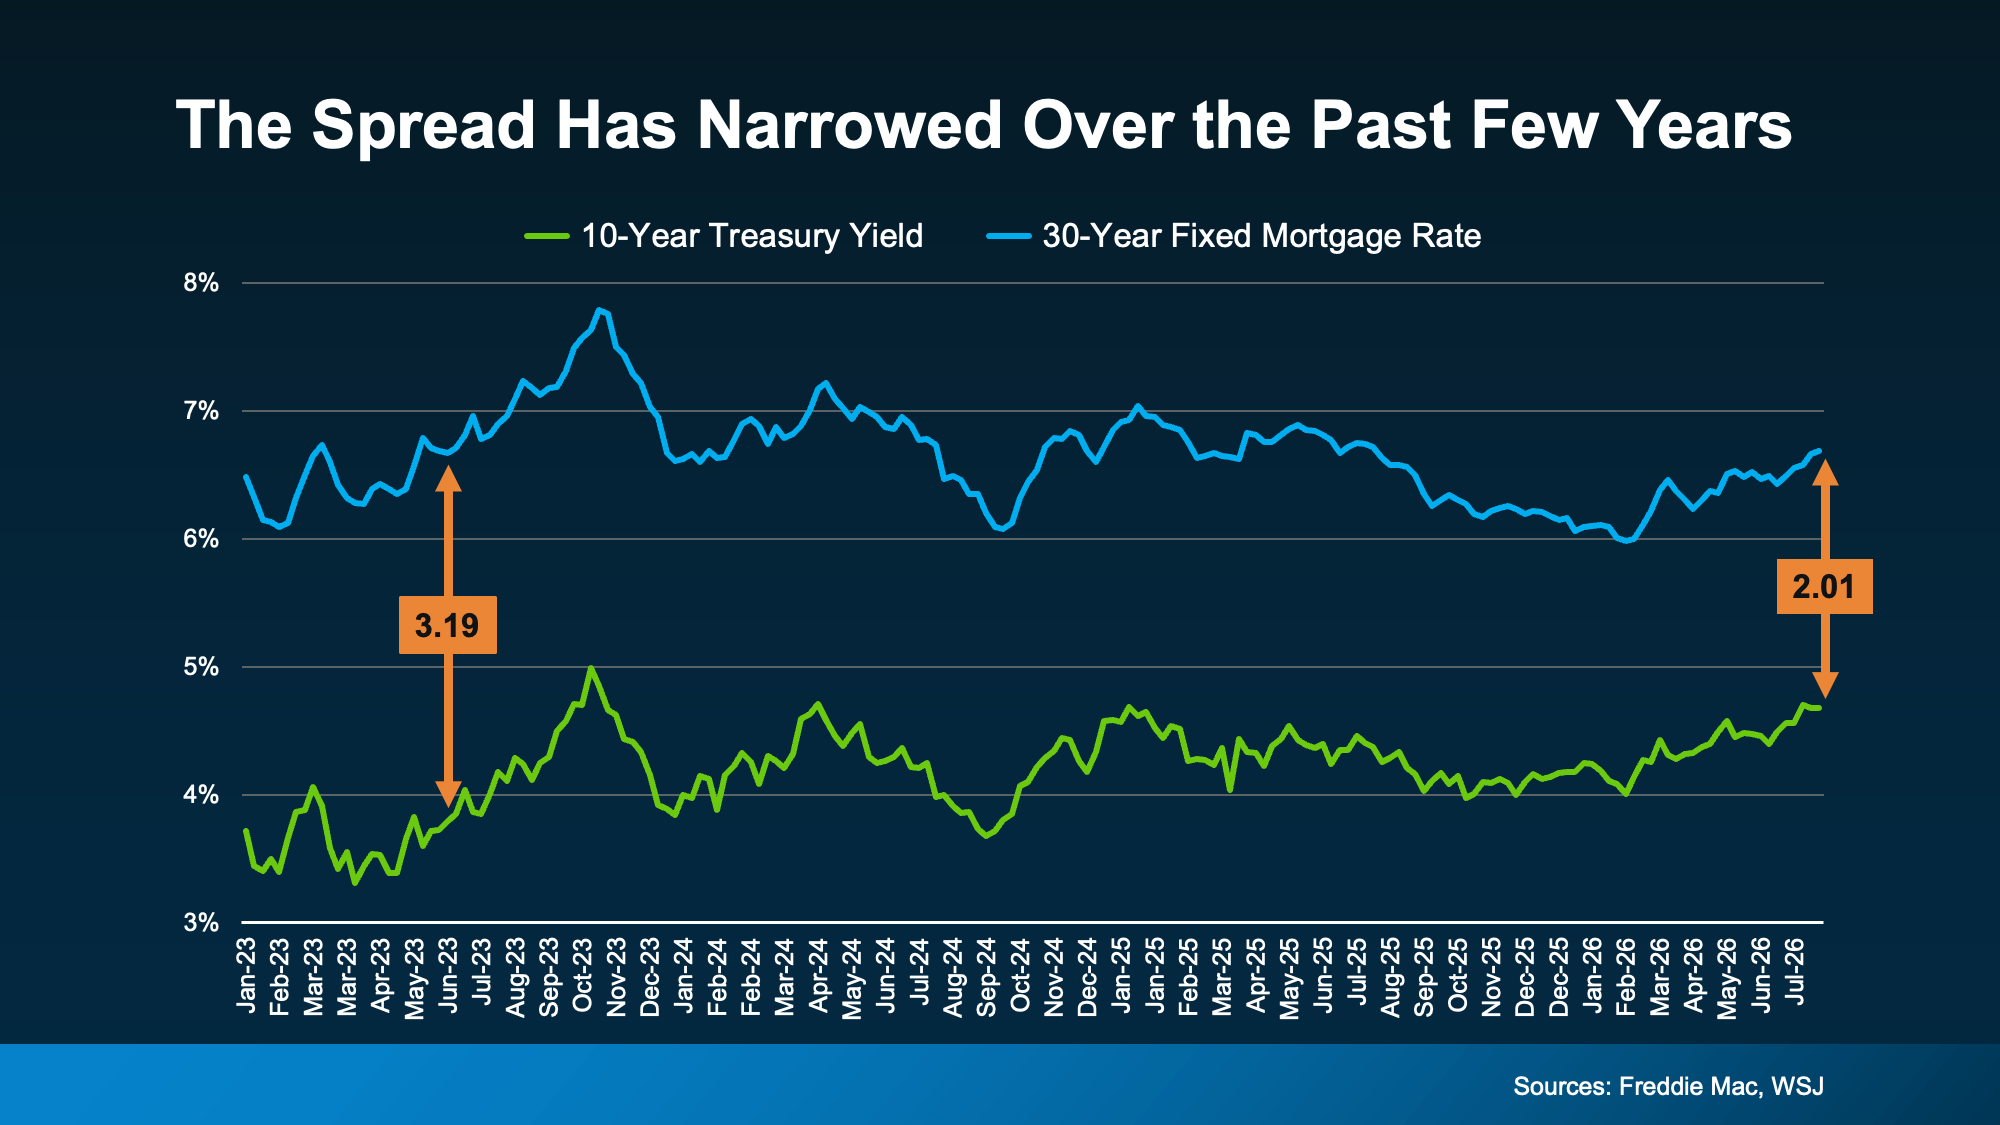
That’s the trade-off with a narrowing spread. Rates may not be where you want them, but they're better than they could've been. If you want help figuring out what that means for your monthly payment, reach out to a local lender

[assets] => Array ( ) [banner_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260831/STM-Banner-202307-SG-3-original.jpg [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 42 [name] => Featured [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => featured [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Featured ) ) [updated_at] => 2019-06-03T18:18:43Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:20:58Z [id] => 325 [name] => Economy [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:04Z [slug] => economy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Economía ) ) [updated_at] => 2024-04-10T16:21:04Z ) ) [content_type] => blog [contents] =>

If you're waiting for mortgage rates to fall a lot before you buy, you may be waiting a while. But before you get discouraged, there's a number working behind the scenes that's actually good for you right now. It's called the spread, and once you understand it, you may see today’s rates in a whole new light.

The Pattern That’s Held for 50+ Years

For starters, mortgage rates don't move on their own. They tend to follow the 10-year treasury yield, a number tied to how investors feel about the economy.

It’s not an exact science, since plenty of other factors can move it day to day, but broadly speaking, when the economy looks strong, that yield tends to climb over time. When the outlook gets shaky, it tends to ease. For over 50 years, the 10-year treasury yield and mortgage rates have moved almost in lockstep (see graph below):

a graph of a graph showing the number of mortgage rates

The gap between them is called the “spread.” On average, that gap runs about 1.76 percentage points. And that spread impacts your mortgage rate. A wider spread tends to push mortgage rates higher than the treasury yield alone would suggest, while a narrower spread keeps rates closer to the treasury yield.

One of the Big Reasons Rates Likely Won’t Drop Dramatically Anytime Soon

If you’re hoping mortgage rates will drop a lot, here’s the reality – they probably won’t, at least not anytime soon. One of the big reasons why comes down to that spread between the 10-year treasury yield and mortgage rates.

A few years ago, that gap got a lot wider as uncertainty in the economy pushed it as high as 3.19 points in 2023.

Now here's the part worth noting – that gap has been narrowing lately. It’s down to about 2.01, just above the long-term average of 1.76 (see graph below):

a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of

When the gap is wide, there’s more room for rates to fall. But when it’s relatively normal, like it is now, there’s less wiggle room for rates to fall.

Why Mortgage Rates Aren’t Higher Right Now

Today’s mortgage rate is basically the treasury yield plus the spread. So, when either one moves, your rate moves with it. Here are 3 different rates, all built off today's 10-year treasury yield of 4.68% to show you just how much the spread matters for your bottom line (see graph below):

a graph of a graph showing a rate of interest

If the spread were still stretched out like it was in 2023, rates would be pushing close to 8% right now. That’s because the spread was over a full point wider than it is today.

But now, thanks to the spread narrowing recently, today's rate sits around 6.69%. That’s the middle scenario in that visual. That's a big difference in your monthly payment compared what we could see if the spread was as big as it was 2023. As Logan Mohtashami, Lead Analyst at HousingWire, put it:

“Of course, mortgage spreads being better in 2026 is the housing hero story of the year . . .”

Now compare that middle bar to the 3rd one. If the spread were sitting at its exact long-term average, rates would be around 6.5%. That's only about a quarter of a point away from where rates actually are today. That means most of the improvement in mortgage rates we should realistically expect from a shrinking spread has already happened.

In other words, the same narrowing spread that’s the reason rates aren’t close to 8% today is also a big reason why they’re not likely to fall a lot further.

[created_at] => 2026-08-11T18:24:42Z [description] =>

If you're waiting for mortgage rates to fall a lot before you buy, you may be waiting a while.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260811/Header-Image-202307-SG-3-original.png [id] => 110566 [kcm_ig_caption] => That’s the trade-off with a narrowing spread. Rates may not be where you want them, but they're better than they could've been. If you want help figuring out what that means for your monthly payment, reach out to a local lender [kcm_ig_hashtags] => MortgageRates,HousingMarket,KeepingCurrentMatters [kcm_ig_quote] => Here’s why mortgage rates are what they are right now. [modified] => [poll] => [public_bottom_line] =>

That’s the trade-off with a narrowing spread. Rates may not be where you want them, but they're better than they could've been. If you want help figuring out what that means for your monthly payment, reach out to a local lender

[published_at] => 2026-08-12T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110567 [content_type] => must-share [title] => 8/12 Must Share ) ) [shares] => 0 [slug] => heres-why-mortgage-rates-are-what-they-are-right-now [status] => published [tags] => Array ( [0] => foundations [1] => exclude ) [title] => Here’s Why Mortgage Rates Are What They Are Right Now [updated_at] => 2026-08-11T18:24:42Z [url] => /2026/08/12/heres-why-mortgage-rates-are-what-they-are-right-now/ )

Here’s Why Mortgage Rates Are What They Are Right Now

If you're waiting for mortgage rates to fall a lot before you buy, you may be waiting a while.

12
stdClass Object
(
    [agents_bottom_line] => 

If you've been putting your home search on hold because you're convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy.

Let’s connect so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:20:58Z [id] => 325 [name] => Economy [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:04Z [slug] => economy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Economía ) ) [updated_at] => 2024-04-10T16:21:04Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:04Z [id] => 327 [name] => Forecasts [parent] => [parent_id] => [published_at] => 2024-04-10T16:22:19Z [slug] => forecasts [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Previsiones ) ) [updated_at] => 2024-04-10T16:22:19Z ) ) [content_type] => blog [contents] =>

Imagine waiting a year to buy a home, only to find mortgage rates haven't changed much. That may sound frustrating.But it's a real possibility.

A lot of people are putting their plans on hold because they believe much lower mortgage rates are right around the corner. But, based on today's forecasts, that may not happen. And you should know that before you decide what to do.

Let's look at why experts don't expect a dramatic drop in rates – and the options that could help you buy anyway. Because even if rates don’t fall, you can still move. Here’s how.

1. Mortgage Rates Aren’t Expected To Fall in a Meaningful Way

If you're waiting for rates to fall, you're not alone. A recent survey from Clever-Best Interest found 42% of people believe mortgage rates will drop below 5% this year.

The challenge is, that's not what the experts who study mortgage rates every day are expecting.

Forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo all show mortgage rates staying relatively steady in the low-to-mid 6% range through at least mid-2027 (see graph below):

a graph with numbers and lines

Why? Rates are influenced by inflation, the overall economy, Treasury yields, Federal Reserve policy, global events, and a lot of other moving pieces. And right now, those factors simply aren't pointing toward the kind of dramatic rate drop many buyers are waiting for.

Could rates move a little? Of course. But if you're holding out for a bigger drop, today's forecasts suggest you may be waiting a lot longer than you expect.

2. Inflation Is Still Elevated – And That’s Working Against Lower Rates 

One reason experts aren't expecting rates to fall much? Inflation. Generally speaking, high inflation is the enemy of lower mortgage rates.

And after a period of relative stability from mid 2023 to late 2025, recent data shows inflation has actually been trending higher lately (see graph below):

a graph of a number of people 

In other words, one of the biggest ingredients needed for much lower mortgage rates simply isn't in place today. That helps explain why experts aren't forecasting the kind of meaningful decline so many buyers are hoping for.

3. Today’s Rates Aren’t High, They’re "Normal"

And this may be the biggest mindset shift of all. The reality is, while today's rates may feel high compared to a few years ago, they're not high. They’re normal.

Historically, mortgage rates have spent the majority of their time somewhere between about 5% and 10%. And data from Freddie Mac shows we’re actually well in that range today. It just feels high because we all remember the ultra-low rates homeowners got during the pandemic (see graph below):

a graph of a graph showing the rise of a mortgage rate 

Now, this doesn't suddenly make a 6% mortgage feel exciting. But it does remind us that waiting for super low rates again may not be a realistic strategy.

So... What Should You Do Instead?

None of this is meant to convince you that you have to buy today. You don’t. But if you need to because something in your life’s changed, there are still ways to find better affordability without waiting for mortgage rates to fall.

  • Check out newly built homes. Many builders are offering incentives to attract buyers, including price cuts, potentially lower rates, free upgrades, and more.

  • Ask about an adjustable-rate mortgage (ARM). If you don't plan to stay in the home long-term, an ARM may offer a lower initial interest rate than a traditional 30-year fixed mortgage. It's not the right choice for everyone, but it's worth asking a lender if it fits your plans.

  • Look into mortgage rate buydowns. This is when you pay upfront to reduce your mortgage rate so you can get for a lower monthly payment without waiting for rates to fall.

  • Find out about assumable mortgages. An assumable mortgage allows you to take over the seller’s existing loan, including its lower mortgage rate.

The important thing is you shouldn’t assume waiting is your only option.

Talk with your real estate agent and lender about whether one of these strategies could be a good fit for you.

[created_at] => 2026-08-05T15:08:43Z [description] =>

Imagine waiting a year to buy a home, only to find mortgage rates haven't changed much. That may sound frustrating. But it's a real possibility.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260805/Header-Image-20221117-SG-original.png [id] => 110371 [kcm_ig_caption] => If you've been putting your home search on hold because you're convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy. Let’s connect so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer. [kcm_ig_hashtags] => HomeAffordability,MortgageRates,KeepingCurrentMatters [kcm_ig_quote] => Thinking about waiting for lower mortgage rates? Read this first. [modified] => [poll] => [public_bottom_line] =>

If you've been putting your home search on hold because you're convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy.

Connect with an agent or lender so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer.

[published_at] => 2026-08-06T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110372 [content_type] => must-share [title] => 8/6 Must Share ) ) [shares] => 0 [slug] => thinking-about-waiting-for-lower-mortgage-rates-read-this-first [status] => published [tags] => Array ( ) [title] => Thinking About Waiting for Lower Mortgage Rates? Read This First. [updated_at] => 2026-08-05T15:08:43Z [url] => /2026/08/06/thinking-about-waiting-for-lower-mortgage-rates-read-this-first/ )

Thinking About Waiting for Lower Mortgage Rates? Read This First.

Imagine waiting a year to buy a home, only to find mortgage rates haven't changed much. That may sound frustrating. But it's a real possibility.

13
stdClass Object
(
    [agents_bottom_line] => 

Big investors are stepping back, and they're adding homes to the market as they go. If you've been waiting for a better shot at buying, this could be it. Let’s connect so you can see what's popping up in our area. You may have more options than you think.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) ) [content_type] => blog [contents] =>

For years, a lot of would-be homebuyers have worried about the same thing. How do you compete with big investors who can swoop in, pay cash, and snap up the houses you want?

Well, worry a little less. Because right now, those big investors aren't buying up the market. They're backing out of it.

Investors Are Buying Fewer Homes Than They Have in Years

According to Redfin, investor home purchases just fell to their lowest level since 2020 – when the start of the pandemic temporarily caused pretty much all homebuying to pull way back. Before that, you'd have to go all the way back to 2016 to find a time when investors bought this few homes (see graph below):

a graph of sales in the fall

Why the step back? Two big reasons.

First, Washington passed a housing law that takes aim at large institutional investors. To be clear, these mega investors were never as big a part of the market as the headlines made it sound. They’ve always made up a relatively small slice of housing pie. But the law still targeted the largest ones, and it worked fast. According to Thom Malone, Principal Economist at Cotality:

“When Washington announced its intention to curb institutional investors’ homebuying, the market reacted. . . Cotality data shows that investment by mega investors who own 1,000 or more properties retracted almost instantly.”

Second, the housing market has cooled. Price growth has slowed in much of the country, and in some markets, prices are dipping. That makes the math a lot less appealing for investors betting on quick gains. Lance Lambert, CEO of ResiClub, explains:

“Ever since rates spiked and the Pandemic Housing Boom fizzled out in spring 2022, institutional single-family rental (SFR) operators have pulled way back from buying up homes on the resale market—the math just isn't as appealing right now. Home prices and rents are no longer ripping, holding costs (property taxes and insurance) have jumped, capital markets have shifted their attention elsewhere, and elevated materials prices make renovations expensive.”

They’re Not Just Buying Less – They’re Selling More

This is the part most people miss. Big investors aren't just slowing down their purchases. Data from Parcl Labs and ResiClub shows the largest institutional investors are now selling more homes than they're buying – and that gap is growing these past 4 quarters (see graph below):

a graph of a graph showing the price of a home sold

Every one of those homes goes right back into the market for buyers like you. And since big investors tend to own homes at the lower end of the price range, a lot of what they're selling is exactly the kind of home first-time buyers are looking for. As Malone puts it:

". . . this sudden dropoff in institutional investment is a signal to first-time homebuyers that there's an opening."

Less competition from deep-pocketed buyers. More homes hitting the market. And many of them at prices that work for a first purchase. That's a shift that works in your favor.

[created_at] => 2026-07-30T16:51:09Z [description] =>

For years, a lot of would-be homebuyers have worried about the same thing. How do you compete with big investors who can swoop in, pay cash, and snap up the houses you want?

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260730/Header-Image-Summer-2023-Guide-28--original.png [id] => 110206 [kcm_ig_caption] => Big investors are stepping back, and they're adding homes to the market as they go. If you've been waiting for a better shot at buying, this could be it. Let’s connect so you can see what's popping up in our area. You may have more options than you think. [kcm_ig_hashtags] => FirstTimeHomebuyer,HouseHunting,KeepingCurrentMatters [kcm_ig_quote] => Big investors are backing off and that’s your opening. [modified] => [poll] => [public_bottom_line] =>

Big investors are stepping back, and they're adding homes to the market as they go. If you've been waiting for a better shot at buying, this could be it. Connect with a local agent to find out what's popping up in your area. You may have more options than you think.

[published_at] => 2026-08-05T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110207 [content_type] => must-share [title] => 8/5 Must Share ) ) [shares] => 0 [slug] => big-investors-are-backing-off-and-thats-your-opening [status] => published [tags] => Array ( [0] => foundations ) [title] => Big Investors Are Backing Off and That’s Your Opening [updated_at] => 2026-07-30T16:51:09Z [url] => /2026/08/05/big-investors-are-backing-off-and-thats-your-opening/ )

Big Investors Are Backing Off and That’s Your Opening

For years, a lot of would-be homebuyers have worried about the same thing. How do you compete with big investors who can swoop in, pay cash, and snap up the houses you want?

14
stdClass Object
(
    [agents_bottom_line] => 

There's no one-size-fits-all answer to buying and selling at once. But for a lot of homeowners, leading with the sale makes moving easier on their mind and their wallet.

Let’s connect, so you can navigate selling and buying with more confidence, more financial power, and less stress.

[assets] => Array ( ) [can_share] => no [categories] => Array ( ) [content_type] => blog [contents] =>

If you're a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you start looking?

There's no single right answer. The best call depends on your finances, your local market, and your timeline. And a trusted agent can help you weigh all of it.

But in a lot of cases these days, selling first puts you in the stronger spot.

The Advantages of Selling First

Selling is usually the trickier half of a move today, so getting it done first clears your biggest hurdle. And that’s especially true right now, because there are more homes for sale than there are buyers, which means houses are taking longer to sell than they did a year or two ago.

So how does leading with your sale pay off? Let’s start with the money.

1. You Won’t Get Stuck Paying Two Mortgages

Buy before you sell, and you could end up carrying two mortgages at once. And especially since houses are staying on the market longer these days, that overlap may drag on for more time than you’d planned. And if unexpected repairs come up, it could get even more expensive.

Selling first takes that risk off the table, so you’re not multitasking homeownership. As Ramsey Solutions puts it:

"It's best to sell your old home before buying a new one to avoid unnecessary risks and possible headaches."

2. You Can Use Your Equity To Fuel Your Move

This is always true, but one of the biggest perks of selling first is that you’ll know exactly how much money you're walking away with. And one of the big figures that matters in that conversation is how much equity you have in your current place.

Equity is basically your house’s value minus what you still owe on your mortgage. And it adds up fast. According to Realtor.com, homeowners who’ve been in their home for 5 years have about $180,000 in equity on average. And those who’ve had their home for 6-10 years? They have over $340,000.

After you sell, you can use that money to cover your down payment or even buy your next home in cash. And knowing that profit up front helps you plan your next move.

3. Your Offer Will Be Hard To Pass Up

When your house is already sold, you don’t have to make your offer contingent on that sale. In a market where buyers are taking their time, that’s exactly what a seller wants to see.

Picture it from the seller’s side. If their house has been sitting for a while, they’ll gravitate toward the offer most likely to close without a snag.

That can also give you room to ask for a little more, like repairs, since a motivated seller would rather keep things moving than lose you and wait for another offer to come in. Your agent can help you make the most of your upper hand in that scenario.

Is There a Catch?

Selling first has its tradeoffs too, and it helps to see the pros and cons side by side before you decide. Here’s a quick breakdown based on information from Zillow (see visual below):

a screenshot of a video game 

The cons are manageable with the right plan, so talk about them with your agent. They can help you negotiate things like a rent-back, where you stay in your house for a set time after closing, or line up flexible closing dates to keep the transition smooth.

[created_at] => 2026-07-30T16:11:29Z [description] =>

If you're a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you start looking?

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260730/Header-Image-Summer-2023-Guide-13--original.png [id] => 110198 [kcm_ig_caption] => There's no one-size-fits-all answer to buying and selling at once. But for a lot of homeowners, leading with the sale makes moving easier on their mind and their wallet. Let’s connect, so you can navigate selling and buying with more confidence, more financial power, and less stress. [kcm_ig_hashtags] => SellYourHouse,HomeEquity,KeepingCurrentMatters [kcm_ig_quote] => Here’s where to start if you’re selling and buying at the same time. [modified] => [poll] => [public_bottom_line] =>

There's no one-size-fits-all answer to buying and selling at once. But for a lot of homeowners, leading with the sale makes moving easier on their mind and their wallet.

Connect with a local agent, and they’ll help you navigate selling and buying with more confidence, more financial power, and less stress.

[published_at] => 2026-08-03T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110200 [content_type] => must-share [title] => 8/3 Must Share ) ) [shares] => 0 [slug] => heres-where-to-start-if-youre-selling-and-buying-at-the-same-time [status] => published [tags] => Array ( ) [title] => Here’s Where To Start if You’re Selling and Buying at the Same Time [updated_at] => 2026-07-30T16:11:29Z [url] => /2026/08/03/heres-where-to-start-if-youre-selling-and-buying-at-the-same-time/ )

Here’s Where To Start if You’re Selling and Buying at the Same Time

If you're a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you start looking?

15
stdClass Object
(
    [agents_bottom_line] => 

Homeowners insurance has become a bigger part of the homebuying conversation. But it doesn't have to become a bigger source of stress.

The key is knowing what to expect before you buy. Get an insurance quote early, factor it into your budget, and lean on trusted local professionals to help you make the most informed decision possible.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

If buying a home is on your radar, you've probably been keeping an eye on mortgage rates and home prices. But don’t forget about homeowners insurance. 

Homeowners insurance has always been part of owning a home. But over the past few years, it's become a larger expense for many homeowners – something that's especially frustrating when affordability already feels tight.

The good news? While premiums are still rising, the latest data shows those increases are beginning to slow. Here's what buyers should know.

Home Insurance Costs Have Gone Up

You've probably heard stories from friends or family about their premiums going up. And that’s not really a surprise when you consider data from the Pew Research Center shows 71% of homeowners say their insurance costs have gone up over the past few years.

While no one likes rising costs, knowing what to expect can help you plan ahead. Your first insurance payment is typically included in your closing costs, but after that it'll become part of your monthly housing expenses.

Getting an insurance quote early can help you build a more realistic budget and avoid surprises later.

Premiums Are Rising, But Not as Fast as They Were

Most of the headlines focus on how home insurance is getting more expensive. And that's true. But here’s the part that’s easy to miss.

Insurance premiums are still rising.

But they're not rising as fast as they were.

According to the latest report from Rate Insurance, 2025 saw the first slowdown in annual premium increases since 2019 (see graph below):

a graph of insurance coverage 

That doesn't mean premiums are getting cheaper. It simply means the rapid increases of the past several years may finally be starting to ease – a small but welcome step in the right direction.

But what you’ll pay in one part of the country can look very different from what someone pays somewhere else.

Where You Buy Can Make a Big Difference

Insurance costs vary because some parts of the country experience more claims than others. That's why it's important to look at what's happening locally.

Your premium will depend on things like where you're buying, the home itself, and the coverage you choose.

Forbes data can give a rough idea of your state’s typical premiums. Check out the map below – the darker the blue, the higher the costs tend to be in that state:

a map of the united states

Ways To Lower Your Costs

While you can't control every cost that comes with buying a home, you can control how prepared you are. If you’re crunching the numbers and trying to find ways to save, Insurify and NerdWallet offer these tips that can help you get the best insurance price possible:

  • Shop Around – Compare quotes from multiple companies.

  • Bundle Policies – Combine home and auto to see if a bundle price is cheaper.

  • Ask If There Are Discounts – Don’t miss out on savings you may qualify for.

  • Highlight Upgrades – Features like a new roof or storm windows can cut costs.

  • Improve Your Credit – A stronger credit score can mean better premiums.

One of the smartest things you can do is get an insurance quote before you make an offer. That way, you'll know what your monthly housing costs are likely to be before you commit.

An insurance professional can walk you through your options and help you find coverage that fits both your needs and your budget.

[created_at] => 2026-07-28T18:06:11Z [description] =>

If buying a home is on your radar, you've probably been keeping an eye on mortgage rates and home prices. But don’t forget about homeowners insurance.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260728/Header-Image-pg-11-original.png [id] => 110120 [kcm_ig_caption] => Homeowners insurance has become a bigger part of the homebuying conversation. But it doesn't have to become a bigger source of stress. The key is knowing what to expect before you buy. Get an insurance quote early, factor it into your budget, and lean on trusted local professionals to help you make the most informed decision possible. [kcm_ig_hashtags] => HomeownersInsurance,HomeAffordability,KeepingCurrentMatters [kcm_ig_quote] => Buying a home? Here's what you should know about home insurance costs. [modified] => [poll] => [public_bottom_line] =>

Homeowners insurance has become a bigger part of the homebuying conversation. But it doesn't have to become a bigger source of stress.

The key is knowing what to expect before you buy. Get an insurance quote early, factor it into your budget, and lean on trusted local professionals to help you make the most informed decision possible.

[published_at] => 2026-07-30T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110126 [content_type] => must-share [title] => 7/30 Must Share ) ) [shares] => 0 [slug] => buying-a-home-heres-what-you-should-know-about-home-insurance-costs [status] => published [tags] => Array ( ) [title] => Buying a Home? Here's What You Should Know About Home Insurance Costs. [updated_at] => 2026-07-28T18:06:11Z [url] => /2026/07/30/buying-a-home-heres-what-you-should-know-about-home-insurance-costs/ )

Buying a Home? Here's What You Should Know About Home Insurance Costs.

If buying a home is on your radar, you've probably been keeping an eye on mortgage rates and home prices. But don’t forget about homeowners insurance.

16
stdClass Object
(
    [agents_bottom_line] => 

Home price growth slowed way down, and now it's showing early signs of picking back up. Whether you're buying or selling, let's connect so you can see exactly what prices are doing in our local market and what that means for your plans.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) ) [content_type] => blog [contents] =>

After more than a year of headlines talking about how home prices are going to crash, the latest data shows that price growth may be starting to pick back up again. And depending on whether you’re buying or selling, that shift means something different for you.

The Numbers May Be Starting To Turn

For the past couple of years, home price growth has been moderating – cooling from around 7% in mid-2024, according to Redfin (see graph below). But look at the right side of that graph. The pace of that growth appears to have hit its low point and started to turn.

a graph of growth in a number of years

While a couple months of data doesn’t necessarily mean this will be a lasting trend, there are some other signs that this could continue.

For example, fewer markets are seeing prices decline. According to ResiClub and Zillow, about 36% of the 300 largest housing markets had falling prices as of the middle of last year. Since the start of this year, that share has been shrinking. Now? Only 23% are experiencing those mild dips (see graph below):

a graph of the price of a house

When fewer markets see prices falling, that means more markets are seeing prices rise again.

And forecasts suggest this shift has room to run. On average, experts project home prices will rise about 2.3% nationally this year. And for that to happen, price growth would have to pick up a bit in the second half of 2026.

But Remember, Real Estate Is Local

While it looks like national prices may be starting to pick back up a tiny bit, that doesn’t mean that’s what’s happening in your neighborhood.

National home prices are really just an average of hundreds of local markets. Some are climbing faster. Others are still cooling. But one reason the national average may be looking up is because a growing number of metros may actually be net positive for prices this year.

Not long ago, the major metros were split about 50/50 – half seeing prices rise and half seeing them fall. Now, that balance looks like it’s starting to tip in a more positive direction. Just last month, more than half of the major metros saw prices go up, according to Redfin (see graph below):

a graph of prices on a dark background

As Selma Hepp, Chief Economist at Cotality, explains:

“. . . local markets continue to tell very different stories. Annual home price growth has changed little since the start of the year, but some markets, especially those supported by strong job and income growth in the West and more affordable Midwest markets, have seen notable acceleration in price gains.”

What This Means for You

Home price headlines can be confusing because they don’t always tell the full picture. Lean on an agent to understand what’s happening in your local market and what the early signs say for where prices may go from here.

That’s the best way to stay one step ahead of the market.

If you're buying: slower price growth has worked in your favor. You've had more room to negotiate and a budget you could plan around. If price growth is picking up in your area, buying now may mean paying less than you would later this year.

If you own a home: you've been gaining equity all along, even while growth moderated. If growth keeps picking up, those gains could speed up, too. Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), projects the typical homeowner will gain roughly $16,000 in housing wealth this year. And if you're thinking about selling, this shift is a good early sign for you. Just remember, the market is still pretty balanced and buyer-friendly in a lot of areas right now.

Home price growth slowed way down, and now it's showing early signs of picking back up. Whether you're buying or selling, let's connect so you can see exactly what prices are doing in our local market and what that means for your plans.

[created_at] => 2026-07-28T18:51:24Z [description] =>

After more than a year of headlines talking about how home prices are going to crash, the latest data shows that price growth may be starting to pick back up again.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260728/Header-Image-20230103-Blog-original.png [id] => 110129 [kcm_ig_caption] => Home price growth slowed way down, and now it's showing early signs of picking back up. Whether you're buying or selling, let's connect so you can see exactly what prices are doing in our local market and what that means for your plans. [kcm_ig_hashtags] => HousingMarket,HomePrices,KeepingCurrentMatters [kcm_ig_quote] => Home price growth slowed down. That may be changing. [modified] => [poll] => [public_bottom_line] =>

Home price growth slowed way down, and now it's showing early signs of picking back up. Whether you're buying or selling, connect with a local real estate agent so you can see exactly what prices are doing in your local market and what that means for your plans.

[published_at] => 2026-07-29T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 110130 [content_type] => must-share [title] => 7/29 Must Share ) ) [shares] => 0 [slug] => home-price-growth-slowed-down-that-may-be-changing [status] => published [tags] => Array ( [0] => foundations ) [title] => Home Price Growth Slowed Down. That May Be Changing. [updated_at] => 2026-07-28T18:51:24Z [url] => /2026/07/29/home-price-growth-slowed-down-that-may-be-changing/ )

Home Price Growth Slowed Down. That May Be Changing.

After more than a year of headlines talking about how home prices are going to crash, the latest data shows that price growth may be starting to pick back up again.

17
stdClass Object
(
    [agents_bottom_line] => 

Moving is both a personal milestone and an investment in your community. So, if the time is right for you, let's connect. You'll make a difference for more people than you know.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:20:58Z [id] => 325 [name] => Economy [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:04Z [slug] => economy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Economía ) ) [updated_at] => 2024-04-10T16:21:04Z ) ) [content_type] => blog [contents] =>

Buying or selling a home is a big financial decision. And right now, it feels even bigger. Inflation is high, costs are high, and you want to be sure the timing is right before you make your move. 

But if you do decide to go for it, whether you're buying or selling, here's something reassuring to hold onto. Not only does your move change your own life, but it also gives your whole community a boost.

Real estate is a huge part of the economy. In 2025, it added up to about $5.6 trillion, according to the National Association of Realtors (NAR). A good share of that comes from everyday people buying and selling homes, just like you.

Your Move Puts Real Money Into the Local Economy

Every sale sends money flowing through your area. NAR data shows that buying an existing home (one that's already been lived in) adds about $64,000 to the local economy. Buy a newly built home, and that number climbs to more than $134,000 (see graph below):

a diagram of a home sale

Over half of that comes from the work of building the home itself. The rest flows to real estate services, like agent and lender fees, plus what you spend settling in afterward, on things like furniture and remodeling.

And the money doesn't stop there. As local businesses earn it, they spend it again in your area, so a single sale ripples further than the sale price alone.

One Sale Keeps a Lot of People Working

Behind every sale is a whole network of people doing their jobs. Contractors, lenders, inspectors, movers, and more. When you buy or sell, you help keep them busy. Lawrence Yun, Chief Economist at NAR, puts it this way:

"Increased home sales mean more economic activity — lawn care, furniture purchases, moving services, mortgage originations and other related business activities all get a boost."

So, your move supports your neighbors' livelihoods, too. The deal that gets you into your next home also helps a local crew make payroll. In a year when every paycheck counts, that's no small thing.

Your Local Impact May Be Even Bigger

What your move financially adds to your community depends a lot on where you live. To help you see how it can vary, here’s a look at the impact of a typical newly built home sale by state.

The national average for a newly built home is about $134,000, but some states see far more (see map below):

a map of the united states

In California, a single sale adds more than $300,000 to the local economy. In Hawaii, it's over $350,000. Even in the most affordable states, the number lands in the tens of thousands.

Want to know what a move would mean where you live? A local agent can show you the figure close to home.

[created_at] => 2026-07-01T20:59:06Z [description] =>

Buying or selling a home is a big financial decision. And right now, it feels even bigger.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260701/Header-Image-GettyImages-595504906-original.png [id] => 109423 [kcm_ig_caption] => Moving is both a personal milestone and an investment in your community. So, if the time is right for you, let's connect. You'll make a difference for more people than you know. [kcm_ig_hashtags] => HomeBuying,SellYourHouse,KeepingCurrentMatters [kcm_ig_quote] => Here's what buying or selling a home gives back to your community. [modified] => [poll] => [public_bottom_line] =>

Moving is both a personal milestone and an investment in your community. So, if the time is right for you, connect with a local agent. You'll make a difference for more people than you know.

[published_at] => 2026-07-06T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 109424 [content_type] => must-share [title] => 7/6 Must Share ) ) [shares] => 0 [slug] => what-buying-or-selling-a-home-gives-back-to-your-community [status] => published [tags] => Array ( ) [title] => What Buying or Selling a Home Gives Back to Your Community [updated_at] => 2026-07-01T20:59:06Z [url] => /2026/07/06/what-buying-or-selling-a-home-gives-back-to-your-community/ )

What Buying or Selling a Home Gives Back to Your Community

Buying or selling a home is a big financial decision. And right now, it feels even bigger.

18
stdClass Object
(
    [agents_bottom_line] => 

A house sitting on the market isn’t always a glaring red flag. In today’s market, it may be your best opportunity yet.

For help deciding which lingering listings are actually worth a second look, let’s connect.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

Open up a home search and you'll see them. Listings that have been on the market for two months. Three. Some longer.

Most buyers scroll right past them, assuming something’s wrong with the house. But that instinct could be costing you, since the longer a home sits, the more motivated the seller usually gets.

Where Some Buyers Are Finding Better Deals

If affordability has been your #1 hurdle to buying, here’s a surprisingly simple strategy that could help you finally get your foot in the door. Start with the homes that have been sitting the longest. That’s often where the best deals are.

Here’s why. Data from Realtor.com shows there’s a connection between longer time on the market and lower sales prices. Basically, the longer a house sits, the more likely it is that the seller will reduce the price (see graph below):

a graph with numbers and lines

The blue line tracks how long homes stay on the market, while the green line tracks the share of homes getting a price reduction. As one climbs, so does the other.  

And if you focus on these homes that are just sitting and waiting, the opportunity for you is bigger than you may think right now.

Redfin data shows there’s $347 billion worth of stale listings on the market right now – more than ever before for this time of year. So, ask your agent to filter listings for you from oldest to newest. The home that fits your budget might already be there. Just further down the list than you thought.

Lingering Doesn’t Always Mean Something’s Wrong 

Let’s say you do that and something catches your eye. Still, you might be questioning why the home has been sitting in the first place. Just remember, sometimes it has nothing to do with the home itself.

According to Redfin, common causes are:

  • The asking price was set too high to start

  • The home didn’t show well online

  • There are a lot of homes for sale in the area, so it just got buried

So, nothing that’s necessarily a dealbreaker, or even anything that’s wrong with the home itself. If there’s a real issue, a thorough inspection will surface it. And that’s information you can use to negotiate. Not a reason to assume it’s a house worth skipping over.

How To Turn a Lingering Listing into a Win

So how do you capitalize on a lingering listing? According to USA Today, you have two main levers to pull.

The first is price. Work with your agent to study what comparable homes recently sold for, then build an offer around that. Coming in below asking price is fair game when a home has been sitting.

The second is concessions. If a seller won’t budge much on price, they may still help in other ways, like covering some closing costs, repair credits, or even a mortgage rate buydown that lowers your monthly payment.

A local agent has the context to tell which homes are the real opportunities and which are skippable.

[created_at] => 2026-06-16T17:32:00Z [description] =>

Open up a home search and you'll see them. Listings that have been on the market for two months. Three. Some longer.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260616/Header-Image-Summer-2023-Guide-30--original.png [id] => 108966 [kcm_ig_caption] => A house sitting on the market isn’t always a glaring red flag. In today’s market, it may be your best opportunity yet. For help deciding which lingering listings are actually worth a second look, let’s connect. [kcm_ig_hashtags] => Homebuying,HomebuyingTips,KeepingCurrentMatters [kcm_ig_quote] => That house that’s been sitting could be your best shot at a deal. [modified] => [poll] => [public_bottom_line] =>

A house sitting on the market isn’t always a glaring red flag. In today’s market, it may be your best opportunity yet.

For help deciding which lingering listings are actually worth a second look, connect with a local real estate agent.

[published_at] => 2026-06-22T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 108967 [content_type] => must-share [title] => 6/22 Must Share ) ) [shares] => 0 [slug] => that-house-thats-been-sitting-could-be-your-best-shot-at-a-deal [status] => published [tags] => Array ( ) [title] => That House That’s Been Sitting Could Be Your Best Shot at a Deal [updated_at] => 2026-06-16T17:32:01Z [url] => /2026/06/22/that-house-thats-been-sitting-could-be-your-best-shot-at-a-deal/ )

That House That’s Been Sitting Could Be Your Best Shot at a Deal

Open up a home search and you'll see them. Listings that have been on the market for two months. Three. Some longer.

19
stdClass Object
(
    [agents_bottom_line] => 

The sellers having the most success today are the ones who understand the market has changed and are adapting to meet it where it is.

Sometimes that means negotiating on closing costs. Sometimes it means offering something else. The key is knowing which concessions are worth it for our local market.

If you’re wondering what's normal in our area, what's worth negotiating, and where it makes sense to stand firm, let’s connect.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:53Z [id] => 328 [name] => Selling Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:23:13Z [slug] => selling-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de venta ) ) [updated_at] => 2024-04-10T16:23:13Z ) ) [content_type] => blog [contents] =>

A few years ago, sellers could get away with saying "no" to just about everything.

No repairs.

No concessions.

No negotiation.

If buyers wanted the house, they pretty much had to take it on the seller's terms. But now that inventory’s grown, negotiations are becoming a normal part of the process again.

That's why one of the most important things sellers need to understand right now is this:

The goal isn't to “win” every negotiation.

Sometimes, it’s worth meeting buyers where they are to get a deal done, fast. One example? Helping with a buyer's closing costs.

Let’s break that down, so you know what to expect if it comes up in your sale.

What Are Buyer Closing Costs?

Closing costs are the extra expenses buyers pay on top of their down payment when they purchase a home. Freddie Mac gives some examples:

  • Loan origination fees

  • Appraisal and inspection costs

  • Title and attorney fees

  • Survey fees and more

Typically, buyer closing costs range from about 2% to 5% of the home’s purchase price. So, on the typical $400,000 home, that could mean anywhere from $8,000 to $20,000 out of pocket.

And in today’s affordability-challenged market, that upfront cash can be a major hurdle for some buyers – even if they can comfortably afford the monthly mortgage payment itself. 

That’s why more people are asking sellers for help.

And More Sellers Are Saying “Yes”

According to the latest data from Zillow, 67% of sellers reported paying some or all of the buyer’s closing costs in 2025 (see chart below):

a blue circle with white text

Now, that doesn't mean every seller is doing it. And it definitely doesn't mean every seller should. But it does show how common concessions have become as the market has shifted. And that’s important for you to know.

When Paying Closing Costs May Make Sense

This is where many sellers get stuck. They hear "help with closing costs" and immediately think: "Why should I pay for their expenses?"

But that's not always the right way to look at it. You’ve got to consider who has the leverage in today’s market.

Redfin data shows there are more sellers than buyers active today. And that shifts the market dynamics (see graph below):

a graph of sales and buyers

That doesn't mean every market favors buyers. Far from it. In some areas, homes are still selling quickly and sellers have plenty of leverage. But in others, buyers have more room to negotiate than they've had in years.

That's why local market conditions matter so much when you make your decision.

For example, helping with closing costs may be worth considering if:

  • There are a lot of homes for sale in your area

  • Your house has been sitting on the market longer than expected

  • You’ve had showings, but no offers

  • You’re motivated to move quickly

  • Or you’re trying to keep a deal together during negotiations

After all, if it’s the thing that helps bring a serious buyer across the finish line, it could be well worth it.

Other Concessions You Could Offer Instead

Just remember, being flexible doesn’t mean saying “yes” to every request.  It means understanding which compromises actually help you accomplish your goals. Because there are always alternatives.

Redfin suggests considering other concessions if you’re not interested in helping with closing costs, like:

  • A home warranty

  • Repair credits

  • Flexible closing dates, or

  • Leave behind appliances or furniture

The right answer depends on what buyers in your market are asking for and what matters most to you. That's exactly why working with an experienced local agent is so important.

[created_at] => 2026-06-04T16:55:05Z [description] =>

A few years ago, sellers could get away with saying "no" to just about everything.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260604/Header-Image-GettyImages-1706263420-original.png [id] => 108656 [kcm_ig_caption] => The sellers having the most success today are the ones who understand the market has changed and are adapting to meet it where it is. Sometimes that means negotiating on closing costs. Sometimes it means offering something else. The key is knowing which concessions are worth it for our local market. If you’re wondering what's normal in our area, what's worth negotiating, and where it makes sense to stand firm, let’s connect. [kcm_ig_hashtags] => HomeSellingTips,SellerConcessions,KeepingCurrentMatters [kcm_ig_quote] => Should you pay for your buyer’s closing costs? Here's what sellers need to know. [modified] => [poll] => [public_bottom_line] =>

The sellers having the most success today are the ones who understand the market has changed and are adapting to meet it where it is.

Sometimes that means negotiating on closing costs. Sometimes it means offering something else. The key is knowing which concessions are worth it for your local market.

If you’re wondering what's normal in your area, what's worth negotiating, and where it makes sense to stand firm, connect with an agent.

[published_at] => 2026-06-15T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 108657 [content_type] => must-share [title] => 6/15 Must Share ) ) [shares] => 0 [slug] => should-you-pay-for-your-buyers-closing-costs-what-sellers-need-to-know [status] => published [tags] => Array ( ) [title] => Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know. [updated_at] => 2026-06-04T16:55:05Z [url] => /2026/06/15/should-you-pay-for-your-buyers-closing-costs-what-sellers-need-to-know/ )

Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know.

A few years ago, sellers could get away with saying "no" to just about everything.

20
stdClass Object
(
    [agents_bottom_line] => 

If affordability has been your top concern, the recent dip in prices is an opening. Want to see what that looks like in our area? Let’s connect.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

If affordability has been the biggest thing standing between you and a home, there's a little good news. 

Asking prices have started to come down.

The typical seller listed their house for a median of $429,500 in May. That’s 2.4% lower than a year ago, according to Realtor.com. On its own, that won't transform what you can afford, but in today’s market every little bit helps and it signals a broader shift taking place.

Buyers Are Finally Catching a Break

Check out this data from Realtor.com and you can see this is the first May in years where buyers have caught any sort of break price-wise.

Each May from 2022-2025, things held pretty steady. But this year? You can see that more noticeable shift in your favor (see graph below):

a graph of sales in different colors

While the dip from $440,000 to $429,500 isn’t a big one, it gives you more breathing room. And that’s not a small thing when affordability has been this tough.

Now, lower asking prices don’t mean every home is suddenly within your range. But they do show buyers are gaining a little ground.

And in today’s market, a little ground can go a long way. 

What That Means for the Housing Market

And just in case this crossed your mind, this is good news for your move, not bad news for the market as a whole.

The subtle dip from last May to this one shows prices are easing, but they’re not dropping off a cliff. What this is actually a sign of is that the market’s rebalancing now that the number of homes for sale has grown.

Buyers have a bit more power again, and sellers know they can't name just any price and expect their house to sell. They either meet the market where it is, or face a price cut later. And in general, sellers would rather avoid a price cut. As the New York Post explains:

"Rather than swinging for the fences with pandemic-era price tags, sellers are increasingly coming to terms with a new reality. The share of listings featuring price cuts actually fell to 17.5% in May, suggesting homeowners are doing their homework before putting up a “For Sale” sign instead of chasing unrealistic numbers and cutting later."

This signals a broader change in the market.

Seller expectations have been skewed a little high since the pandemic buying frenzy – you've probably felt that firsthand. But now, things are starting to normalize. It could mean less back-and-forth to land on a fair number. And homes should be priced a bit more realistically from the start.

[created_at] => 2026-06-09T06:25:03Z [description] =>

If affordability has been the biggest thing standing between you and a home, there's a little good news.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260609/Header-Image-GettyImages-83802508-original.png [id] => 108772 [kcm_ig_caption] => If affordability has been your top concern, the recent dip in prices is an opening. Want to see what that looks like in our area? Let’s connect. [kcm_ig_hashtags] => Homebuying,HomePrices,KeepingCurrentMatters [kcm_ig_quote] => Lower asking prices are a win for today’s buyers. [modified] => [poll] => [public_bottom_line] =>

If affordability has been your top concern, the recent dip in prices is an opening. Connect with a local real estate agent to see what that looks like in your area.

[published_at] => 2026-06-10T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 108773 [content_type] => must-share [title] => 6/10 Must Share ) ) [shares] => 0 [slug] => lower-asking-prices-are-a-win-for-todays-buyers [status] => published [tags] => Array ( [0] => foundations ) [title] => Lower Asking Prices Are a Win for Today’s Buyers [updated_at] => 2026-06-09T06:25:03Z [url] => /2026/06/10/lower-asking-prices-are-a-win-for-todays-buyers/ )

Lower Asking Prices Are a Win for Today’s Buyers

If affordability has been the biggest thing standing between you and a home, there's a little good news.

21
stdClass Object
(
    [agents_bottom_line] => 

The housing market hasn’t rebounded as quickly as experts originally hoped. But that doesn’t mean it’s stalled.

Higher inflation and lingering economic uncertainty caused economists to revise their forecasts for this year. But importantly, when those two things settle down, many experts believe the market will regain its momentum.

So don’t see this revision in forecasts as a sign of trouble. See it as a temporary reaction to overall conditions and uncertainty.

If you want to know what’s happening in our local market, and what it could mean for your plans for the rest of this year, let’s connect.

[assets] => Array ( ) [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 6 [name] => For Sellers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => sellers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los vendedores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:20:58Z [id] => 325 [name] => Economy [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:04Z [slug] => economy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Economía ) ) [updated_at] => 2024-04-10T16:21:04Z ) [5] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:22:04Z [id] => 327 [name] => Forecasts [parent] => [parent_id] => [published_at] => 2024-04-10T16:22:19Z [slug] => forecasts [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Previsiones ) ) [updated_at] => 2024-04-10T16:22:19Z ) ) [content_type] => blog [contents] =>

If the housing market feels confusing right now, you’re not alone.

Mortgage rates have risen. Home sales haven't picked up like expected. And many buyers and sellers are wondering when things are going to feel easier or be more affordable.

The truth is: a lot changed over the first half of this year.

Back at the end of 2025, economists were forecasting a much stronger housing market for 2026. They expected mortgage rates to come down, affordability to improve more dramatically, and home sales to rebound.

But lingering inflation, economic uncertainty, and growing geopolitical tensions overseas pushed mortgage rates higher than expected. And because rates stayed elevated for longer, many buyers continued to hold off.

That’s why experts recently revised their housing forecasts for the rest of the year (see graph below):

a graph of sales and sales

So, what does this actually mean for you? Let’s break it down.

Mortgage Rates May Remain Elevated

While just about everyone wants mortgage rates to go back to the uppers 5s or low 6s we saw at the start of the year, as of right now, the experts don’t think that’s likely to happen this year.

Instead, forecasts have been updated from the low 6s they originally projected. Many industry organizations are saying rates will stay in roughly the mid 6s this year. The good news is, that’s still lower than rates were a year ago.

Of course, this is based on what we know today. If the conflict overseas comes to an end or inflation drops, this could change. But if you’re waiting for lower rates, it may not pay off in the way you expect.

Existing Home Sales Revised Lower

Back in late 2025, experts expected we’d sell an average of 4.5 million homes this year. Now? That’s dropped down a bit to 4.2 million.

That tells us something important: buyers are still hesitant because affordability remains challenging.

Higher mortgage rates have made monthly payments harder to manage, especially for first-time buyers. And that’s slowed the pace of the market compared to what was originally expected. But even though the forecast was revised down, we’re still expected to sell more homes than last year. 

Once geopolitical tensions resolve and rates begin to settle down, many experts believe that group of buyers will be ready to jump back in. As Lawrence Yun, Chief Economist at NAR, explains:

“There is sizable pent-up demand that could be released into the market.”

There has already been a few glimmers of renewed hope lately. In recent months, pending homes sale have been improving month-over-month despite higher rates.

So, if you’re able to afford a home at today’s rates, it could still make sense to buy now. Because otherwise, if you wait, you’ll have more competition (and potentially fewer homes to choose from) when those others buyers jump back in.

New Home Sales Also Slowed

Builders also expected to have a stronger year. Earlier forecasts projected new home sales would top 700k in 2026. Now, economists expect we'll be just shy of that number.

Again, mortgage rates are a major reason why.

But the upside for buyers is that builders may be even more motivated to sell. That means builder incentives, negotiation opportunities, and pricing flexibility may continue in many markets. So, if you live somewhere where there’s more new construction, this may actually be a bright spot for you.

Builders could be more ready to negotiate, and that gives you more leverage to get a better deal.

Home Prices Are Still Expected To Rise

This is one of the most important takeaways from the entire forecast. Even though sales activity is slower, on average, experts did not revise their home price forecast downward.

They still expect prices to rise nationally this year.

Why? Because while buyer demand has softened, the number of homes for sale is still relatively limited overall. That imbalance is helping support prices, even in a slower market.

Of course, conditions vary depending on where you live. Some markets are cooling more than others. But nationally, experts are still projecting steady price growth — not a major decline. And that should be a comfort whether you’re buying or selling.

Because sellers don’t want a major drop in prices. And while buyers may think they do, generally you feel better about a big purchase when it doesn’t depreciate right away.

[created_at] => 2026-06-02T19:06:32Z [description] =>

If the housing market feels confusing right now, you’re not alone.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260602/Header-Image-GettyImages-1393815299-original.png [id] => 108573 [kcm_ig_caption] => The housing market hasn’t rebounded as quickly as experts originally hoped. But that doesn’t mean it’s stalled. Higher inflation and lingering economic uncertainty caused economists to revise their forecasts for this year. But importantly, when those two things settle down, many experts believe the market will regain its momentum. So don’t see this revision in forecasts as a sign of trouble. See it as a temporary reaction to overall conditions and uncertainty. If you want to know what’s happening in our local market, and what it could mean for your plans for the rest of this year, let’s connect. [kcm_ig_hashtags] => HousingMarketForecasts,HousingMarketUpdate,KeepingCurrentMatters [kcm_ig_quote] => The mid-year housing market update: why forecasts changed in 2026. [modified] => [poll] => [public_bottom_line] =>

The housing market hasn’t rebounded as quickly as experts originally hoped. But that doesn’t mean it’s stalled.

Higher inflation and lingering economic uncertainty caused economists to revise their forecasts for this year. But importantly, when those two things settle down, many experts believe the market will regain its momentum.

So don’t see this revision in forecasts as a sign of trouble. See it as a temporary reaction to overall conditions and uncertainty.

If you want to know what’s happening in your local market, and what it could mean for your plans for the rest of this year, talk to a local agent.

[published_at] => 2026-06-03T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 108576 [content_type] => must-share [title] => 6/3 Must Share ) ) [shares] => 0 [slug] => the-mid-year-housing-market-update-why-forecasts-changed-in [status] => published [tags] => Array ( [0] => foundations [1] => exclude ) [title] => The Mid-Year Housing Market Update: Why Forecasts Changed in 2026 [updated_at] => 2026-06-02T19:06:32Z [url] => /2026/06/03/the-mid-year-housing-market-update-why-forecasts-changed-in/ )

The Mid-Year Housing Market Update: Why Forecasts Changed in 2026

If the housing market feels confusing right now, you’re not alone.

22
stdClass Object
(
    [agents_bottom_line] => 

Builder incentives and lower new home prices are working to your advantage in a way they haven't in years. Want to see what's available in your area and what kind of deal a builder may be willing to make? Let's connect.

[assets] => Array ( ) [banner_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260527/STM-Banner-GettyImages-1765760671-original.jpg [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 45 [name] => New Construction [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => new-construction [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Nueva construcción ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:18:37Z [id] => 322 [name] => Affordability [parent] => [parent_id] => [published_at] => 2024-04-10T16:18:45Z [slug] => affordability [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Asequibilidad ) ) [updated_at] => 2024-04-10T16:18:45Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:19:38Z [id] => 323 [name] => Buying Tips [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:44Z [slug] => buying-tips [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Consejos de compra ) ) [updated_at] => 2024-04-10T16:19:44Z ) ) [content_type] => blog [contents] =>

If you’ve always assumed a newly built home is just not in your budget, you should know the math just got a little friendlier.

The median sale price of a newly built home is now at its lowest level since 2021, according to the latest data from the Census. And on top of that, builders are still rolling out incentives to bring buyers through the door.

Here's what's happening, and what it means if you're shopping right now.

Prices on Newly Built Homes Have Come Down

After a steep climb during the pandemic years, prices have eased a bit. The median sale price of newly built homes is sitting at about $390,000. That’s the lowest it's been in nearly five years (see graph below):

a graph of a home pricesWhile local markets vary, the national trend is moving in your favor, especially if you’re a first-time buyer. According to Zonda, prices in the entry-level price range have dropped roughly 2.7% over the past 12 months – more than any other price tier.

That doesn't mean every home in every market is suddenly affordable. But it does mean that, broadly, you’ll see the best prices on new builds since 2021, if you’re buying now.

Why This Isn’t a Repeat of 2008

And just in case you’re thinking it, lower prices don't mean the new home market is in trouble. Builders today are being intentional about how much inventory they have, so it doesn't pile up the way it did in 2008.

If you look back up at the graph, you’ll see that even after the recent improvement in new home prices, they’re still higher than pre-pandemic norms. So, this isn’t a crash. It’s a builder strategy to keep inventory moving.

Homebuilders Are Still Sweetening the Deal

Lower sticker prices aren't the only break buyers are getting. According to the National Association of Home Builders (NAHB), 60% of builders are currently offering some form of incentive to attract buyers. Those typically include:

  • Help with closing costs: Some builders are covering thousands of dollars in fees to reduce the upfront cost of buying.

  • Extra upgrades: Think premium finishes, appliance packages, and designer features, often added at no extra cost.

  • Mortgage rate buydowns: When the builder pays to lower your mortgage rate, which reduces your monthly payment.

  • Price cuts: Over one in three builders (36%) are cutting prices right now, averaging about 5% off list price (see graph below):

a blue and grey pie chartThat last point catches a lot of buyers off guard – most assume that builders won’t budge on price.

But builders need to move what they've built. That's a different mindset than a homeowner deciding whether to budge on price. So, you may find they’re more open to adjusting the price than you’d think. As Joel Berner, Senior Economist at Realtor.com, puts it:

". . . many existing-home sellers resort to taking down their listing instead of taking less than their desired price, but builders are more motivated to sell their inventory than owner-occupants . ."

[created_at] => 2026-05-14T05:57:35Z [description] =>

If you’ve always assumed a newly built home is just not in your budget, you should know the math just got a little friendlier.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260514/Header-Image-GettyImages-1765760671-original.png [id] => 107879 [kcm_ig_caption] => Builder incentives and lower new home prices are working to your advantage in a way they haven't in years. Want to see what's available in your area and what kind of deal a builder may be willing to make? Let's connect. [kcm_ig_hashtags] => Homebuying ,NewHome ,KeepingCurrentMatters [kcm_ig_quote] => Newly built home prices hit a 5-year low. [modified] => [poll] => [public_bottom_line] =>

Builder incentives and lower new home prices are working to your advantage in a way they haven't in years. Connect with a local real estate agent to see what's available in your area and what kind of deal a builder may be willing to make.

[published_at] => 2026-05-21T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 107880 [content_type] => must-share [title] => 5/21 Must Share ) ) [shares] => 0 [slug] => newly-built-home-prices-hit-a-5-year-low [status] => published [tags] => Array ( ) [title] => Newly Built Home Prices Hit a 5-Year Low [updated_at] => 2026-05-14T06:04:15Z [url] => /2026/05/21/newly-built-home-prices-hit-a-5-year-low/ )

Newly Built Home Prices Hit a 5-Year Low

If you’ve always assumed a newly built home is just not in your budget, you should know the math just got a little friendlier.

23
stdClass Object
(
    [agents_bottom_line] => 

Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment.

That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while.

But if you’re interested, let this reassure you. If you want to talk through what home prices are doing in our market, your goals, or your timelines, let’s have a quick conversation.

[assets] => Array ( ) [banner_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260527/STM-Banner-20230123-Blog-original.jpg [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 11 [name] => First-Time Buyers [parent] => [parent_id] => [published_at] => 2024-04-10T15:59:33Z [slug] => first-time-buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Compradores de vivienda por primera vez ) ) [updated_at] => 2024-04-10T15:59:33Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 53 [name] => Rent vs. Buy [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => rent-vs-buy [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Alquilar Vs. Comprar ) ) [updated_at] => 2019-06-03T18:18:43Z ) [4] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:21:25Z [id] => 326 [name] => Equity [parent] => [parent_id] => [published_at] => 2024-04-10T16:21:42Z [slug] => equity [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Equidad ) ) [updated_at] => 2024-04-10T16:21:42Z ) ) [content_type] => blog [contents] =>

It’s one of the biggest hold ups some buyers have right now: “What if I buy, and home prices go down?”

With everything in the news, that concern makes some sense. No one wants to make a big financial decision at the wrong time. But here’s what’s important to know. You don’t want to get hung up on the few places seeing slight declines right now.

When you zoom out and look at the full picture, home prices usually rise over time.

What the Data Really Shows

Take a look at the visual below. It uses data from Case-Shiller and Bilello to show how home prices have changed year by year going all the way back to the 1950s.

Here’s the key takeaway.

Outside of the housing crash, home prices have either held steady or increased in just about every year for decades (see visual below):

a chart of percentages and numbersThat’s a remarkably consistent track record. And it shows something a lot of headlines miss.

While short-term shifts can happen, it’s the long-term gains that really matter.

Why Prices Tend To Rise Over Time

There are a few core reasons prices usually go up each year:

  • There are always people who need to move. People need a place to live, and that demand will never fully go away. It may ebb and flow, but someone will always have to move as big changes happen in their life. So, homes stay in demand.
  • There still aren't enough homes for sale. While the number of homes for sale has grown, nationally there’s still an undersupply based on how many people want a home. That keeps upward pressure on prices.
  • Inflation has an impact. Over time, the cost of goods (including homes) naturally increases. That pushes home values higher.

What That Means for You as a Buyer

It’s easy to get caught up in what might happen with home prices next month or next year, especially if you’re a first-time buyer and you’re feeling a little anxious about making such a big financial commitment. But the big picture is clear. Prices usually rise.

That doesn’t mean prices will go up every single year in every market. Real estate is local, and there can be short-term ups and downs. We’re seeing that in some places right now. You can even see it in the few annual dips in the visual above.

But historically, the declines have been temporary.

That’s why it’s generally recommended to buy a home only if you plan to stay for a while – typically at least five years. That’s normally enough time to see your house grow in value. And, it’s enough so you can ride out any short-term changes in the market.

Because when you can do that, something powerful happens. Those rising home values grow your net worth, and by extension, help you build wealth.

The right decision isn’t about timing the market perfectly. It’s about making a move that works for your life and staying in it long enough to benefit from the bigger trend.

[created_at] => 2026-05-13T21:50:44Z [description] =>

It’s one of the biggest hold ups some buyers have right now: “What if I buy, and home prices go down?”

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260513/Header-Image-20230123-Blog-original.png [id] => 107868 [kcm_ig_caption] => Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment. That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while. But if you’re interested, let this reassure you. If you want to talk through what home prices are doing in our market, your goals, or your timelines, let’s have a quick conversation. [kcm_ig_hashtags] => Homebuying ,HomePrices,KeepingCurrentMatters [kcm_ig_quote] => Are home prices going to fall? [modified] => [poll] => [public_bottom_line] =>

Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment.

That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while.

But if you’re interested, let this reassure you. If you want to talk about what home prices are doing in our market, your goals, or your timelines, reach out to a local agent.

[published_at] => 2026-05-18T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 107869 [content_type] => must-share [title] => 5/18 Must Share ) ) [shares] => 0 [slug] => are-home-prices-going-to-fall [status] => published [tags] => Array ( ) [title] => Are Home Prices Going To Fall? [updated_at] => 2026-05-18T10:30:12Z [url] => /2026/05/18/are-home-prices-going-to-fall/ )

Are Home Prices Going To Fall?

It’s one of the biggest hold ups some buyers have right now: “What if I buy, and home prices go down?”

24
stdClass Object
(
    [agents_bottom_line] => 

Online posts are going to make things sound worse than they are. If you want a true, data-bound look at what’s really happening in today’s market, lean on a real estate agent.

Let’s connect so you have someone to separate fact from fiction today.

[assets] => Array ( ) [banner_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260429/STM-Banner-20230116-Blog-original.jpg [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 9 [name] => Home Prices [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => home-prices [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Precios ) ) [updated_at] => 2019-06-03T18:18:43Z ) [2] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 35 [name] => Mortgage Rates [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => mortgage-rates [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Tasas de interés ) ) [updated_at] => 2019-06-03T18:18:43Z ) [3] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:06:50Z [id] => 320 [name] => Inventory [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:06Z [slug] => inventory [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Inventario ) ) [updated_at] => 2024-04-10T16:19:06Z ) ) [content_type] => blog [contents] =>

There’s a lot of uncertainty right now and that’s leading to some dramatic headlines. And if you’re thinking about buying a home, that can make you feel a little less sure about your decision.

A recent study by CNBC asked homebuyers what they’re most worried about, and three themes kept coming up again and again:

  • Mortgage rates
  • The number of homes for sale
  • Home prices

But a lot of what you may be hearing on those is based more on misconceptions. Not facts. So, let’s break it down and separate fact from fiction.

Misconception #1: “I’ll Just Wait, Because Mortgage Rates Are Going To Fall Dramatically”

One idea doing its rounds on social is that mortgage rates are going to drop dramatically soon. So, it’s better to wait to buy.

But is that really what’s expected?

While mortgage rates have come down a bit in the last few weeks, forecasts don’t show a major drop ahead. The most likely scenario is that rates stay somewhere in the low 6% range this year. 

And that’s not a big change from where rates are now (see graph below): 

a graph with numbers and linesOf course, this depends on where inflation and the economy go from here. But, based on what we know today, waiting for a big drop in rates may not work out the way some people hope. As U.S. News explains:

“Mortgage rates aren't expected to change much over the next several quarters . . .”

Not to mention, even with rates where they are today, it’s already more affordable than a year ago. So, even if they don’t change much, it’s still better than it was.

Misconception #2: "There Are Too Many Homes for Sale Right Now”

You’ve probably heard inventory is up. And nationally, it is. The number of homes for sale is 8% higher than this time last year. But that's not a bad thing. In fact, it’s one of the reasons buyers have a bit more breathing room right now.

The problem is the headlines are making something good, sound bad. They’re focusing on how this is the most inventory we’ve had since 2019 or how many homes builders are building. And that can make it sound like the number of homes for sale is rising too far, too fast.

But that’s not what the bigger picture shows.

Data from Realtor.com proves that, even though inventory is up compared to last year, it’s still nearly 14% lower than it was during the last normal housing market (2017-2019):

While it can vary a lot based on where you live, only 9 states have more inventory than pre-pandemic today. That’s a key reason why there still aren’t enough homes for sale to trigger something like the crash back in 2008.
Misconception #3: “Home Prices Are About To Crash”

You’ve probably seen this one, too. The confusion is coming from the fact that some metros are experiencing slight price declines. And influencers are running with that and saying prices are crashing. But that’s not the reality.

Most areas are seeing prices rise, not fall. And that’s because:

  • Many homeowners aren’t selling because they don’t want to give up the low mortgage rate they locked in a few years ago. And that’s keeping a lid on how much inventory can grow.
  • Since inventory is still below pre-pandemic norms, there aren’t enough homes for sale to cause a price crash.
  • And even in markets with more inventory, some sellers are choosing to pull their homes off the market instead of cutting prices.

And those are 3 big reasons prices aren’t headed for a crash. 

And even in the markets experiencing mild declines, the drops aren’t enough to cancel out the big gains most homeowners have seen in the last 5 years (see graph below):

That’s not a crash. That’s just prices moderating after a few record-breaking years.
[created_at] => 2026-04-21T19:04:02Z [description] =>

There’s a lot of uncertainty right now and that’s leading to some dramatic headlines.

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260421/Header-Image-20230116-Blog-original.png [id] => 106860 [kcm_ig_caption] => Online posts are going to make things sound worse than they are. If you want a true, data-bound look at what’s really happening in today’s market, lean on a real estate agent. Let’s connect so you have someone to separate fact from fiction today. [kcm_ig_hashtags] => MortgageRates,HomePrices,KeepingCurrentMatters [kcm_ig_quote] => Here are 3 things that are not going to happen in today's housing market. [modified] => [poll] => [public_bottom_line] =>

Online posts are going to make things sound worse than they are. If you want a true, data-bound look at what’s really happening in today’s market, lean on a real estate agent.

Connect with a local agent so you have someone to separate fact from fiction today.

[published_at] => 2026-04-23T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 106861 [content_type] => must-share [title] => 4/23 Must Share ) ) [shares] => 0 [slug] => 3-things-that-are-not-going-to-happen-in-todays-housing-market [status] => published [tags] => Array ( [0] => exclude ) [title] => 3 Things That Are Not Going To Happen in Today's Housing Market [updated_at] => 2026-04-23T10:30:18Z [url] => /2026/04/23/3-things-that-are-not-going-to-happen-in-todays-housing-market/ )

3 Things That Are Not Going To Happen in Today's Housing Market

There’s a lot of uncertainty right now and that’s leading to some dramatic headlines.

25
stdClass Object
(
    [agents_bottom_line] => 

More fresh listings are hitting the market right now, and that’s creating real opportunity.

If you put your search on hold last year, this Spring may be the time to jump back in. Let’s take a look at what just hit the market and see what could work for you.

[assets] => Array ( ) [banner_image] => [can_share] => no [categories] => Array ( [0] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2019-06-03T18:18:43Z [id] => 5 [name] => For Buyers [parent] => [parent_id] => [published_at] => 2019-06-03T18:18:43Z [slug] => buyers [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Para los compradores ) ) [updated_at] => 2019-06-03T18:18:43Z ) [1] => stdClass Object ( [category_type] => standard [children] => [created_at] => 2024-04-10T16:06:50Z [id] => 320 [name] => Inventory [parent] => [parent_id] => [published_at] => 2024-04-10T16:19:06Z [slug] => inventory [status] => public [translations] => stdClass Object ( [es] => stdClass Object ( [name] => Inventario ) ) [updated_at] => 2024-04-10T16:19:06Z ) ) [content_type] => blog [contents] =>

Did you try to buy a home last year, but you ended up pressing pause?

Maybe you couldn’t find a home that really fit your needs. Or maybe the ones you liked just weren’t affordable. According to a recent survey from NerdWallet, those were the top two reasons buyers gave up on their search in 2025.

But this Spring, there's one trend that could help fix both of those frustration points: more homes are hitting the market.

The Number of Fresh Listings Is Almost 2x Higher Than a Few Months Ago

Data from Realtor.com shows there are nearly 2x as many new listings hitting the market today as there were just 3 months ago. Those are homes the seller just put up for sale (see graph below):

a graph of a bar chartThat’s a significant rise. And while we usually see an uptick as we head into the busiest time of the year, this increase was bigger than normal. Jake Krimmel, Senior Economist at Realtor.com, explains:

“New listings jumped 21.2% from February to 439,000, a larger-than-typical seasonal surge . . . March typically sees the biggest month-over-month jump in new listings of the entire buying season, averaging an 18% increase since 2017; this year it exceeded 20%.”

That means more sellers are jumping back into the market, and that’s giving buyers more fresh options to choose from. So, if you’d felt like you’d seen everything out there and still nothing was quite right, this may be your moment.

With that many “just listed” homes, one of them could be exactly what you’ve been searching for.

Where You Have More Options

And this trend is happening across most of the country, so you should have more options pretty much whereever you are.

Earlier this year, the Northeast had fewer new listings because winter storms delayed sellers from putting their homes on the market. But now, that region is catching up fast.

In March, new listings jumped across nearly every state, especially in the Northeast, helping drive a strong national rebound.

What Rising Inventory Means for You

Right now, there are almost a million homes for sale nationwide. That’s up over 8% compared to last year.

With that many homes on the market, there’s a much better chance something will fit what you’re looking for, especially with so many fresh options being added right now. As Odeta Kushi, Deputy Chief Economist at First American, explains:

“One of the most encouraging signals heading into the spring home-buying season is the improvement in for-sale inventory levels compared with last year. . . More homes on the market give buyers greater choice and, combined with improved buying power, expand the range of homes they can realistically consider.”

In other words, your search may feel very different this year.

[created_at] => 2026-04-21T18:43:21Z [description] =>

Did you try to buy a home last year, but you ended up pressing pause?

[exclusive_id] => [expired_at] => [featured_image] => https://files.keepingcurrentmatters.com/KeepingCurrentMatters/content/images/20260421/Header-Image-GettyImages-814730874-original.png [id] => 106857 [kcm_ig_caption] => More fresh listings are hitting the market right now, and that’s creating real opportunity. If you put your search on hold last year, this Spring may be the time to jump back in. Let’s take a look at what just hit the market and see what could work for you. [kcm_ig_hashtags] => SpringHousingMarket,NewListings,KeepingCurrentMatters [kcm_ig_quote] => More options are popping up this spring. [modified] => [poll] => [public_bottom_line] =>

More fresh listings are hitting the market right now, and that’s creating real opportunity.

If you put your search on hold last year, this Spring may be the time to jump back in. Connect with a local real estate agent to see what’s newly available in your area.

[published_at] => 2026-04-22T10:30:00Z [related] => Array ( ) [related_to] => Array ( [0] => stdClass Object ( [id] => 106858 [content_type] => must-share [title] => 4/22 Must Share ) ) [shares] => 0 [slug] => more-options-are-popping-up-this-spring [status] => published [tags] => Array ( [0] => foundations ) [title] => More Options Are Popping Up This Spring [updated_at] => 2026-04-22T10:30:17Z [url] => /2026/04/22/more-options-are-popping-up-this-spring/ )

More Options Are Popping Up This Spring

Did you try to buy a home last year, but you ended up pressing pause?